If someone set fire to your home, an Arson Homeowners Claim Morrisville NC is generally covered by your homeowners policy — as long as you, the policyholder, did not set it. The catch is that carriers investigate arson losses harder than almost any other claim, and innocent homeowners often get treated like suspects while their payment sits frozen. For The Public Adjusters, Inc. is a licensed and bonded public adjusting firm that represents you, not the insurance company, through that investigation and settlement.
What This Service Is
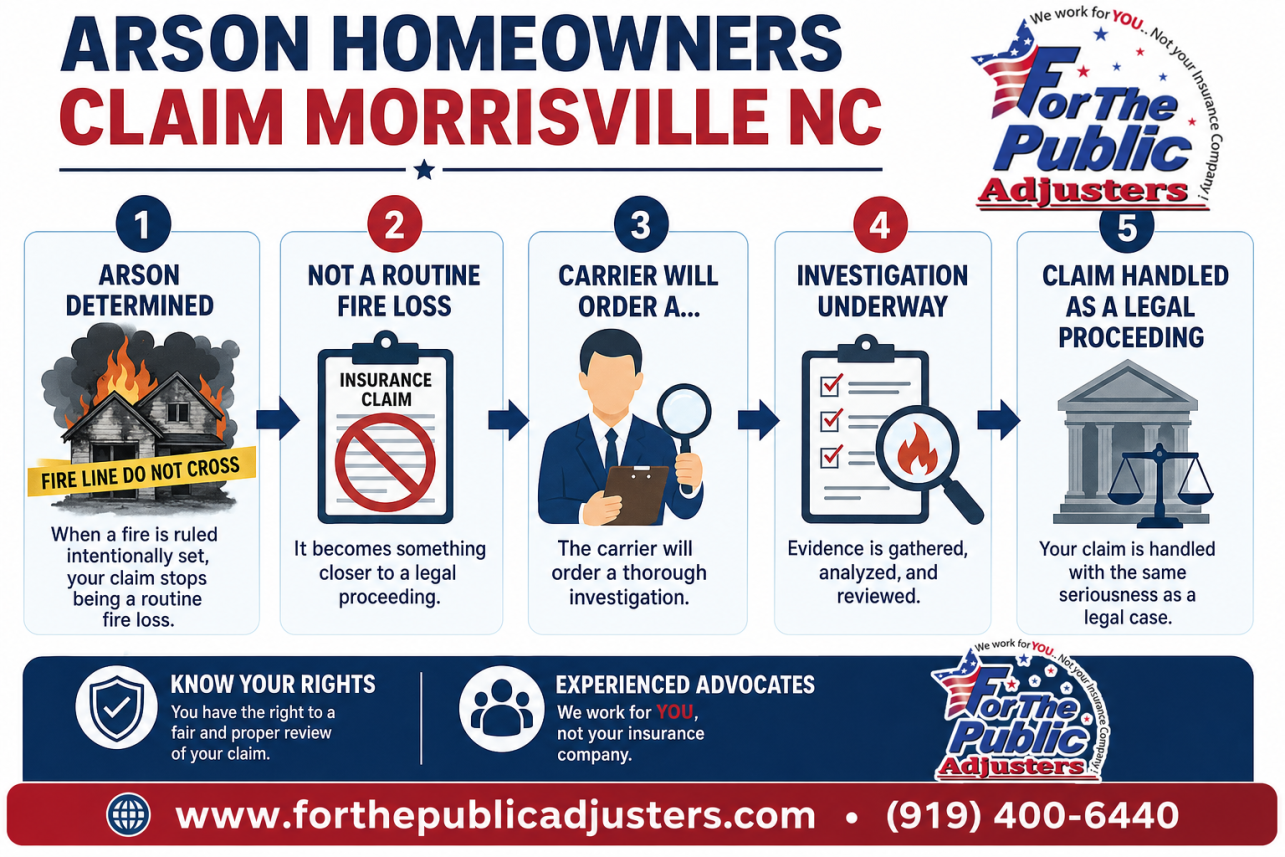
When a fire is ruled intentionally set, your claim stops being a routine fire loss and becomes something closer to a legal proceeding. The carrier will order a cause and origin investigation, review your finances for a supposed motive, and may require a recorded statement or a formal examination under oath before paying a dime.
Our job as your Morrisville public adjuster is to manage that entire process on your side of the table. We document the structure damage, the smoke contamination, and every item of personal property; we prepare the sworn proof of loss the policy requires; and we negotiate the valuation with the carrier's adjuster so you are not accepting their first number.
Arson losses rarely stay contained to one room. Smoke travels through HVAC systems, water from firefighting soaks framing and insulation, and accelerants can contaminate materials that look untouched. We handle the fire damage claim, the related fire damage insurance claim help in Knightdale and across Wake County, plus smoke and water damage claims that ride along with it, so nothing covered gets left out of the settlement.
We work these cases throughout the Triangle — including an arson claim in Chapel Hill looks very similar to one here — and we never guarantee a specific dollar outcome, because no honest adjuster can. What we can do is make sure the claim is documented, valued, and pressed properly.
Common Problems
Is Arson Covered By Home Insurance — And Will They Actually Pay Full Value?
Yes, arson committed by someone else — a vandal, an intruder, even a disgruntled acquaintance — is covered under standard homeowners policies, whether yours is with USAA, State Farm, or any other carrier. What is excluded is a fire set by the insured. That exclusion is exactly why carriers scrutinize these claims so aggressively.
Even when coverage is accepted, the payment is often short. Smoke saturation gets priced as a cleaning job instead of replacement, the personal property inventory misses hundreds of items, and loss of use benefits — the money that pays for temporary housing while you cannot live in the home — get cut off early.
If the house is a total loss, your mortgage lender will be named on the check and has its own requirements, which adds another layer most homeowners have never dealt with. Each of these is a fight about dollars, and each one is winnable with the right documentation.
Why Is My Arson Homeowners Claim Morrisville NC Stuck Under Investigation?
Carriers are allowed to investigate a suspicious fire, but they are not allowed to use the investigation as an excuse to stall indefinitely. A claim suspended for months while the fire marshal, the carrier's independent fire investigator, and a special investigations unit all take turns is a real hardship when you are paying for a hotel out of pocket.
Know that a criminal investigation and your insurance claim are separate tracks. Police need proof beyond a reasonable doubt; your carrier must pay unless it can actually prove you set the fire. Courts have held carriers accountable when they get this wrong — in Hayseeds, Inc. v. State Farm Fire & Casualty, a West Virginia jury rejected the insurer's arson defense after a building fire, the policyholder recovered the loss, and the court ruled that an insured who substantially prevails is also entitled to attorney fees.
If you are asked to sit for an examination under oath or submit a proof of loss, do not wing it. Mistakes in those documents are how legitimate claims get denied. You can also file a complaint with state regulators; the North Carolina Department of Insurance oversees how carriers handle claims in this state.
Should I Deal With The Insurance Company Myself, Or Hire Someone?
You can handle a routine claim yourself. An arson loss is not routine. The carrier has a cause and origin expert, a special investigator, and often defense counsel involved before you have even found a place to sleep. Facing that alone, while grieving the loss of your home, is how underpayments and denials happen.
A licensed public adjuster is the only professional, other than an attorney, legally allowed to negotiate a property claim on your behalf in North Carolina. The NCDOI Public Adjusters Guide explains what we do and confirms that our fee comes from the settlement — typically a percentage — so there is no upfront cost to you.
When you compare firms, ask whether they have handled arson losses specifically, whether they are licensed and bonded, and whether they will attend the examination under oath preparation with you. We handle these claims across Wake County, from Morrisville to an arson homeowners claim in Fuquay-Varina, and we are glad to answer those questions directly.
Our Process
Immediate Review And Policy Analysis
We read your full policy — not the summary page — and identify every coverage that applies: dwelling, other structures, personal property, loss of use, and debris removal. We also flag deadlines, including the statute of limitations on your claim, so nothing expires while the investigation drags on.
Independent Damage Documentation
We inspect and document the entire loss ourselves rather than relying on the carrier's numbers: structural fire damage, smoke penetration in walls and ductwork, water damage from suppression, and a room-by-room personal property inventory with replacement values. This becomes the sworn proof of loss the policy requires.
Negotiation Through Final Settlement
We present the claim, respond to the carrier's investigators, prepare you for any examination under oath, and negotiate every line item. If the carrier delays unreasonably or denies without proof, we document the conduct and, where warranted, work alongside insurance dispute lawyers to escalate. You stay informed at every step.
| What Happens After a Suspicious Fire | Handling It Alone | With For The Public Adjusters |
|---|---|---|
| Examination under oath | You answer sworn questions unprepared, and inconsistencies get used against you | You're prepared in advance, documents are organized, and your statements align with the evidence |
| Cause-and-origin findings | You rely on the carrier's investigator, who was hired by the company denying your claim | An independent certified fire investigator examines the scene before evidence is destroyed |
| Proof of loss deadline | Easy to miss while the investigation drags — and missing it can sink the claim | Sworn proof of loss prepared, documented, and submitted on time |
| Contents and smoke damage | Kitchen and burn rooms get scoped; soot contamination in the rest of the house is ignored | Full inventory plus soot and chloride testing throughout the home |
| Additional living expenses | Payments freeze during the investigation and you absorb rent out of pocket | ALE is documented, pursued, and claimed retroactively where owed |
| Leverage against a wrongful denial | You take the denial at face value | North Carolina policyholders have won fire-loss denials in court — Bryant v. Nationwide Mutual Fire Ins. Co., 313 N.C. 362 (1985) — and we build the record that supports that pressure |
Commonly Overlooked In The Public Adjusting Industry
- Scene preservation before demolition — Homeowners understandably want the burned structure cleared fast, but once it's gone, the physical evidence that disproves arson is gone with it.
- The sworn proof of loss deadline under the North Carolina standard fire policy — Families consumed by the investigation assume the clock pauses while the SIU works — it doesn't, and a missed proof of loss hands the carrier an easy out.
- Third-party arson is still a covered loss — People hear the word 'arson' and assume the claim is dead, when a fire set by a vandal or intruder is exactly what the policy insures against.
- Smoke, soot, and chloride contamination in rooms that never burned — Carrier scopes stop at the burn line, but corrosive soot in ductwork, electronics, and soft goods quietly destroys contents house-wide.
- Examination under oath preparation — Most policyholders treat the EUO like a casual interview, not realizing it's a sworn record the carrier builds specifically to support a denial.
- Retroactive additional living expenses after an investigation hold — Once ALE payments freeze, families stop tracking receipts, then can't recover months of legitimate housing costs when the hold lifts.
- False-positive 'pour patterns' from melted plastics and flashover — Carrier investigators sometimes read ordinary post-flashover burn patterns as accelerant evidence, and nobody challenges it without an independent expert.
- Code-required rebuild upgrades in Wake County estimates — Initial carrier estimates price a like-for-like repair, ignoring current electrical, smoke-sealing, and permitting requirements that significantly raise the true cost.
Case Studies
Case Study #1
Situation: A family in Morrisville's Kitts Creek neighborhood came home from a weekend in Wilmington to find their two-story home heavily damaged by fire. The fire marshal's preliminary report listed the cause as 'incendiary,' and within days the carrier's Special Investigations Unit took over the file.
Problem: The insurer's cause-and-origin investigator concluded an accelerant was used near the garage, and the SIU began building an arson defense — requesting bank statements, demanding an examination under oath, and freezing all payments, including additional living expenses. The family was paying a mortgage and a Cary rental out of pocket.
Investigation: We photographed and preserved the scene before demolition, retained an independent certified fire investigator, and pulled the family's cell records, toll data from I-40, and hotel receipts proving they were three hours away when the fire started. We also documented a pattern of break-ins reported on neighboring streets to Morrisville Police in the prior sixty days.
Findings: The independent investigator found the 'accelerant pour pattern' the carrier relied on was actually a melted plastic fuel pattern from stored lawn equipment — a known false positive. The side garage door showed pry marks consistent with forced entry that the carrier's investigator never documented.
Solution: We prepared the family for their examinations under oath, submitted a sworn proof of loss within the policy deadline, and delivered a rebuttal report with the forensic findings, the alibi evidence, and the forced-entry documentation. We reminded the carrier that under North Carolina law — as the state Supreme Court recognized in Bryant v. Nationwide Mutual Fire Insurance Co., 313 N.C. 362 (1985), where a homeowner prevailed after a fire-loss denial and the court allowed claims for bad-faith refusal to settle — an insurer that denies without a reasonable basis exposes itself to liability well beyond the policy limits.
Outcome: The carrier withdrew its arson defense, reopened additional living expenses retroactively, and paid the dwelling, contents, and ALE claims. The family rebuilt on the same lot.
Lesson: An 'incendiary' label on a fire report is not proof the homeowner set the fire. Third-party arson is a covered loss, and the evidence that proves it disappears fast once demolition starts — so the scene must be preserved and independently examined immediately.
Case Study #2
Situation: A retired couple near Church Street in Morrisville suffered a kitchen fire that spread into the attic while they were at a doctor's appointment in Durham. Because the husband had recently been laid off and the home carried a second mortgage, the carrier flagged the file for financial-motive investigation.
Problem: The insurer paid nothing for four months while it subpoenaed financial records and interviewed neighbors. Smoke and soot had contaminated contents in every room, but the carrier's adjuster scoped only the kitchen and attic, valuing the loss at a fraction of what rebuilding would actually cost in Wake County.
Investigation: We ordered a complete independent origin-and-cause analysis, which traced the fire to a failed wiring connection behind the range — a manufacturer-recognized defect. We then performed a room-by-room contents inventory, over 1,900 line items, and had soot sampling done to document chloride contamination on electronics and HVAC ductwork throughout the house.
Findings: There was no accelerant, no unexplained ignition source, and no physical evidence of intent — only a financial-motive theory. The carrier's scope also omitted code-required electrical upgrades, smoke sealing, duct cleaning, and pack-out costs, understating the structural claim significantly.
Solution: We submitted the electrical-failure findings, the full contents inventory, and a rebuilt structural estimate reflecting current Wake County permit and code requirements. We cited Bryant v. Nationwide Mutual Fire Insurance Co., the North Carolina fire-loss case in which the policyholder won and the court held that aggravated, bad-faith claim conduct can support punitive damages, and asked the carrier to either produce actual evidence of intent or pay the claim.
Outcome: The carrier dropped the investigation, and the final settlement covered the structure, code upgrades, full contents replacement, and the couple's temporary housing. It resolved at several times the carrier's original scope.
Lesson: Financial hardship is not evidence of arson, and carriers know it. A documented accidental cause plus a complete, defensible inventory shifts the conversation from suspicion back to what the policy owes.
| What the Insurer Does | What It Usually Means | Smart Next Step |
|---|---|---|
| Fire marshal lists cause as 'incendiary' or 'undetermined' | The carrier will likely assign the Special Investigations Unit and slow all payments | Preserve the scene — do not demolish or discard anything — and get independent representation before giving recorded statements |
| Request for an examination under oath | The carrier is building a formal record it can use to deny; this is a policy condition you generally must attend | Never go in unprepared; organize finances, alibi evidence, and documents first |
| Subpoena-style requests for bank and credit records | The carrier is testing a financial-motive theory | Provide what the policy requires, but with context — hardship alone is not proof of arson |
| Reservation of rights letter arrives | The carrier is paying attention to exclusions and preserving its right to deny later | Keep performing every policy duty on time, especially the sworn proof of loss |
| ALE and advances suddenly stop | The investigation has shifted from the fire to you | Document every housing and living expense now so it can be claimed retroactively |
| Carrier's investigator claims 'pour patterns' or accelerant | These findings have known false positives from melted plastics and flashover | Retain an independent certified fire investigator to test the conclusion |
| Evidence the fire was set by a third party | Arson by a stranger or vandal is still a covered loss under a homeowners policy | Document forced entry, police reports, and neighborhood incident history immediately |
| Outright denial citing the intentional-acts exclusion | The carrier believes its file supports a jury argument — but courts have sided with homeowners, as in Bryant v. Nationwide (N.C. 1985) | Have the full claim file, forensics, and policy reviewed before accepting the denial as final |

Reviews
After our house fire off Morrisville-Carpenter Road, the insurance company's investigator started asking about our finances instead of our damage. It was terrifying. For The Public Adjusters brought in their own fire investigator, prepared us for the examination under oath, and proved the fire started in a bathroom exhaust fan. The denial threat disappeared and the claim finally got paid properly. I can't imagine facing an Arson Homeowners Claim Morrisville NC situation without them.
Deepa R., Morrisville
The fire department report said 'undetermined' but our carrier's SIU treated us like suspects for months. These adjusters got the scene preserved before demolition, documented pry marks on our back door the carrier's investigator ignored, and tracked every proof of loss deadline so nothing lapsed. The arson defense was dropped and we settled for the structure and all our contents. Professional, calm, and relentless.
Marcus T., Kitts Creek
A vacant rental property we own in Morrisville was set on fire by vandals, and the insurer tried to use both the vacancy and an arson theory against us. For The Public Adjusters knew exactly how the vacancy clause actually read, documented the forced entry, and built the contents and structural claim line by line. The only reason this isn't my first review is that it took longer than I hoped — but that was the carrier dragging, not them.
Janet W., near Town Hall Drive
Frequently Asked Questions
What Should I Do First After A Fire If My Insurer Suspects Arson In Morrisville, NC?
The first steps matter enormously. Once the Morrisville Fire Department and Wake County investigators clear the scene, document everything before anything is moved or cleaned. Photograph every room, charred contents, and structural damage, and keep all receipts for temporary housing and emergency expenses.
Notify your insurance carrier promptly, but be careful with recorded statements. When an insurer suspects an intentional fire, everything you say becomes part of its investigation file. You have the right to have a licensed representative present and to review your policy before giving detailed statements.
Do not sign any non-waiver agreements or proof-of-loss documents without understanding what they mean. Insurers often request an Examination Under Oath in suspected arson cases, and how you prepare for it can shape the entire claim.
It also helps to know the law favors policyholders who stand their ground. In Bryant v. Nationwide Mutual Fire Insurance Co., 313 N.C. 362 (1985), a North Carolina homeowner's house burned and the insurer denied the claim alleging arson. The North Carolina Supreme Court ruled in favor of the insured, holding that an innocent co-insured spouse could recover under the policy even where the insurer blamed the other spouse for the fire. That decision still protects honest Wake County homeowners today.
As a licensed and bonded public adjusting firm, we step in early to protect your documentation, your statements, and your right to a fair settlement. We cannot guarantee any specific outcome, but early professional guidance often prevents the missteps insurers use to justify delays or denials.
How Does A Public Adjuster Help With An Arson Homeowners Claim Morrisville NC Policyholders Are Facing?
An Arson Homeowners Claim Morrisville NC residents deal with is one of the most adversarial situations in property insurance, because the carrier is actively looking for reasons to deny. A public adjuster works exclusively for you, the policyholder, never for the insurance company.
First, we review your full policy, including dwelling, other structures, contents, and additional living expense coverage. Many Morrisville homeowners in neighborhoods like Breckenridge, Kitts Creek, and Town Hall Commons discover coverage they did not know they had.
Second, we build the damage estimate independently. Fire losses involve more than visible charring; smoke penetrates HVAC systems, insulation, and framing, and water from suppression efforts causes secondary damage. We document all of it line by line so the carrier's estimate cannot quietly leave items out.
Third, we manage communications. When arson is alleged, adjusters and special investigation units scrutinize every statement. We help you respond accurately and completely while protecting your rights, including preparation for any Examination Under Oath.
North Carolina courts have made clear that insurers carry the burden of proving an arson defense. In Bryant v. Nationwide Mutual Fire Insurance Co., the state Supreme Court sided with the insured homeowner after the carrier denied a fire loss on arson grounds. We hold insurers to that standard throughout the claim.
We are licensed and bonded in North Carolina. While no one can promise a specific settlement figure, having a professional advocate typically means a more complete, better-documented claim than facing the carrier's investigators alone.
Can The Insurance Company Deny My Fire Claim Just Because The Fire Was Ruled Incendiary?
No, not automatically. An incendiary cause finding by fire investigators means someone intentionally set the fire. It does not mean you set it, and it does not by itself relieve the carrier of its obligation to pay.
Under North Carolina law, an insurer asserting an arson defense must prove two things: that the fire was intentionally set, and that the insured set it or procured it. Fires set by vandals, burglars, or unknown third parties are covered losses under a standard homeowners policy. In a growing area like Morrisville, with construction sites and vacant homes between tenants, third-party fires are not rare.
The Bryant v. Nationwide Mutual Fire Insurance Co. decision from the North Carolina Supreme Court illustrates how courts protect honest policyholders. There, the insurer refused to pay a fire loss by alleging arson, and the court ruled for the insured, allowing recovery under the policy. Insurers cannot simply point at the homeowner and walk away from the contract.
That said, carriers often use an incendiary finding to slow the claim, demand extensive financial records, and conduct Examinations Under Oath. Cooperation is required under your policy, but you are entitled to fair treatment and a reasonable investigation.
Our role is to keep the claim moving, document your dwelling and contents losses thoroughly, and push back when the carrier's position goes beyond what the evidence and the law support. We are licensed and bonded, and we advocate only for policyholders, never for insurance companies.
What Is Covered In An Arson-Related Homeowners Claim In Morrisville, And How Long Does The Process Take?
A standard homeowners policy in North Carolina typically covers the dwelling, detached structures like garages and sheds, personal contents, and additional living expenses while your home is uninhabitable. All of these apply to a fire loss, even one under arson investigation, as long as the carrier cannot prove you were responsible.
For Wake County homeowners, additional living expense coverage is especially important. Rental costs near Research Triangle Park and RDU are high, and displaced families often underestimate what they are entitled to recover for temporary housing, meals, and extra commuting costs.
Timelines vary widely. A straightforward fire claim may resolve in a few months. When a carrier opens a special investigation for a suspected intentional fire, expect document requests, recorded interviews, and possibly an Examination Under Oath, which can stretch the process to six months or longer. Thorough preparation and a complete, well-supported proof of loss usually shorten that timeline rather than lengthen it.
It is worth remembering that North Carolina courts have ruled against insurers who deny fire losses without carrying their burden of proof. In Bryant v. Nationwide Mutual Fire Insurance Co., the insured prevailed after the carrier denied a home fire claim on arson allegations.
For The Public Adjusters, Inc. handles an Arson Homeowners Claim Morrisville NC families bring to us with full documentation of structure and contents damage, careful management of the investigation phase, and persistent follow-up with the carrier. We are licensed and bonded, and while results depend on each policy and loss, our job is to pursue every dollar the contract allows.
What Does The Insurance Company Have To Prove Before Denying An Arson Homeowners Claim Morrisville NC Policyholders Submit?
In North Carolina, the burden of proving arson as a defense sits squarely on the insurance company, not on you. To deny a fire claim on arson grounds, the carrier generally must show three things: that the fire was intentionally set, that you had a motive, and that you had the opportunity to set it. Suspicion alone is not enough.
Courts across the country have held insurers to that standard. In Watson v. United Services Automobile Association, 566 N.W.2d 683 (Minn. 1997), the court ruled that an innocent co-insured spouse could still recover under the homeowners policy even though the other spouse intentionally set fire to the home. The insured won, and the decision reinforced that carriers cannot paint every household member with the same brush.
For a Morrisville homeowner, this matters because Wake County fire investigators may classify a fire as "incendiary" without ever identifying who set it. An incendiary ruling is not the same as proof that you did anything wrong. Our role as licensed and bonded public adjusters is to document the loss, challenge weak or circumstantial allegations, and keep the carrier focused on its contractual duty to pay covered damage to your dwelling and contents. While no one can guarantee a specific outcome, holding the insurer to its legal burden is often the difference between a stalled file and a fairly settled one.
Should I Agree To A Recorded Statement Or Examination Under Oath During An Arson Investigation On My Morrisville Fire Claim?
Most homeowners policies issued in North Carolina do require you to cooperate, which can include a recorded statement and, in suspected arson cases, a formal examination under oath (EUO). Refusing outright can give the carrier grounds to deny the claim for non-cooperation, so the answer is usually yes — but never unprepared.
An EUO in a suspected-arson file is not a casual conversation. The insurer's attorney will ask detailed questions about your finances, your whereabouts the day of the fire, your mortgage status, and the contents of the home. Innocent answers given carelessly can be twisted into "motive" or "opportunity."
Before any statement, we help Morrisville homeowners assemble documentation that supports the claim: the Wake County fire marshal's report, utility records, receipts and photos of contents, and a complete inventory of the damaged dwelling and personal property. If the questioning crosses into territory better handled by an attorney, we will tell you plainly that it is time to bring one in — public adjusters handle the claim, not criminal or coverage litigation.
Timing matters too. You are generally entitled to reasonable notice and to receive a copy of the transcript. Going in organized, with your damages fully documented, changes the tone of the entire investigation. Carriers move differently when they see the policyholder is represented, prepared, and holding them to the policy language rather than hoping for goodwill.
How Much Does It Cost To Hire A Public Adjuster For A Suspected-Arson Fire Loss In Morrisville?
For The Public Adjusters, Inc. works on a contingency-fee basis, which means our fee is a percentage of the insurance settlement — you pay nothing out of pocket up front, and nothing at all if there is no recovery. North Carolina regulates public adjuster contracts, and every agreement we use spells out the fee in writing before any work begins.
That structure matters in an arson-flagged file more than almost any other type of loss. These claims take longer, involve more scrutiny, and require far more documentation than a routine kitchen fire. You may face a Special Investigations Unit, an examination under oath, and repeated document requests. Paying hourly for that level of work would be out of reach for most Wake County families.
Our fee covers the full scope of claim handling: a room-by-room contents inventory, independent estimates for structural repairs to your home, coordination with the fire investigation findings, additional living expense tracking while you are displaced, and direct negotiation with the carrier's adjusters and attorneys. We are licensed and bonded in North Carolina.
One honest caveat: no public adjuster can promise a specific dollar amount, and you should be wary of anyone who does. What we can promise is thorough documentation and persistent advocacy. In our experience, fully documented fire losses in the Morrisville and Research Triangle area are frequently valued well above the carrier's initial figures, which is why the contingency model tends to work in the homeowner's favor.
Are Smoke, Soot, And Water Damage From Firefighting Covered In An Arson Homeowners Claim Morrisville NC Residents File?
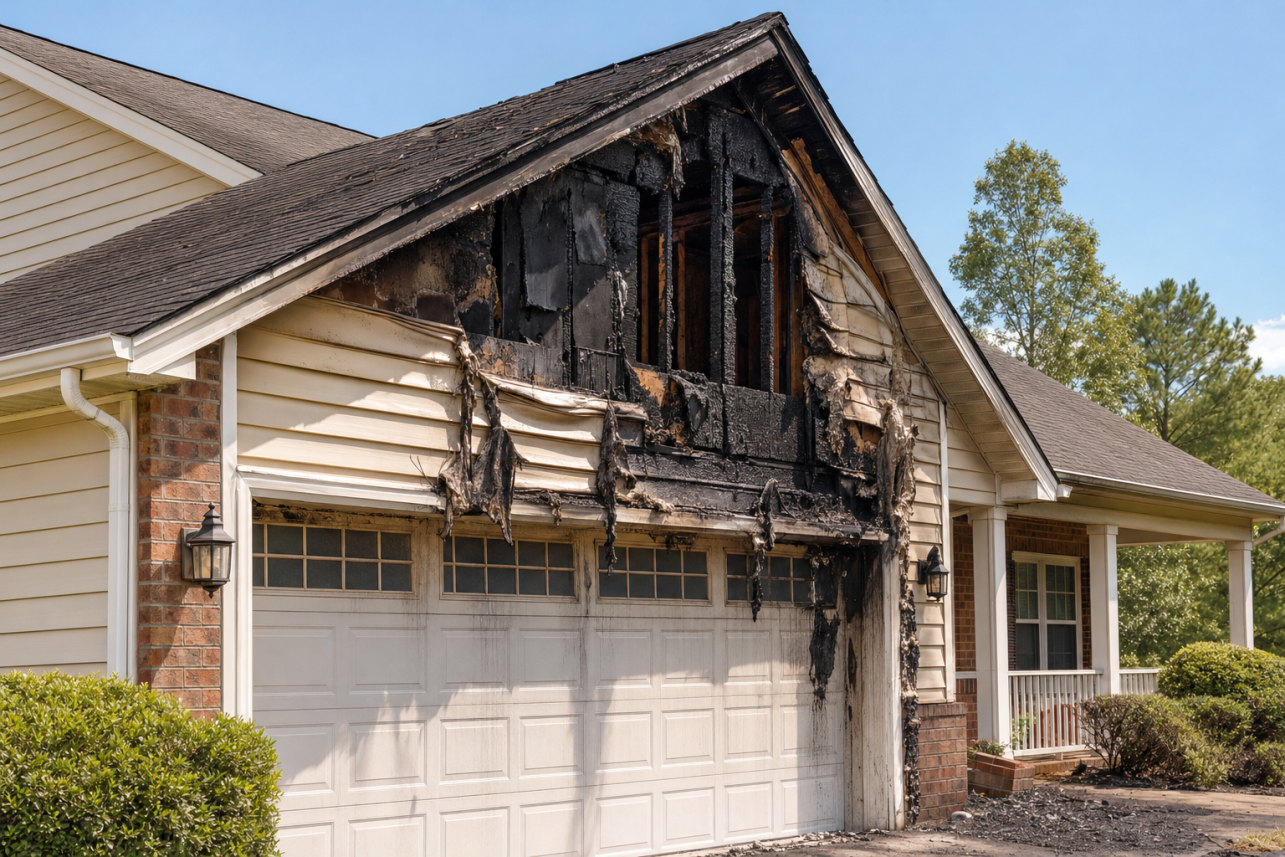
Yes — as long as the claim itself is covered, the damage caused by fighting the fire is part of the loss. When Morrisville Fire/Rescue or a neighboring Wake County department puts out a house fire, the water, foam, forced entry, and ventilation holes they create are all consequences of a covered peril. The same goes for smoke and soot migration into rooms the flames never touched.
This is one of the most undervalued parts of arson-flagged fire files. Carriers under investigation pressure sometimes scope only the burn area and ignore soot contamination in HVAC ducts, acidic smoke residue etching finishes, moisture trapped in wall cavities, and odor absorbed into insulation and framing. Left unaddressed, that damage leads to mold, corrosion, and lingering smoke smell months after repairs.
We document the full footprint of the loss: hygienist testing where appropriate, duct and cavity inspections, and line-item estimates that include demolition, drying, deodorization, and code-required upgrades under your ordinance-or-law coverage. Contents affected by smoke — clothing, electronics, upholstered furniture — are inventoried and valued separately from the structure.
Keep in mind the distinction between firefighting water and natural flooding. Water damage from hoses is a fire-claim issue; rising water from storms falls under separate flood coverage through the National Flood Insurance Program, and FEMA is the right resource for that. If an insurer tries to minimize suppression damage while the arson investigation drags on, insist on a complete scope — the policy covers the whole loss, not just the charred rooms.
Will My Additional Living Expenses Be Paid While An Arson Homeowners Claim Morrisville NC Investigation Is Still Open?
Most homeowners policies include Additional Living Expenses (ALE) coverage, and an open origin-and-cause investigation does not automatically suspend it. If your home off Davis Drive, Town Hall Drive, or anywhere else in Morrisville is uninhabitable after a fire, the carrier generally owes reasonable costs above your normal living expenses while the claim is being evaluated.
That said, some insurers slow-walk ALE payments when a fire is labeled suspicious. We push back on that. Unless and until the company can actually prove a valid defense, the policy remains in force, and delaying temporary housing money for a family in Wake County is a leverage tactic, not a legal requirement.
Practical steps matter here. Keep every receipt for lodging, meals above your normal grocery spend, pet boarding, laundry, and extra commuting costs. Rental rates near Research Triangle Park run high, so document comparable housing carefully — the carrier owes expenses consistent with your normal standard of living, not the cheapest option available.
As licensed and bonded public adjusters, we prepare and submit ALE demands in writing, tie each expense to policy language, and track the carrier's response deadlines under North Carolina's claims-handling standards. We cannot promise a specific payout, but we can make sure your temporary living costs are fully documented and formally presented so the insurer has no paperwork excuse to withhold them.
Has A North Carolina Homeowner Ever Beaten An Arson Accusation And Won Against The Insurance Company In Court?
Yes, and the leading example is a North Carolina Supreme Court decision that still protects policyholders today. In Bryant v. Nationwide Mutual Fire Insurance Co., 313 N.C. 362 (1985), a homeowner's dwelling and contents were destroyed by fire, and the insurer refused to pay, asserting the insureds had set it. The case went all the way to the state's highest court, and the policyholders prevailed.
The decision matters for anyone handling an Arson Homeowners Claim Morrisville NC insurers have flagged as suspicious, because it confirmed that the burden sits squarely on the insurance company. The carrier must prove its arson defense — including that the insured had both motive and opportunity — with actual evidence, not suspicion or innuendo. A fire being ruled incendiary in origin is not, by itself, proof the homeowner set it.
Bryant is the framework we work within every day in Wake County. When a carrier hints at arson to pressure a policyholder into a lowball settlement or a withdrawn claim, we document the loss thoroughly, demand the carrier identify its specific evidence, and hold it to the standard the Supreme Court established.
We are not attorneys and we do not litigate, but knowing the controlling case law shapes how we build the claim file. If a dispute does head toward appraisal or litigation, a well-documented file prepared from day one makes the policyholder's position far stronger. No outcome can ever be guaranteed, but Bryant shows North Carolina homeowners can and do win these fights.
My Morrisville House Was Set On Fire By Vandals Or An Unknown Third Party — Does My Homeowners Policy Still Cover That?
In most cases, yes. Fire is a named peril under virtually every homeowners policy, and that includes fires intentionally set by someone other than the insured. If a vandal, burglar, disgruntled acquaintance, or complete stranger set fire to your Morrisville home, the policy's arson exclusion generally does not apply to you, because that exclusion targets fires set by or at the direction of the policyholder.
The complication is that the carrier may still open a thorough investigation to rule you out before paying. The Morrisville Fire Department and, in larger losses, Wake County fire investigators will document origin and cause, and the insurer will often retain its own origin-and-cause expert. Cooperate with law enforcement — a police report naming you as the victim of a crime is powerful evidence in your favor.
Meanwhile, your claim still needs to be built properly. Structural damage, smoke and soot migration into HVAC systems and wall cavities, and a complete contents inventory all have to be documented and valued. Third-party arson fires often involve accelerants, which can push smoke contamination farther through a home than an accidental fire would.
Our team prepares the full damage estimate, the room-by-room contents inventory, and the supporting documentation showing you had no involvement. We present it to the carrier as one coherent package. While no specific result can be promised, a victim of arson should never be treated like a suspect, and a well-organized claim file helps keep the focus where it belongs — on paying for your loss.
How Does My Mortgage Company Get Involved When I File An Arson-Related Homeowners Claim In Morrisville?
If you have a mortgage, your lender is almost certainly listed on the policy as a mortgagee, and that changes how claim checks are handled. Settlement payments for dwelling damage are typically made jointly to you and the lender, and the mortgage company will usually hold the funds in escrow and release them in draws as repairs are completed and inspected.
There is an important protection here too. Most policies contain a standard mortgage clause, which means the lender's right to payment can survive even if the carrier raises a defense against the homeowner. In arson disputes, that clause sometimes results in the insurer paying the lender while continuing to contest the homeowner's portion — a situation that demands careful documentation on your side.
For a homeowner in Morrisville working through an arson-flagged fire loss, coordination matters. The lender will want the insurer's estimate, a signed repair contract, and proof your property taxes and payments are current. Delays in any one of those pieces can stall the rebuild on your Wake County property even after the carrier agrees to pay.
We handle that coordination as part of representing you on an Arson Homeowners Claim Morrisville NC families are trying to resolve. That means preparing the repair estimate the lender relies on, supplying draw-request documentation, and keeping the insurer, contractor, and mortgage servicer working from the same numbers. We cannot guarantee a particular settlement amount, but we can keep the moving parts organized so lender requirements never become the reason your recovery stalls.
What Evidence Should I Gather On My Own To Support An Arson Homeowners Claim Morrisville NC Insurers Are Investigating?
Start with documentation that proves two things: the value of what you lost and your whereabouts and circumstances around the time of the fire. For the loss itself, collect photos and video of the damage before anything is moved, receipts, credit card statements, and any pre-fire photos of your home's interior that show your contents in place.
For the investigation side, keep records that establish a normal financial picture — mortgage statements showing you were current, bank records, and proof of employment. Insurers in suspected-arson cases look hard at motive, so evidence that you had no financial pressure is genuinely valuable. Save your alibi details too: phone records, toll transponder data from I-40 or NC-540, work badge swipes, or doorbell camera footage from neighbors near your Morrisville street.
Request a copy of the fire report from the Town of Morrisville Fire/Rescue Department and, if the Wake County or state fire marshal investigated, ask about the cause-and-origin findings. You are entitled to know what the official record says.
Finally, keep a written log of every call, visit, and letter from the insurance company, including names and dates. Carriers must handle claims in good faith under North Carolina law, and a clean paper trail protects you if the handling turns unfair. As licensed and bonded public adjusters, we help Morrisville homeowners organize this evidence into a documented, professionally presented claim — though no one can guarantee a specific outcome, thorough proof consistently puts policyholders in a far stronger position.
I Was Never Arrested Or Charged With Setting The Fire — Can My Insurer Still Accuse Me And Withhold Payment?
Yes, and this surprises many Morrisville homeowners. A criminal arson charge requires proof beyond a reasonable doubt, but an insurance company only needs to meet a civil standard — the greater weight of the evidence — to raise an arson defense. So even if the Wake County District Attorney never files charges, or charges are dropped, the carrier can still investigate you and attempt to deny the claim.
That said, the absence of criminal charges works in your favor. If trained fire investigators and prosecutors reviewed the scene and declined to pursue you, that undercuts the insurer's theory. Your file should make that point loudly and with documentation.
Courts have sided with homeowners in exactly this posture. In Watson v. United Services Automobile Association, the insured recovered for fire damage to her home even though the carrier denied the claim based on arson allegations tied to her estranged spouse — the court held an innocent policyholder could not be stripped of coverage for a fire she did not set. Decisions like that one show insurers do not get the final word; juries and judges do.
The practical danger is that an unrepresented homeowner says something during a recorded interview or examination under oath that the carrier later twists into 'evidence.' A Morrisville public adjuster documents your loss, keeps the valuation fight separate from the accusation fight, and coordinates with your attorney if the denial needs to be challenged. We cannot promise a specific result, but we can make sure the record reflects the truth.
My Spouse Or Another Person Named On The Policy Allegedly Set The Fire. Am I Out Of Luck On Our Morrisville Home?
Not necessarily. This situation falls under what courts call the innocent co-insured doctrine, and it can preserve your right to recover even when another insured is accused of intentionally starting the fire.
The outcome often turns on the exact policy wording. Older policies excluded coverage for loss caused by 'an insured' or 'the insured,' and courts have read those phrases very differently. Where the policy protects each insured's interest separately, an innocent spouse can frequently recover her share of the dwelling and contents loss even if the other spouse is blamed.
The Watson v. United Services Automobile Association decision is a leading example: the court allowed the innocent wife to recover for the fire loss to the family home despite the insurer's arson defense aimed at her husband, reasoning that statutory fire coverage protected her independent interest. North Carolina courts likewise scrutinize whether an exclusion can fairly be applied to a policyholder who did nothing wrong.
In practice, this means a Morrisville homeowner in this position should never accept a blanket denial at face value. Your separate ownership interest in the Wake County property, your mortgage obligations, and your personal contents all matter, and each needs to be valued and asserted on its own.
Our team reviews the specific exclusion language in your policy, documents your individual interest in the home and belongings, and prepares the claim so your recovery is argued on your facts — not lumped in with accusations against someone else. Where litigation becomes necessary, we work alongside your attorney. No guarantees are ever possible, but innocent co-insureds have real, court-recognized rights.
How Does The Official Fire Investigation In Morrisville Affect My Insurance Payout, And What If Investigators Got The Cause Wrong?
The cause-and-origin determination drives everything in an Arson Homeowners Claim Morrisville NC families pursue. When Town of Morrisville Fire/Rescue or a Wake County or state investigator labels a fire 'incendiary' or 'undetermined,' the insurance company's Special Investigations Unit typically opens its own parallel inquiry, hires its own origin-and-cause expert, and slows the claim while it builds a file.
Here is what matters: an 'incendiary' finding means someone intentionally set the fire — it does not mean you set it. Vandalism, a break-in, a dispute with a third party, or juvenile fire-setting can all produce an incendiary ruling, and your homeowners policy still covers fires set by someone other than an insured.
Fire science is also not infallible. Findings must follow NFPA 921, the recognized standard for fire investigation, and conclusions based on outdated indicators — alleged 'pour patterns,' crazed glass, or burn depth myths — have been successfully challenged. If the official cause determination rests on shaky methodology, a qualified independent fire expert can re-examine the scene evidence, and that rebuttal can change the entire posture of your claim.
As public adjusters, we read the official reports line by line, flag conclusions that conflict with the physical evidence, and bring in independent experts when the facts call for it. Meanwhile, we keep the damage side moving: documenting structure, smoke, soot, and firefighting-water damage so your claim's value is fully established the moment the coverage question resolves. We never promise a particular dollar figure, but we make certain the investigation's conclusions are tested rather than simply accepted.
Local Relevance
Morrisville sits in the heart of western Wake County, with much of its housing built during the late-1990s through mid-2000s boom that filled the area around RTP. These are mostly wood-framed, open-floor-plan homes where fire and smoke spread quickly, so even a fire set at an exterior door or garage can contaminate the entire house.
The town's workforce is also unusually mobile. Corporate relocations mean homes here sit vacant between owners or tenants more often than in older parts of the Triangle, and vacant properties are more likely targets for vandalism and set fires — and more likely to trigger vacancy questions from the carrier.
The National Fire Protection Association publishes extensive research on intentional fires, and the pattern it describes nationally holds here: these losses are investigated differently from accidental fires from the first hour. That is why local representation matters. We serve all of western Wake, including homeowners needing arson homeowners claim help in Apex, and we know how Triangle carriers and their investigators tend to work these files.
Because so many Morrisville households relocate for RTP jobs, homes here often sit empty between a move-out and a sale or new lease — and that is precisely when set fires and vandalism tend to occur, and when carriers start asking about vacancy provisions in the policy. Knowing how to document occupancy history and push back on a vacancy-based denial is often half the battle in a Morrisville arson loss.
Treated Like A Suspect After Someone Burned Your Home?
You did nothing wrong, and you should not face the insurance company's investigators alone. For The Public Adjusters, Inc. is licensed and bonded in North Carolina, and we represent Morrisville homeowners from the first inspection through final settlement. The consultation is free, and we only get paid when you do.
Call us: (919) 400-6440
Helpful Resources
- NCDOI Public Adjusters Guide
- National Fire Protection Association (NFPA)
- North Carolina Department of Insurance — State regulator for insurance claims and adjusters
Serving Morrisville · Wake
Last updated: October 25, 2026