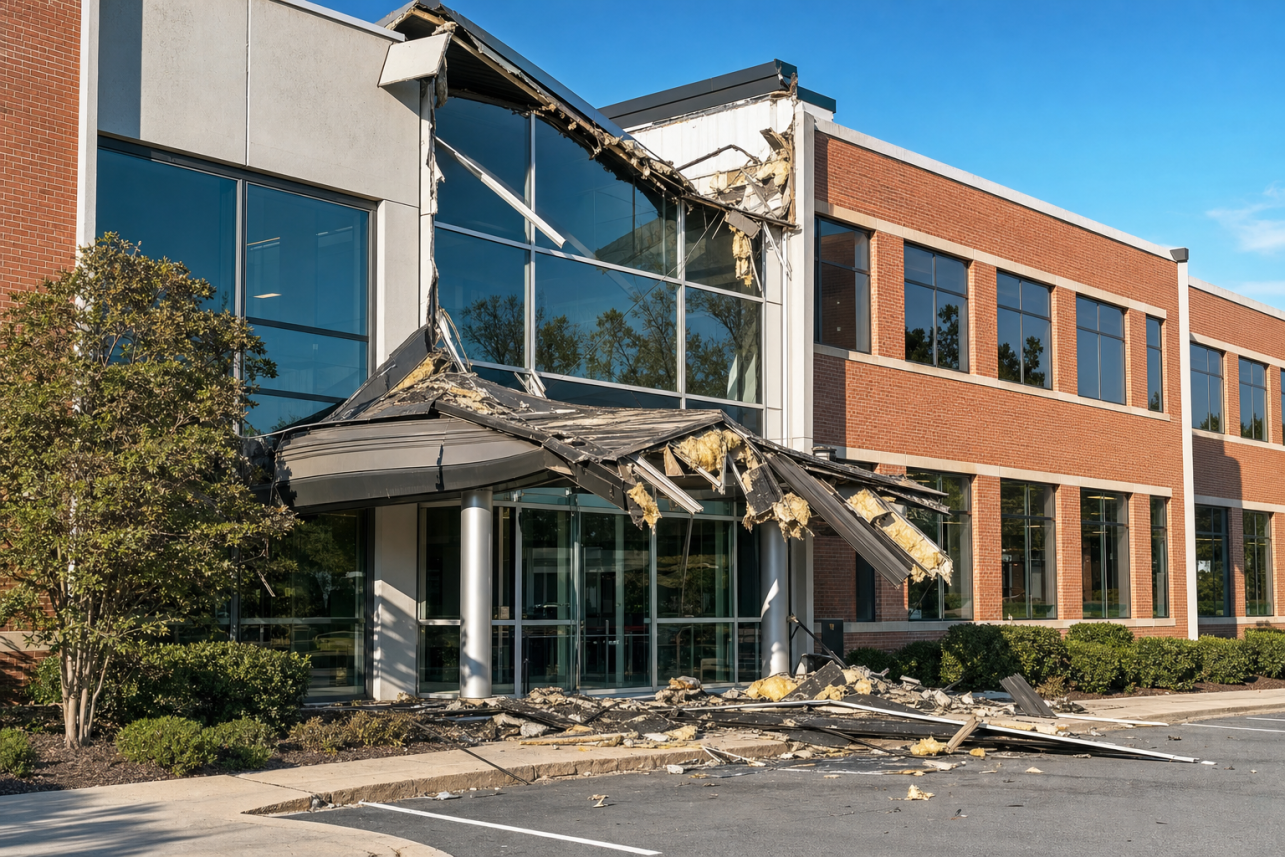
If you need help with a Commercial Business Claim Morrisville NC business owners can call For The Public Adjusters, Inc. — a licensed and bonded public adjusting firm that represents you, not the insurance company. We document the full scope of your property damage, calculate your lost business income, and negotiate directly with the carrier on your behalf. You stay focused on running your business while we handle the claim from first inspection to final settlement.
What This Service Is
A commercial claim is rarely just about a damaged building. When fire, water, or smoke shuts down a Morrisville business, you are dealing with ruined inventory, damaged equipment, payroll you still owe, and revenue that stops the moment your doors close. Your commercial property insurance policy likely covers much of that — but only if every category of loss is identified, documented, and claimed correctly.
That is what we do. As your public adjuster, we read the policy line by line, measure the real scope of damage, build the proof of loss, and put a defensible number on everything from equipment damage valuation to business interruption. We also make sure often-overlooked coverages — like extra expense coverage that pays for a temporary location or rush equipment rental — actually get used.
The insurance company's adjuster works for the carrier. Under North Carolina licensing rules overseen by the state, a public adjuster is the only claim professional who legally works for the policyholder. The NCDOI Public Adjusters Guide explains exactly that distinction, and it is why business owners hire us before accepting a first offer. We handle commercial losses across Wake County, including a steady volume of Commercial Business Claim Cary NC work right next door.
Common Problems
Will Insurance Actually Pay For My Lost Profits And The Weeks I'm Forced To Close?
This is the question we hear most, usually phrased as "lost profits, loss of business." The answer depends on your business interruption coverage and how well the loss is documented. Carriers rarely volunteer this money — you have to prove it.
A proper business income loss calculation uses your sales records, tax filings, payroll, and seasonal trends to show what you would have earned if the loss had never happened. Done casually, it gets picked apart. Done thoroughly, it is very hard for a carrier to dismiss.
We also watch the property side of the math. If the carrier pays actual cash value instead of replacement cost on your equipment and build-out, you absorb the depreciation out of pocket. Knowing which valuation your policy promises — and holding the carrier to it — often changes the insurance settlement amount significantly.
My Commercial Business Claim Morrisville NC Offer Came Back Low — Or Denied. Now What?
Lowball offers and claim denials are not the end of the road. The first offer is frequently based on a quick walkthrough that misses hidden smoke residue, water migration inside walls, and code-required upgrades in the rebuilding cost estimate.
A denial is often built on a coverage exclusion read in the carrier's favor, or on a policy coverage dispute over what caused the damage. Those positions can be challenged with better documentation, engineering support, and a correct reading of the policy language.
North Carolina courts have backed policyholders who pushed back. In DENC, LLC v. Philadelphia Indemnity Insurance Company, a federal appeals court upheld judgment for the insured owner of a North Carolina apartment building after the carrier denied coverage for a collapsed structure — a reminder that an insurer's denial letter is an opinion, not a verdict. When a dispute reaches that level, we coordinate with insurance dispute lawyers, but most underpaid claims we handle are resolved through documentation and negotiation long before court. Business owners have reopened and improved results on claims like a Commercial Business Claim in Raleigh we handled after the carrier's first number came in far below the real cost to reopen.
Searching "Commercial Public Adjuster Near Me" — How Do I Pick The Right One?
Start with licensing. North Carolina requires public adjusters to be licensed, and reputable firms are bonded. We are both. Then ask about commercial experience specifically — a residential-only adjuster may never have built an inventory loss claim or a lost revenue file.
Ask how they document. A good firm photographs and measures everything, prepares the proof of loss filing itself, and builds the income claim from your actual books rather than rough estimates. Ask who will negotiate with the carrier and how often you will get updates.
Can you handle it yourself? Legally, yes. But you would be negotiating against trained claim professionals while trying to keep a business alive. One honest caution from us: no legitimate adjuster can guarantee a specific payout, and anyone who promises you a number before inspecting the loss should be shown the door.

Our Process
Full Inspection And Scope Of Damage Assessment
We walk the entire property — structure, inventory, equipment, and contents — and document everything with photos, measurements, and itemized inventories. Smoke damage in ceiling cavities and water trapped under flooring are exactly the items a quick carrier inspection misses, and exactly where claims get underpaid.
Policy Review And Claim Valuation
We read your commercial policy in full: coverage limits, your deductible amount, exclusions, and whether you are owed replacement cost or actual cash value. Then we build the numbers — rebuilding cost estimates, equipment and inventory valuations, lost revenue documentation, and extra expenses — into one complete, defensible claim package.
Negotiation Through Settlement
We present the claim, respond to the carrier's objections with evidence, and negotiate until the offer reflects your actual loss. If the carrier delays unreasonably or takes positions that look like bad faith, we document that too and advise you on next steps. The same approach drives results on claims like a Commercial Business Claim in Apex NC, where persistence on the paperwork changed the outcome.
| Claim Task | Handling It Yourself | With Our Licensed & Bonded Team |
|---|---|---|
| Damage documentation | Photos on a phone; hidden damage behind walls and in ductwork often missed | Moisture mapping, soot testing, and room-by-room scoping before anything is disturbed |
| Building estimate | You rely on the carrier's adjuster, who works for the insurance company | Independent line-item estimate including code upgrades and concealed damage |
| Contents and inventory | Rough lists from memory after cleanup has already started | Itemized schedules with values, invoices, and vendor replacement quotes |
| Business income claim | Frequently underclaimed or skipped entirely | Income model built from your books, tax records, and a realistic restoration timeline |
| Negotiation | Verbal back-and-forth that is easy for a carrier to delay or deny | Every disputed item documented in writing and supported by policy language |
| Your time | Weeks of calls, paperwork, and site meetings on top of running the business | We manage the claim so you can focus on your operation and your people |
Commonly Overlooked In The Public Adjusting Industry
- Business income during the full period of restoration — Carriers often calculate lost income only through their own optimistic repair timeline, not the realistic date a business can actually reopen.
- Ordinance and law coverage for code upgrades — Wake County code requirements can add significant rebuild cost, and this coverage is routinely left off carrier estimates unless someone claims it.
- Soot and odor contamination in HVAC systems — Ductwork spreads smoke residue through an entire building, but it is invisible from the floor and rarely scoped without wipe testing.
- Moisture trapped in wall cavities and under flooring — Surface readings can show 'dry' while insulation and framing behind the drywall stay saturated, setting up a mold problem months later.
- The co-insurance penalty on underinsured buildings — Many owners never learn their building was insured below the required percentage until the carrier reduces the payout at claim time.
- Recoverable depreciation left unclaimed — Policies often hold back depreciation until repairs are complete, and busy owners forget to submit the paperwork to collect it.
- Extra expense coverage for temporary operations — The cost of temporary space, equipment rental, and expedited shipping to keep clients is claimable, but owners absorb it without realizing the policy pays.
- Pre-loss documentation of inventory and build-out — Once cleanup starts, proof of what existed disappears, and the burden of proving values always falls on the policyholder.
Case Studies
Case Study #1
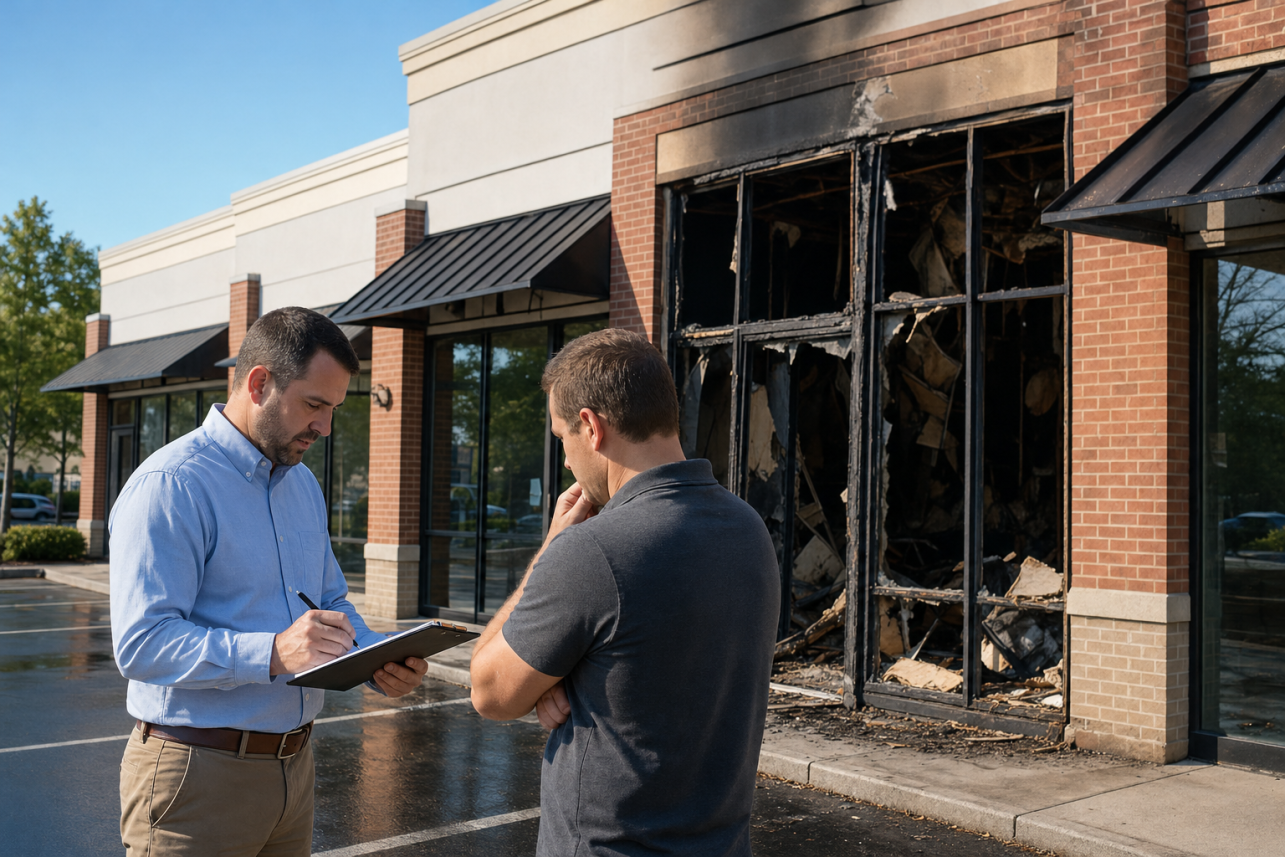
Situation: A family-owned restaurant off Chapel Hill Road in Morrisville suffered a kitchen fire that spread smoke and soot through the dining room, HVAC system, and dry storage. The owners closed immediately and called their carrier the same night.
Problem: The insurance company's first estimate covered repainting the kitchen and replacing the hood system, but treated the dining room as 'cleanable' and offered almost nothing for smoke-contaminated food inventory or lost income. The owners were being pushed to reopen before the building was actually safe to occupy.
Investigation: Our team performed a room-by-room inspection, pulled soot wipe samples from ductwork and soft goods, inventoried every contaminated food and paper product, and reconstructed the restaurant's sales history from POS records and tax filings to build a defensible business income model.
Findings: Soot had migrated through the entire HVAC system and settled on ceiling tiles, upholstery, and inventory far beyond the kitchen. The carrier's estimate omitted duct cleaning, code-required upgrades to the fire suppression system, and more than two months of lost income during a realistic restoration timeline.
Solution: We prepared a complete line-item estimate, a contents and inventory schedule with supporting invoices, and a business income claim tied to the actual period of restoration. We then negotiated directly with the carrier's adjuster and their outside consultant, documenting every disputed item in writing.
Outcome: The claim settled for several times the carrier's opening figure, including full HVAC decontamination, code upgrades under the policy's ordinance and law coverage, and business income through the true reopening date. The owners reopened without carrying the shortfall out of pocket.
Lesson: Smoke travels much farther than flames, and carriers routinely scope only what burned. North Carolina courts have long held insurers to the full scope of their policy language — in Gaston County Dyeing Machine Co. v. Northfield Insurance Co., 351 N.C. 293 (2000), the North Carolina Supreme Court sided with the insured on coverage for sudden property damage the carrier had tried to exclude. Documentation and policy knowledge, not goodwill, drive commercial settlements.
Case Study #2
Situation: A technology services firm in a flex-office building near the Morrisville side of Research Triangle Park came in on a Monday to find a failed sprinkler line had run all weekend, soaking server rooms, workstations, ceiling grids, and two floors of finished space.
Problem: The carrier accepted the water loss but applied heavy depreciation to the build-out, disputed the business personal property values on specialized equipment, and argued the firm could operate remotely, so the extra expense and income claim was 'minimal.'
Investigation: We brought in moisture mapping to document saturation behind walls and under raised flooring, catalogued damaged equipment with serial numbers and replacement quotes, and worked with the firm's controller to document contract penalties and client losses tied to the downtime.
Findings: Moisture readings showed wet insulation and framing inside wall cavities the carrier's adjuster had marked dry, creating a real mold risk. The equipment schedule was undervalued by a wide margin, and 'work from home' did not replace the secure, climate-controlled environment the firm's client contracts required.
Solution: We submitted a revised building estimate including selective demolition and drying of concealed cavities, a replacement-cost equipment claim supported by vendor quotes, and an extra expense claim for temporary secure office space that kept client contracts intact during repairs.
Outcome: The carrier reinspected, accepted the moisture documentation, and the final settlement funded proper drying, full equipment replacement at documented cost, and the temporary facility. The firm kept every major client through the restoration period.
Lesson: Water losses are won or lost on moisture documentation and valuation detail. If an adjuster never opens a wall or checks a cavity, the estimate is a guess — and the policyholder pays for that guess later in mold remediation and disputes.
| Type of Loss | What the Settlement Usually Hinges On | First Thing to Do |
|---|---|---|
| Fire and smoke | How far soot and odor actually traveled — HVAC, inventory, and soft goods, not just the burn area | Do not clean anything yet; document conditions before mitigation begins |
| Burst pipe / water damage | Moisture inside wall cavities, under flooring, and above ceilings that a quick inspection misses | Stop the water, then get moisture readings taken and recorded |
| Hurricane or tornado damage | Separating structural damage from cosmetic issues and proving the storm as the cause | Photograph everything before temporary repairs; keep all tarping and board-up receipts |
| Flood (rising water) | Flood is usually a separate NFIP policy with its own rules and deadlines — see FEMA.gov and FloodSmart.gov | Confirm whether you carry flood coverage and file the proof of loss within NFIP timeframes |
| Theft or vandalism | The quality of your inventory records and the police report matching the claimed items | File a police report immediately and preserve any security footage |
| Business income loss | An accurate 'period of restoration' and financial records that prove what you would have earned | Gather P&L statements, tax returns, and sales records before the carrier sets the timeline |
| Collapse or structural failure | Engineering evidence of the cause, since carriers often blame excluded wear and tear | Keep the area untouched and get an independent engineering opinion |
Reviews
After a fire in the unit next to ours, smoke damage ruined most of our inventory, but the insurance company kept calling it 'surface cleaning.' For The Public Adjusters inventoried every item, tested the stock, and handled the business income side we didn't even know we could claim. The final settlement let us restock completely and cover rent while we were closed. I would never handle a commercial fire claim alone again.
Renee T., retail store owner, Morrisville
A tornado-spawned storm cell tore open part of our warehouse roof and rain destroyed packaged goods below. The carrier's first offer barely covered patching the roof. This team documented the structural damage, the ruined stock, and the code upgrades the county required for the rebuild. They fought every lowballed line item in writing and the difference in the settlement was substantial. Honest, thorough, and they explained each step.
Marcus D., warehouse operations manager, Wake County
A burst supply line flooded our suite overnight — exam rooms, equipment, patient files, everything. The adjuster the carrier sent spent twenty minutes on site. For The Public Adjusters spent two full days measuring moisture, listing contents, and building the claim, then handled all the back-and-forth so I could focus on relocating patients. Our practice recovered far more than the initial estimate and reopened in a properly dried, rebuilt space.
Priya S., medical office practice administrator, Morrisville
Frequently Asked Questions
What Does A Public Adjuster Do For A Commercial Business Claim Morrisville NC Owners Can File After Property Damage?
When you hire For The Public Adjusters, Inc. to handle a Commercial Business Claim Morrisville NC businesses rely on, we work exclusively for you — never the insurance company. We document the full scope of damage to your building, equipment, inventory, and business personal property, then prepare and negotiate the claim on your behalf.
That matters because insurer-appointed adjusters answer to the carrier. Policyholders have the right to push back, and courts have backed them. In Gaston County Dyeing Machine Co. v. Northfield Insurance Co., 351 N.C. 293 (2000), the North Carolina Supreme Court ruled in favor of the insured in a dispute over coverage for property damage, confirming that carriers cannot simply read their policies in the narrowest way possible.
For Morrisville commercial properties — whether an office park off Aviation Parkway, a warehouse near RDU, or a restaurant on Chapel Hill Road — we inspect the loss, review your policy language line by line, build a detailed estimate, and handle every conversation with the carrier. We are licensed and bonded in North Carolina, and while no one can promise a specific outcome, our job is to make sure the claim reflects what your policy actually owes you.
What Types Of Commercial Property Damage Do You Handle In Morrisville?
We represent Wake County business owners on claims involving fire and smoke damage, water damage from burst pipes or roof leaks, hurricane and tornado damage, flood losses, theft and vandalism, and business interruption tied to a covered property loss.
Hurricanes are a real concern here. Even though Morrisville sits well inland, storms like Fran and Florence pushed damaging winds and rain deep into the Triangle, and tornadoes have touched down in Wake County more than once. Those storm claims often involve roof systems, HVAC units, signage, and interior water intrusion — all areas where carriers frequently undervalue the loss.
Flood claims deserve special attention because standard commercial policies usually exclude flood. If your business carries a policy through the National Flood Insurance Program, we can help you document and present that claim, and we encourage owners to review resources at FEMA.gov and FloodSmart.gov to understand their coverage before a loss ever happens.
Please note that we do not handle claims involving motor vehicles, cell phones, health, or life insurance. Our focus is strictly damage to buildings, business contents, and the income losses that flow from a covered property claim — and that focus is exactly why Morrisville business owners call us.
How Long Does A Commercial Insurance Claim Take In Morrisville, And Can You Speed It Up?
Timelines vary with the size and complexity of the loss. A straightforward water damage claim at a small Morrisville office might resolve in a few weeks, while a major fire at a warehouse or flex space near the airport corridor can take several months, especially when business interruption coverage is involved.
North Carolina requires insurers to acknowledge and respond to claims within reasonable timeframes, but delays still happen — often because documentation is incomplete or the carrier's estimate is disputed. That is where professional representation changes the pace. We prepare a complete, well-supported claim package from the start, which reduces the back-and-forth that drags claims out.
We also keep pressure on the carrier at every stage: scheduling inspections promptly, responding to document requests the same week, and challenging lowball estimates with our own detailed scope of damage. When carriers stall or deny unfairly, policyholders have legal recourse, and North Carolina courts have repeatedly held insurers accountable when they wrongly refuse to pay for damage to buildings and contents.
While we never guarantee a specific settlement amount or closing date — no honest adjuster can — getting organized representation early is the single best way to avoid the delays that hurt Wake County businesses most.
Why Should I Hire Your Team Instead Of Handling My Commercial Business Claim Morrisville NC Carrier Offers To Settle Quickly?
A fast settlement offer is not always a fair one. Carriers know that a business owner dealing with a damaged storefront or shuttered facility is under enormous pressure to reopen, and early offers often leave out code-upgrade costs, hidden water damage, depreciation disputes, and the full value of business interruption.
For The Public Adjusters, Inc. levels that playing field. We read your policy the way it is written, not the way the carrier summarizes it. We measure, photograph, and inventory everything — from structural damage down to individual contents items — and we build an independent estimate before negotiations begin. On Morrisville claims, we also understand local rebuild costs in the Triangle market, which frequently run higher than the carrier's software assumes.
The courts recognize that policyholders deserve the full benefit of their coverage. In Gaston County Dyeing Machine Co. v. Northfield Insurance Co., the North Carolina Supreme Court sided with the insured on a property damage coverage dispute, a reminder that an insurer's first interpretation is not the final word.
We are licensed and bonded, we work on your behalf from the first inspection to the final payment, and we are honest about expectations: no one can guarantee a result, but you should never accept less than your policy provides without a qualified advocate reviewing the claim first.
How Are Your Fees Structured For A Commercial Insurance Claim In Morrisville?
We work on a contingency basis, which means our fee is a percentage of the settlement your business actually receives from the insurance company. There are no upfront costs, no hourly billing, and no retainer. If the claim doesn't pay, you don't owe us a fee for our adjusting work.
The exact percentage is agreed upon in writing before we begin, and it's spelled out in a contract that complies with North Carolina Department of Insurance regulations. For The Public Adjusters, Inc. is licensed and bonded in North Carolina, so you have real accountability behind that agreement.
For most Morrisville business owners, the math is straightforward. Carriers frequently rely on their own adjusters' scope of damage, which can miss code-upgrade costs, hidden moisture behind walls, smoke contamination in HVAC systems, or the full extent of inventory and equipment losses. Our job is to document everything the policy covers and negotiate from a complete, defensible estimate.
While we never guarantee a specific outcome — no honest adjuster can — our goal is always to pursue the full value available under your policy. One point of clarification: we handle property claims for buildings, business personal property, and related losses. We do not handle claims involving motor vehicles, cell phones, health insurance, or life insurance. If your loss involves a commercial building or its contents anywhere in Wake County, we're glad to review it at no cost.
Can A Commercial Business Claim Morrisville NC Policy Include Lost Income While My Business Is Closed?
Yes, in many cases. Most commercial property policies sold to Morrisville businesses include business interruption coverage, sometimes called business income and extra expense coverage. This can pay for net income your business loses while it's shut down for covered repairs, plus continuing expenses like rent, payroll for key employees, and loan payments.
It can also cover extra expenses — the cost of temporary office space near RTP, expedited equipment replacement, or moving inventory to a temporary warehouse so you can keep serving customers during the rebuild.
Here's the catch: business interruption is one of the most disputed parts of any commercial loss. Carriers often challenge the period of restoration, the income projections, or whether certain expenses were truly necessary. A restaurant on Chapel Hill Road and a biotech tenant near Perimeter Park will have completely different income models, and the documentation has to reflect that.
We work with your financial records — profit and loss statements, tax returns, sales data, payroll — to build an income claim the carrier can't easily dismiss. We also track the repair timeline carefully, because every week the restoration period is shortened by the insurer is money out of your pocket.
If your policy includes this coverage, it should be part of your claim from day one, not an afterthought. We review your full policy before filing anything so nothing recoverable gets left behind.
What Can I Do If My Commercial Claim Was Underpaid Or Denied By The Insurance Company?
A denial or lowball payment is not the end of the road. Policyholders have the right to challenge the carrier's position, and they win — often.
A good example is Windridge of Naperville Condominium Association v. Philadelphia Indemnity Insurance Co. (7th Cir. 2019). After hail damaged the siding on the association's buildings, the insurer wanted to pay only for the individual damaged panels, even though matching replacement siding no longer existed. The court sided with the policyholder, ruling the insurer had to pay to re-side the buildings so the repair restored them to pre-loss condition. That case is a powerful reminder that an insurer's first answer is frequently not the correct one.
For a Commercial Business Claim Morrisville NC business owners believe was shortchanged, the process usually starts with a complete re-inspection. We document damage the original adjuster missed, prepare a line-item estimate using current Wake County construction pricing, and present a formal supplement or dispute to the carrier.
If the disagreement is about the amount of loss rather than coverage, most policies include an appraisal clause — a structured dispute process that resolves pricing disagreements without a lawsuit. We can guide you through that option as well.
Time limits apply to reopening and disputing claims in North Carolina, so don't sit on a denial letter. We review prior settlements and denials at no charge, and while we can't promise a particular result, we can tell you honestly whether the numbers look wrong.
My Morrisville Commercial Property Flooded — Is That Handled Differently From Other Water Damage?
Yes, and the distinction matters enormously. Standard commercial property policies cover sudden water damage from sources like burst pipes, failed water heaters, or sprinkler discharge. Rising water from outside — overflowing creeks, storm surge, or surface runoff — is flood damage, and it's excluded from almost every standard policy.
Flood coverage comes through a separate policy, usually written through the National Flood Insurance Program (NFIP) at floodsmart.gov or a private flood carrier. Morrisville sits in a watershed with Crabtree Creek and several tributaries, and parts of town near low-lying commercial corridors have flooded during heavy rain events. If you're unsure whether your property sits in a flood zone, FEMA's Flood Map Service Center at msc.fema.gov lets you look up your address directly.
If you carry flood coverage, we can help you navigate that claim. NFIP claims follow strict federal rules — a signed proof of loss is generally due within 60 days of the loss, which is far less forgiving than standard property claims. Missing that deadline can forfeit your recovery entirely.
Some losses involve both: a storm damages the roof while floodwater enters at grade. Those mixed-cause claims require careful documentation separating which damage belongs to which policy, because each carrier will try to attribute the loss to the other. That's exactly where an experienced adjuster working for you — not the insurance company — earns their fee. We're licensed and bonded in North Carolina and handle both sides of that documentation.
What Documents Do I Need To File A Commercial Business Claim Morrisville NC Insurers Will Take Seriously?
Strong documentation is the foundation of any successful commercial claim. Before anything else, locate your complete policy — not just the declarations page, but all endorsements and forms. These determine your coverage for the building, business personal property, and business interruption.
Next, gather evidence of the damage itself. Take dated photos and video of every affected area, from structural damage down to individual pieces of inventory and equipment. Do not throw anything away until the carrier has inspected it or given written permission to dispose of it.
For the financial side of the claim, pull together profit-and-loss statements, tax returns, payroll records, sales reports, and vendor invoices from at least the prior twelve months. Morrisville businesses near the airport corridor and in the Park West area often have seasonal revenue swings, and documenting those patterns matters when calculating lost income.
Finally, keep a written log of every conversation with the insurance company — dates, names, and what was said. When our team steps in, we organize all of this into a documented, itemized claim package. Courts have repeatedly sided with policyholders who could prove their losses: in Gaston County Dyeing Machine Co. v. Northfield Insurance Co., the North Carolina Supreme Court ruled in favor of the insured business in a dispute over property damage coverage, and thorough records were central to establishing the loss. We are licensed and bonded, and while no outcome can ever be promised, well-documented claims consistently put policyholders in a stronger position.
Is There A Deadline For Filing A Commercial Property Claim In Morrisville Or Wake County?
Yes, and missing it can cost you everything. In North Carolina, most commercial property policies require you to file suit within three years of the date of loss, consistent with the state's statute of limitations on contract claims. However, your policy itself may impose shorter internal deadlines — many require 'prompt' notice of loss and submission of a sworn proof of loss within a set number of days after the carrier requests it.
There is an important distinction between notifying the carrier and completing the claim. Reporting the loss quickly protects your rights, but you are not required to accept the first estimate or settle before the full scope of damage is understood. Hidden damage, such as moisture inside wall cavities or compromised roofing systems, often surfaces weeks after the initial event.
For a Commercial Business Claim Morrisville NC business owners should also watch supplemental claim windows. If you discover additional damage after an initial payment, you generally have the right to reopen or supplement the claim, but the same time limits apply.
Our advice to Wake County business owners is simple: report the loss promptly, document everything, and get a professional review of the policy's notice and proof-of-loss provisions before any deadline becomes a problem. We routinely take over claims mid-process and make sure no contractual deadline quietly passes while negotiations drag on. We cannot guarantee a particular result, but we can make certain your claim is never lost on a technicality.
Can I Dispute The Insurance Company's Estimate On My Morrisville Commercial Claim?
Absolutely. A carrier's estimate is an opinion, not a final ruling, and commercial estimates are disputed successfully all the time. The first step is a line-by-line comparison: carrier estimates frequently omit code-upgrade costs, understate commercial-grade materials, miss detach-and-reset work, or price repairs using residential labor rates that don't reflect what Morrisville contractors actually charge.
When we represent a business, we prepare our own independent estimate of the building, contents, and income loss, then negotiate from documented evidence rather than opinion. If the gap can't be closed through negotiation, most commercial policies include an appraisal clause — a formal process where each side selects an appraiser and a neutral umpire resolves the difference, often without litigation.
Policyholders who push back have real legal footing in this state. In Gaston County Dyeing Machine Co. v. Northfield Insurance Co., the North Carolina Supreme Court found in favor of the insured business when the carrier tried to narrow what counted as covered property damage. That decision remains a reminder that insurers do not get the final word on coverage.
We are licensed and bonded public adjusters, and we never promise a specific dollar outcome — no honest professional can. What we provide is a thoroughly documented counter-position and the experience to use every dispute tool your policy contains, from supplemental claims to formal appraisal.
Do You Handle Hurricane And Tornado Damage To Commercial Buildings In Morrisville?
Yes. Hurricane and tornado losses are among the most complex commercial claims we handle in Wake County. Even though Morrisville sits well inland, hurricanes tracking up from the coast — as Fran and Florence demonstrated — can drive torrential rain, roof failures, and widespread tree damage across the Triangle. Tornadoes spun off from those same systems have struck Wake County repeatedly.
These claims get complicated because a single storm often produces multiple types of damage governed by different coverage parts. A tornado may tear roofing off a flex-space building on Aviation Parkway, letting rain destroy inventory and electronics inside, while shutting the business down for weeks. That means building coverage, business personal property, and business interruption all come into play — and each must be documented separately.
Storm surge and rising water are a different matter entirely. Flood damage is excluded under most commercial property policies and is typically covered only through the National Flood Insurance Program (NFIP) or private flood coverage. If rising water affected your property, resources at FEMA.gov and FloodSmart.gov explain how NFIP commercial claims work, and we can help coordinate the flood claim alongside your property claim so nothing falls between the two policies.
After a major storm, carriers are flooded with claims and adjusters are stretched thin, which is exactly when losses get underscoped. Our team inspects thoroughly, separates covered perils correctly, and builds the claim before the carrier's first estimate locks in a low number. We're licensed and bonded, and we work only for the policyholder — never the insurance company.
Do You Handle Fire And Smoke Damage For A Commercial Business Claim Morrisville NC Owners Need To File?
Yes. Fire and smoke losses are among the most complex commercial claims we manage for Morrisville businesses, from retail spaces along Chapel Hill Road to light-industrial buildings near RDU and the Airport Boulevard corridor.
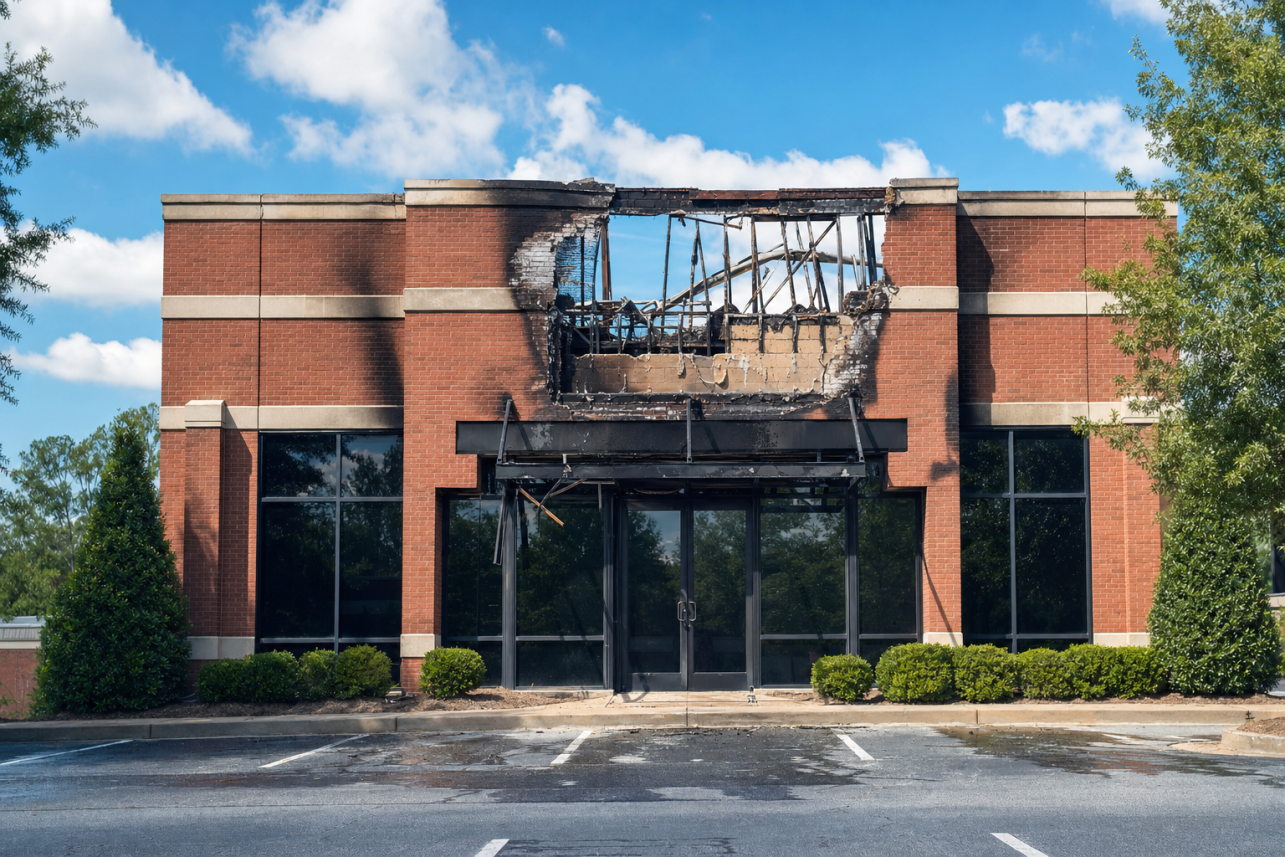
Fire claims rarely stop at the burn area. Smoke residue migrates through HVAC systems and settles on inventory, electronics, and finishes rooms away from the flames. Soot is acidic and continues corroding metal and circuitry for days after the fire is out. Carriers sometimes approve cleaning for items that genuinely need replacement, which is where an experienced Morrisville public adjuster earns their fee.
We document the full scope: structural damage, smoke and soot contamination, water damage from firefighting efforts, damaged contents, code-upgrade requirements under Wake County permitting, and business income losses while you rebuild. We prepare a detailed inventory and work with testing when odor or contamination is disputed.
Courts have repeatedly backed policyholders who push for proper scope. In Windridge of Naperville Condominium Association v. Philadelphia Indemnity Insurance Co. (7th Cir. 2019), the insurer wanted to replace only storm-damaged siding on some elevations; the court ruled the insured was entitled to replacement that produced a matching, uniform result across the building. The same matching principle often applies when fire damage affects part of a roof, facade, or interior finish.
For The Public Adjusters, Inc. is licensed and bonded, and we work on your behalf — not the carrier's. We cannot promise a specific dollar outcome, but we can promise your loss will be fully measured and professionally presented.
Can I Reopen Or File A Supplemental Claim If My Settlement Didn't Cover All My Commercial Damage?
In many cases, yes. If you accepted a payment and later discovered additional damage — or realized the carrier's estimate missed items — you can typically submit a supplemental claim, as long as you're within your policy's deadlines and North Carolina's statute of limitations, which is generally three years for breach of an insurance contract.
This comes up constantly with commercial buildings in Morrisville. A contractor opens a wall during repairs and finds hidden water damage. A roofer discovers decking rot the carrier's adjuster never saw from the ground. Or the original estimate used pricing that doesn't reflect actual Wake County construction costs in today's market.
An important caution: check whether you signed a full release when you accepted payment. Most property settlements are not final releases, but some negotiated agreements are. We review your settlement paperwork before advising you on next steps.
Our process starts with a line-by-line review of the carrier's estimate against the actual condition of your property. We identify omissions, pricing shortfalls, overlooked code-upgrade costs, and unclaimed business income or extra expense losses. Then we prepare and submit a documented supplemental demand to the insurer.
Policyholders who challenge incomplete settlements have strong footing when the facts support them. In Salesin v. State Farm Fire & Casualty Co., a Michigan appellate court sided with an insured whose water-damage loss was undervalued, confirming the carrier had to honor the policy's replacement-cost obligations. We can't guarantee a particular result, but underpaid claims in the Triangle are often worth revisiting.
What Is The Appraisal Clause, And When Should A Morrisville Business Use It?
Appraisal is a dispute-resolution process written into most commercial property policies. When you and the insurer agree a loss is covered but disagree on the amount, either side can invoke appraisal. You select an appraiser, the carrier selects one, and the two choose a neutral umpire. Agreement by any two of the three sets the loss amount — usually without going to court.
For a commercial business claim in Morrisville, appraisal makes sense when the gap between your documented damages and the carrier's estimate is significant and negotiation has stalled. It's typically faster and far less expensive than litigation, which matters when your revenue depends on reopening.
Appraisal is not the right tool for coverage denials. If the insurer says the damage isn't covered at all, that's a coverage dispute that may require an attorney. We help you tell the difference and can coordinate with counsel when needed.
Courts take appraisal awards seriously. In North Glenn Homeowners Association v. State Farm Fire & Casualty Co., the North Carolina Court of Appeals upheld an appraisal award in favor of the insured property owner over the carrier's objections, confirming that properly conducted appraisals are binding on insurers in our state.
Before recommending appraisal, our team builds the file that makes it worthwhile: a detailed estimate, photographs, moisture or engineering reports where relevant, and a clear accounting of business income losses. Going into appraisal well-documented is what gives a Wake County business owner real leverage.
I Lease My Commercial Space In Morrisville — Who Files The Claim, Me Or My Landlord?
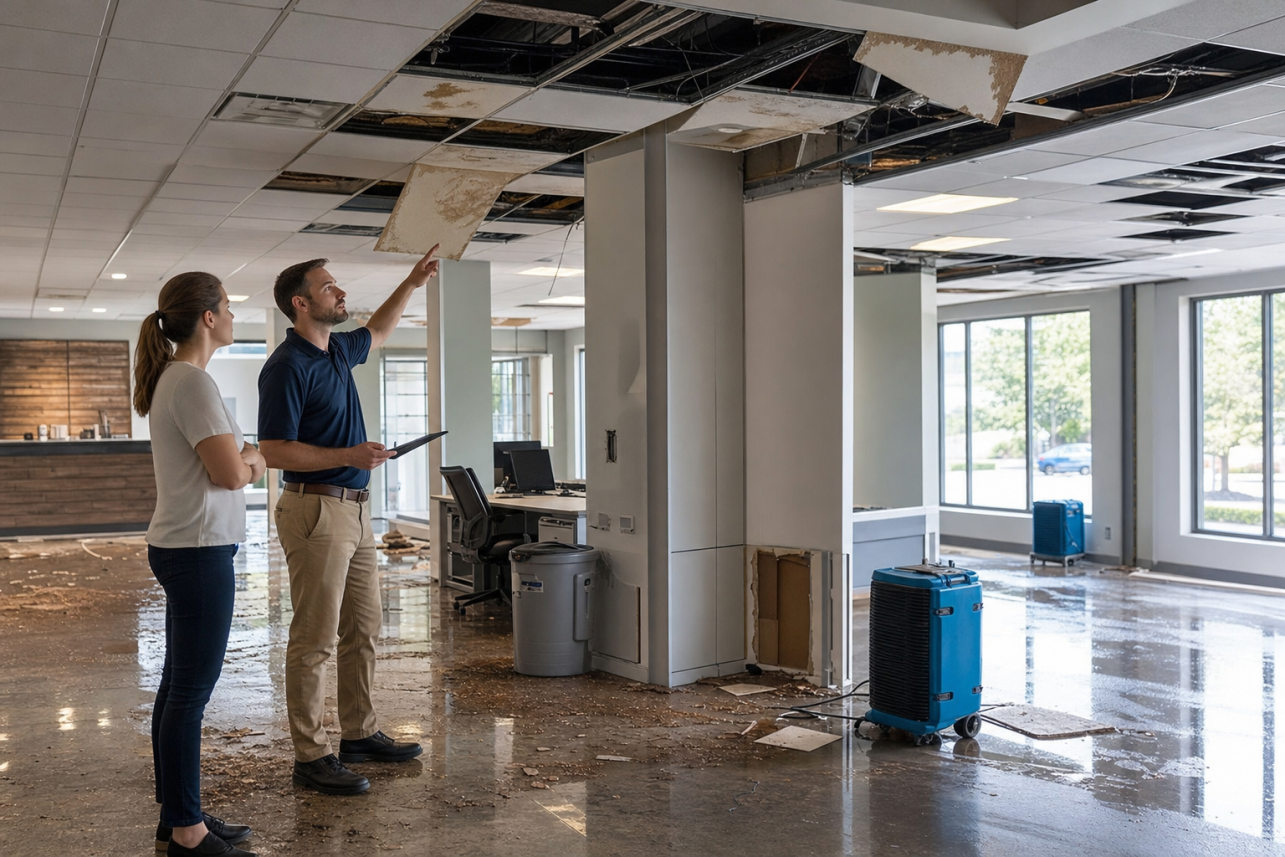
It depends on what was damaged and what your lease says. In most Morrisville commercial leases, the landlord insures the building structure, while the tenant insures their own contents, tenant improvements and betterments, inventory, equipment, and business income. That usually means two separate policies and potentially two separate claims from the same event.
Start with your lease. Look for the insurance and casualty sections, which spell out who covers what and whether you're responsible for build-outs you paid for — custom counters, specialized lighting, walk-in coolers, lab fit-outs common in the RTP-area buildings around Morrisville. Those improvements are frequently the tenant's responsibility to insure, and they're frequently missed in claims.
As the tenant, your claim for a Commercial Business Claim Morrisville NC policy typically responds to includes business personal property, improvements and betterments, business income during closure, and extra expenses like temporary relocation. Your landlord's claim covers the roof, walls, structural systems, and common areas.
We represent tenants, landlords, and sometimes both sides of the same building on their respective policies. We help coordinate so repair timelines line up — a tenant can't reopen until the landlord's structural repairs are complete, and documented delays may extend your business income recovery period.
If flooding was involved, note that standard commercial policies exclude rising water; flood coverage comes through the NFIP or private flood insurers. FEMA.gov and FloodSmart.gov explain how NFIP commercial flood policies work. We're licensed and bonded, and we'll review both the lease and the policies before any claim is filed.
Local Relevance
Morrisville's business corridors grew fast alongside Research Triangle Park — flex office space, restaurants, hotels, labs, and warehouses, much of it built during the boom years of the late 1990s and 2000s. Buildings from that era are now old enough that carriers increasingly argue "wear and tear" on roof and water losses, which makes thorough documentation essential.
The area's weather does commercial properties no favors. Humid summers drive hidden mold growth after even modest water intrusion, spring storms bring hail and the occasional tornado in narrow paths, and heavy rain over heavily paved ground sends runoff into buildings that never flooded before. Many owners discover only after a storm that standard commercial policies exclude flood — separate coverage through the National Flood Insurance Program is a different policy entirely, and knowing which policy responds to which damage matters enormously when you file.
We work these claims throughout Wake County and the Triangle, from Morrisville and Public Adjuster Cary NC engagements to kitchen and electrical fires like the Fire Damage Claim Help in Garner cases we handle on the other side of the county.
Morrisville sits in low-lying terrain near Crabtree Creek, and years of rapid development have added far more pavement and runoff than the flood maps were drawn for — so commercial buildings outside the mapped high-risk zones still take on water, and owners often learn only afterward that their standard policy excluded it. Sorting out which damage falls under the property policy versus a flood policy is frequently the deciding factor in what a Morrisville business actually recovers.
Your Business Can't Afford A Slow, Underpaid Claim
Every week your claim drags is a week of lost revenue, idle staff, and out-of-pocket repair costs. For The Public Adjusters, Inc. is licensed and bonded, and we represent one side only: yours. Call before you sign anything from the carrier — the free consultation costs you nothing, and the first offer is almost never the best one.
Call us: (919) 400-6440
Helpful Resources
- NCDOI Public Adjusters Guide
- National Flood Insurance Program (NFIP)
- North Carolina Department of Insurance — State regulator for insurance and public adjuster licensing
- FEMA flood insurance information — Federal resource on flood coverage and the NFIP
Serving Morrisville · Wake
Last updated: October 24, 2026