
If you need help with a Vandalism Homeowners Claim Morrisville NC policyholders can hire For The Public Adjusters, Inc. to document the damage, prepare the proof of loss, and negotiate directly with the insurance company on their behalf. Vandalism — break-ins, graffiti, smashed windows, kicked-in doors, destroyed interiors — is covered under most standard homeowners policies, but carriers frequently underpay or deny these claims over police report issues, vacancy questions, or disputed repair costs. We are licensed and bonded in North Carolina, and we work only for the policyholder, never the insurer.
What This Service Is
A public adjuster is a licensed claims professional who represents you, the homeowner, instead of the insurance company. When vandals damage your Morrisville home, the carrier sends its own adjuster to estimate the loss. That person works for the insurer. We level the field.
For a vandalism home insurance claim, our job starts with a complete inspection: forced-entry damage to doors and frames, broken window replacement, graffiti removal from brick or siding, slashed furniture, ruined flooring, and contents that were destroyed or stolen during the break-in. We photograph everything, build a line-item repair cost estimate, and prepare the sworn proof of loss statement your policy requires.
Then we negotiate. If the carrier's first number reflects heavy depreciation deductions or leaves out obvious damage, we push back with documentation rather than frustration. The NCDOI Public Adjusters Guide explains how our licensing works in North Carolina and confirms that public adjusters may only be paid by the policyholder — a fee that comes from the settlement, not out of pocket up front.
We handle vandalism losses across Wake County and the surrounding Triangle. Homeowners outside Morrisville can reach our Public Adjuster Apex NC team for the same representation. We also handle related losses — fire, smoke, water, and tree damage — when vandalism leads to secondary destruction, such as an intruder leaving taps running or setting small fires.
Common Problems
The Insurer's Offer Won't Cover The Actual Repairs — What Is My Claim Really Worth?
This is the most common call we get. The carrier's estimate pays for a coat of paint over graffiti when the masonry needs professional media blasting, or it prices a kicked-in door at a builder-grade slab when your entry door and frame were custom.
Much of the gap comes down to actual cash value versus replacement cost. If the adjuster applies depreciation to your contents and finishes, the check can land thousands below what repairs actually cost in today's market — leaving you with real out-of-pocket expenses after the deductible.
We rebuild the estimate line by line using local contractor pricing, identify which items your policy pays at replacement cost, and document recoverable depreciation so you can claim it after repairs are complete. We never guarantee a specific dollar outcome — no honest adjuster can — but we make sure nothing covered is left off the claim.
Why Was My Vandalism Homeowners Claim Morrisville NC Denied?
A vandalism claim denied is rarely the end of the story. Carriers commonly deny over a missing or delayed police report, an argument that the damage is 'wear and tear' rather than malicious acts, or a vacancy exclusion if the home sat empty for 30 or 60 days before the loss.
Each of those defenses can be challenged. A supplemental police report can be filed. A qualified inspection can distinguish fresh forced-entry damage from aging. Vacancy clauses have specific definitions that don't always fit your situation — a home being renovated or between tenants is not automatically 'vacant' under every policy.
North Carolina courts have long held insurers to the actual words of their policies. In Bryant v. Nationwide Mutual Fire Insurance Co., the North Carolina Supreme Court ruled that an innocent co-insured homeowner could still recover under the policy after the home was intentionally burned by the other spouse — the carrier could not stretch an exclusion to defeat coverage the policy language didn't take away. The same principle protects vandalism claimants: if the policy covers the loss, a creative denial letter doesn't change that. When a denial crosses into stonewalling or unreasonable delay, North Carolina law also recognizes bad faith claims against insurers. We've helped homeowners appeal denials here and on cases like a homeowners vandalism insurance claim in Durham.
Should I Just Handle The Claim Myself, Or Is A Public Adjuster Worth The Fee?
Small, straightforward losses — one broken window, clearly under your deductible — usually don't need professional help. But vandalism claims are rarely that clean. Break-ins often involve structural door and frame damage, contents losses that are hard to inventory, and disputes over whether damage is malicious or pre-existing.
A good public adjuster earns the fee by finding covered damage the carrier's adjuster missed, pricing repairs correctly, handling the proof of loss paperwork, and negotiating from documented evidence. Our fee is a percentage of the recovery, agreed in writing before we start, so our interests align with yours.
When you compare adjusters, check licensing with the North Carolina Department of Insurance, ask whether they're bonded (we are), and ask who will actually inspect your property. If a claim dispute escalates beyond negotiation, we can also coordinate with insurance dispute lawyers — but most vandalism claims resolve well before that point.

Our Process
Report, Secure, And Protect Your Rights
File a police report immediately — nearly every homeowners policy requires it for vandalism. Then make reasonable temporary repairs to prevent further damage: board a broken window, secure a damaged door. Keep every receipt, because those emergency costs are typically reimbursable.
Don't throw anything away and don't start permanent repairs before the damage is documented. Then call us for a free claim review.
Full Documentation And Proof Of Loss
We inspect the property, photograph all damage, inventory destroyed or stolen contents, and prepare a detailed repair estimate using current local pricing. We also review your policy for coverage you may not know you have, such as debris removal, code-upgrade allowances, or additional living expenses if the home is temporarily unlivable.
We then prepare and submit the sworn proof of loss so deadlines are met and nothing gives the carrier a technical reason to delay payment.
Negotiation Through Settlement
We meet the insurance company's adjuster on site, walk them through the evidence, and negotiate every disputed line item. If the claim stalls or the carrier delays payment without good reason, we escalate through the proper channels, including complaints to state regulators when warranted.
The same process has recovered fair settlements for policyholders on everything from a vandalism homeowners claim in Raleigh NC to large fire and water losses across the Triangle.
| Claim Task | Homeowner Handling It Alone | With For The Public Adjusters |
|---|---|---|
| Damage documentation | Phone photos of visible damage; hidden paint penetration, frame damage, and chemical staining often missed | Room-by-room inspection with testing for paint penetration, substrate damage, and contents contamination |
| Estimate and scope | Relies on the carrier's estimate, which typically prices patch-and-paint repairs | Independent line-item estimate including matching requirements for flooring, siding, and cabinetry |
| Policy review | Exclusions like vacancy clauses taken at the carrier's word | Full policy analysis, including narrow reading of exclusions supported by case law such as Battishill v. Farmers Alliance (insured won coverage after the carrier stretched a vandalism exclusion) |
| Negotiation | One homeowner against a trained company adjuster | A licensed, bonded professional negotiating on the policyholder's behalf |
| Time and stress | Weeks of calls, paperwork, and re-inspections on your own schedule | We manage inspections, correspondence, and deadlines so you can focus on your home |
Commonly Overlooked In The Public Adjusting Industry
- Paint and chemical penetration beneath graffiti — Carrier estimates price a coat of primer and paint, but spray paint and solvents often soak into drywall paper, brick, and raw wood, requiring replacement that only surface testing reveals.
- Matching requirements for continuous flooring and siding — Insurers push spot repairs, overlooking that a patch in a continuous hardwood run or a wall of siding leaves a visible mismatch the policyholder may be entitled to have corrected.
- The policy's exact vacancy definition — Carriers deny vandalism claims on vacant homes by assumption, even though many policies define vacancy narrowly — and courts like the one in Battishill v. Farmers Alliance have refused to let insurers stretch those exclusions, ruling for the insured.
- Ensuing water damage from cut or stolen plumbing — When intruders rip out copper lines, the resulting water discharge is often a separately covered peril, but it gets lumped into a denied vandalism claim if no one separates the perils.
- Structural damage hidden behind kicked-in doors and pried windows — A new door slab or glass pane gets approved while the split jamb, racked frame, and cracked trim behind them are never opened up and inspected.
- Additional living expenses when vandalism makes the home unsafe — Homeowners don't realize that if broken entry points, contamination, or utility damage make the home unlivable, temporary housing and meal costs are often claimable.
- Police report timing and proof-of-loss deadlines — Most policies require prompt reporting of vandalism to law enforcement and a sworn proof of loss within a set window, and missing either gives the carrier an easy procedural denial.
- Code and ordinance upgrades on replacement glass and doors — Replacing shattered windows and doors in Wake County can trigger current code requirements like tempered safety glass, costs that disappear from estimates unless someone claims the ordinance-or-law coverage.
Case Studies
Case Study #1
Situation: A family in the Kitts Creek neighborhood of Morrisville returned from a week-long trip to find their home had been broken into. The intruders spray-painted interior walls, smashed two bay windows, kicked in interior doors, and poured bleach across the hardwood floors in the living room and hallway.
Problem: The homeowner's insurance carrier sent a field adjuster who spent less than an hour on site. The carrier's estimate covered repainting only the tagged walls, replacing the glass panes but not the damaged frames, and refinishing a single room of flooring. The offer came to a fraction of the real repair cost.
Investigation: Our team spent two full days documenting the loss. We used moisture and surface testing to show the spray paint had penetrated the drywall paper, meaning the affected walls needed replacement rather than a coat of primer. We also measured the continuous hardwood runs through the open floor plan.
Findings: The bleach had chemically burned the finish and stained the wood itself in areas the carrier never inspected under furniture. Because the hardwood ran continuously from the foyer through the dining room, spot-refinishing would have left an obvious mismatch. The bay window frames were racked and could not safely hold new glass.
Solution: We prepared a line-item estimate covering full drywall replacement in the tagged rooms, refinishing of the entire continuous hardwood run, new window units with frames, replacement interior doors and jambs, and cleaning of contents exposed to paint overspray. We then negotiated directly with the carrier's adjuster and their re-inspection team.
Outcome: The carrier revised its position after the re-inspection and issued payment based on the documented scope, which was several times the original offer. The family was able to restore the home with matching materials instead of patchwork repairs.
Lesson: Vandalism damage is almost always deeper than it looks on a walk-through. Paint penetration, chemical staining, and matching requirements for continuous flooring are exactly the items a rushed carrier inspection misses — and exactly where a Morrisville public adjuster earns their fee.
Case Study #2
Situation: A Morrisville homeowner near Town Hall Drive had listed an inherited house for sale. While it sat on the market, intruders broke in, ripped copper piping out of the walls, and tore apart the HVAC air handler for scrap metal. Water from the severed supply lines ran for days before a realtor discovered it.
Problem: The carrier denied the entire claim, arguing the home was 'vacant' and that the policy's vandalism exclusion for vacant dwellings barred coverage for everything — including the extensive water damage that followed the pipe theft.
Investigation: We pulled the policy language apart word by word. We documented that the home remained furnished, utilities were active, and the owner visited weekly — facts that undercut the vacancy argument under the policy's own definitions. We also separated the loss into its component perils: theft, vandalism, and the resulting water discharge.
Findings: The water damage was an ensuing loss from the accidental discharge of water, a separately covered peril, not simply 'vandalism.' Courts have repeatedly refused to let carriers stretch vandalism exclusions beyond their plain meaning — in Battishill v. Farmers Alliance Insurance Co., 139 N.M. 24 (2006), the New Mexico Supreme Court held that a fire set by intruders at a home vacant more than 30 days was a covered fire loss, not excluded 'vandalism,' and the insured won.
Solution: We submitted a formal rebuttal to the denial, citing the policy's vacancy definition, the separate water-discharge coverage, and the case law holding that exclusions must be read narrowly against the insurer. We demanded a re-inspection with our documentation in hand.
Outcome: The carrier withdrew the blanket denial and paid for the plumbing replacement, HVAC equipment, water-damaged drywall and flooring, and mold remediation. The sale of the home proceeded after repairs.
Lesson: A denial letter is a starting position, not a verdict. When a carrier leans on a vacancy or vandalism exclusion, the exact policy definitions — and the case law interpreting them — often tell a very different story.
| Scenario | Typically Covered Under a Homeowners Policy? | What It Depends On | Smart First Step |
|---|---|---|---|
| Graffiti on brick, siding, or fencing | Usually yes | Whether paint penetrated porous surfaces, requiring replacement instead of cleaning | Photograph everything before any cleanup and file a police report |
| Broken windows with interior damage from exposure | Usually yes, including ensuing rain or intrusion damage | How quickly the opening was secured and documented | Board up to prevent further loss; keep receipts — emergency protection is typically reimbursable |
| Copper pipe or wiring theft with resulting water damage | Often yes, as theft plus accidental water discharge | Whether the carrier tries to apply a vacancy or vandalism exclusion | Shut off water, document the source, and get the policy's vacancy definition reviewed before accepting any denial |
| Vandalism to a vacant or listed-for-sale home | Disputed — carriers often deny | The policy's exact vacancy definition and how long the home was unoccupied; courts read these exclusions narrowly | Do not accept a verbal denial; have the policy language professionally reviewed |
| Intentional damage by a departing tenant | Sometimes — landlord policies differ from owner-occupied policies | Whether the policy treats tenant damage as vandalism or excludes damage by residents | Document the unit's condition with dated photos and the lease file |
| Slashed porch screens, outdoor furniture, and landscaping damage | Often yes, with sublimits | Contents coverage limits and any per-item or landscaping caps | Inventory each damaged item with purchase info before discarding anything |
| Interior contents destroyed during a break-in | Usually yes | Whether items were vandalized (contents coverage) or stolen (theft sublimits may apply to jewelry, electronics, firearms) | Separate your inventory into damaged vs. missing items — they're adjusted differently |

Reviews
Someone broke into our house while we were at the beach and destroyed the kitchen — cabinets pried off, counters cracked, graffiti everywhere. Our insurance company offered barely enough to paint and patch. For The Public Adjusters found damage their adjuster never even looked at, including paint soaked into the subfloor under the vinyl. The final settlement actually let us rebuild the kitchen properly. I'd never handle a vandalism claim alone again.
Danielle R., Breckenridge
Vandals cut the screens on our back porch, shattered the sliding door, and slashed the furniture inside. The carrier wanted to depreciate everything to almost nothing and skip the door frame entirely. These folks documented every item, pushed back on the depreciation, and got the frame and tempered glass covered to code. Professional, licensed, and they explained every step in plain English.
Marcus T., Shiloh area
Our rental property between tenants was tagged with spray paint and the copper water lines were stolen out of the crawlspace. The insurer tried to deny it as a vacant-home exclusion. For The Public Adjusters proved the house didn't meet the policy's vacancy definition and got the plumbing, water damage, and repainting paid. It took a couple of months of back and forth, but they handled all of it.
Priya S., near Morrisville Carpenter Rd
Frequently Asked Questions
What Should I Do First After Discovering Vandalism To My Morrisville Home?
Call the police before you touch anything. A police report is one of the first documents your insurance carrier will request, and in Wake County you can file through the Morrisville Police Department or, in unincorporated areas, the Wake County Sheriff's Office. Get the report number and the responding officer's name.
Next, photograph and video everything — spray paint, broken windows, kicked-in doors, damaged fixtures, ruined contents — before any cleanup begins. Insurers scrutinize vandalism losses closely, and documentation taken in the first hours is often the strongest evidence you will ever have.
Then take reasonable steps to prevent further damage, such as boarding broken windows or securing a door. Keep every receipt, because emergency protective measures are typically reimbursable under a standard homeowners policy. Do not make permanent repairs until the loss has been fully inspected and documented.
Finally, report the loss to your carrier promptly, but be careful with recorded statements. Adjusters for the insurance company work for the insurance company. As licensed and bonded public adjusters, we work only for the policyholder — we document the full scope of damage, prepare the estimate, and negotiate directly with the carrier on your behalf. While no one can promise a specific outcome, having a professional build your claim from day one helps ensure nothing is overlooked, from structural damage down to smaller contents items that homeowners frequently forget to list.
How Does A Public Adjuster Help With A Vandalism Homeowners Claim Morrisville NC Policyholders Might Otherwise Handle Alone?
With a Vandalism Homeowners Claim Morrisville NC homeowners often underestimate, the biggest risk is an incomplete scope of damage. Vandalism rarely stops at one broken window. There may be graffiti that requires full repainting rather than spot treatment, damaged flooring from forced entry, destroyed personal property, and sometimes water damage if plumbing fixtures were tampered with.
A public adjuster inspects the entire property, inventories damaged contents room by room, and prepares a detailed repair estimate using the same estimating platforms carriers use. That puts you on equal footing when the insurance company's adjuster produces a lower figure.
We also manage the paperwork: the sworn proof of loss, the police report coordination, policy review for coverage that applies to your specific loss, and all correspondence with the carrier. Policyholders in Morrisville juggle jobs in RTP, families, and now a damaged home — handing off the claim process removes a significant burden.
North Carolina courts have made clear that carriers must handle claims fairly. In Gray v. North Carolina Insurance Underwriting Association, 352 N.C. 61 (2000), the North Carolina Supreme Court upheld a judgment, including punitive damages, for homeowners whose storm-damaged beach properties were unfairly adjusted by their insurer. That case is a reminder that policyholders have real rights when a carrier lowballs or delays. We are licensed and bonded, and while we never guarantee a particular settlement amount, our job is to pursue every dollar your policy legitimately owes you.
Does My Homeowners Policy Cover Vandalism If My Morrisville House Was Vacant Or Under Renovation?
This is where many claims get denied, so the details matter. Most standard homeowners policies cover vandalism and malicious mischief, but many exclude it if the dwelling has been vacant for a set period — often 30 or 60 consecutive days before the loss. Vacancy and occupancy are defined terms in your specific policy, and carriers apply them aggressively.
Importantly, 'vacant' usually means empty of furnishings, which is different from 'unoccupied.' A Morrisville home that is fully furnished while you travel, or a house in the middle of a renovation with contents still inside, may not meet the policy's definition of vacant at all. We review the exact policy language before accepting the carrier's interpretation.
If you own a rental near Town Hall Drive or an investment property awaiting a tenant, your landlord or dwelling policy may treat vandalism differently than an owner-occupied homeowners form. Renovation projects can also involve builder's risk coverage with its own vandalism provisions.
When a carrier denies a vandalism loss on vacancy grounds, that denial is not automatically the final word. We gather evidence of occupancy — utility records, photos, contractor schedules, neighbor statements — and challenge interpretations that do not match the policy wording or the facts. As licensed and bonded public adjusters serving Wake County, we cannot promise a denial will be reversed, but we can make sure the carrier's position is tested against the actual contract language rather than accepted at face value.
What Is A Fair Settlement For Vandalism Damage, And What If The Insurance Company's Offer Seems Low?
A fair settlement restores your home and contents to their pre-loss condition under the terms of your policy. For a Vandalism Homeowners Claim Morrisville NC property owners should expect the estimate to include everything the vandalism actually caused: structural repairs, full repainting where graffiti cannot be matched, replacement of broken glass and hardware, damaged contents at replacement cost if your policy provides it, debris removal, and any code upgrades your policy covers.
Low offers usually come from a narrow scope — pricing a patch-and-paint when the whole wall needs refinishing, or missing contents entirely. In the Triangle's current construction market, carrier estimates frequently lag behind what Morrisville contractors actually charge for labor and materials.
If the offer seems low, you are not required to accept it. A public adjuster can re-inspect, prepare an independent estimate, and negotiate the difference. Many policies also contain an appraisal clause, a formal dispute process where each side selects an appraiser and disagreements go to an umpire — often a faster path than litigation.
North Carolina law backs policyholders who push back. In Gray v. North Carolina Insurance Underwriting Association, the state's highest court affirmed that an insurer's unfair claim handling on damaged homes could support punitive damages. Most disputes never need a courtroom, and we resolve the vast majority through documentation and negotiation. We are licensed and bonded, we never promise a specific dollar figure, and our fee structure means our interests are aligned with yours: a properly documented, fully paid claim.
What Evidence Should I Gather Before Filing A Vandalism Claim For My Morrisville Home?
Strong documentation is the backbone of any successful Vandalism Homeowners Claim Morrisville NC policyholders submit, so start gathering proof immediately. First, file a report with the Morrisville Police Department or, if your property sits in an unincorporated area, the Wake County Sheriff's Office. Nearly every homeowners policy requires a police report for vandalism, and skipping it can jeopardize your entire claim.
Next, photograph and video everything before you clean up or make repairs. Capture wide shots showing the scope of the damage and close-ups of broken windows, graffiti, damaged doors, slashed screens, destroyed landscaping, and any damaged contents inside the home. Time-stamped images are especially persuasive.
Create a written inventory of every damaged item, including brand names, approximate purchase dates, and replacement costs. Pull receipts, credit card statements, or even old photos from family gatherings that show the items in your home beforehand. Keep all receipts for emergency board-up, locksmith services, or temporary security measures, since reasonable protective expenses are typically reimbursable.
Finally, do not discard damaged property until the insurer has had the chance to inspect it, unless it poses a safety hazard. If you must remove something, photograph it thoroughly and keep a sample if possible. Our team at For The Public Adjusters, Inc. helps Morrisville homeowners assemble this documentation into a complete, professionally prepared claim package that leaves far less room for the carrier to dispute the scope or value of the loss.
How Long Do I Have To File After Vandalism Damage In Morrisville, And Are There Deadlines I Could Miss?
Yes, and the deadlines come in layers, which catches many Wake County homeowners off guard. Your policy almost certainly requires "prompt" notice of the loss, which insurers interpret aggressively. Waiting weeks to report vandalism gives the carrier an opening to argue it was prejudiced by the delay, so report it within days of discovery whenever possible.
Beyond prompt notice, most North Carolina homeowners policies impose a contractual limitations period, often three years from the date of loss under the standard NC fire and extended coverage provisions, for filing suit against the insurer. Some policies also require a sworn proof of loss within a set number of days after the company demands it, commonly sixty. Missing a proof-of-loss deadline is one of the most frequent reasons otherwise valid claims get denied.
There are also practical deadlines. Mitigation duties require you to protect the property from further damage, such as boarding broken windows or securing doors, right away. If a vandalized roof opening lets rain in next week, the insurer may refuse to pay for that additional damage.
Because these clocks all run simultaneously, a Morrisville public adjuster tracks every policy deadline for you, prepares the sworn proof of loss correctly the first time, and documents your mitigation efforts. For The Public Adjusters, Inc. is licensed and bonded in North Carolina, and we build a timeline for each claim so nothing lapses while repairs and negotiations move forward.
My Insurer Denied My Claim, Suggesting The Vandalism Was Caused By Someone Connected To My Household. Can I Still Recover?
Possibly, yes. Insurers sometimes deny vandalism and intentional-damage claims by pointing to an estranged spouse, a tenant, or another person connected to the insured. But North Carolina courts have protected innocent policyholders in exactly these situations.
In Bryant v. Nationwide Mutual Fire Insurance Co., 313 N.C. 362 (1985), the North Carolina Supreme Court ruled in favor of an innocent insured whose home was intentionally burned. The Court held that one insured's wrongdoing does not automatically bar an innocent co-insured from recovering for damage to the home under the policy. That principle matters enormously in vandalism disputes, because carriers often treat any suspected involvement by a named insured or family member as grounds for a blanket denial.
If you receive a denial like this, do not simply accept it. Request the denial in writing with the specific policy language the insurer is relying on. Preserve the police report, any suspect information, and all correspondence. The burden of proving an intentional-acts exclusion applies generally rests on the insurance company, not on you.
As Morrisville public adjusters, we review the denial letter, the policy, and the investigation file to determine whether the carrier's position actually holds up under North Carolina law. Many denials soften considerably once a licensed professional challenges the factual and legal basis in writing. While no one can promise a particular outcome on any claim, a denial built on assumptions about who caused the damage is often far weaker than it first appears.
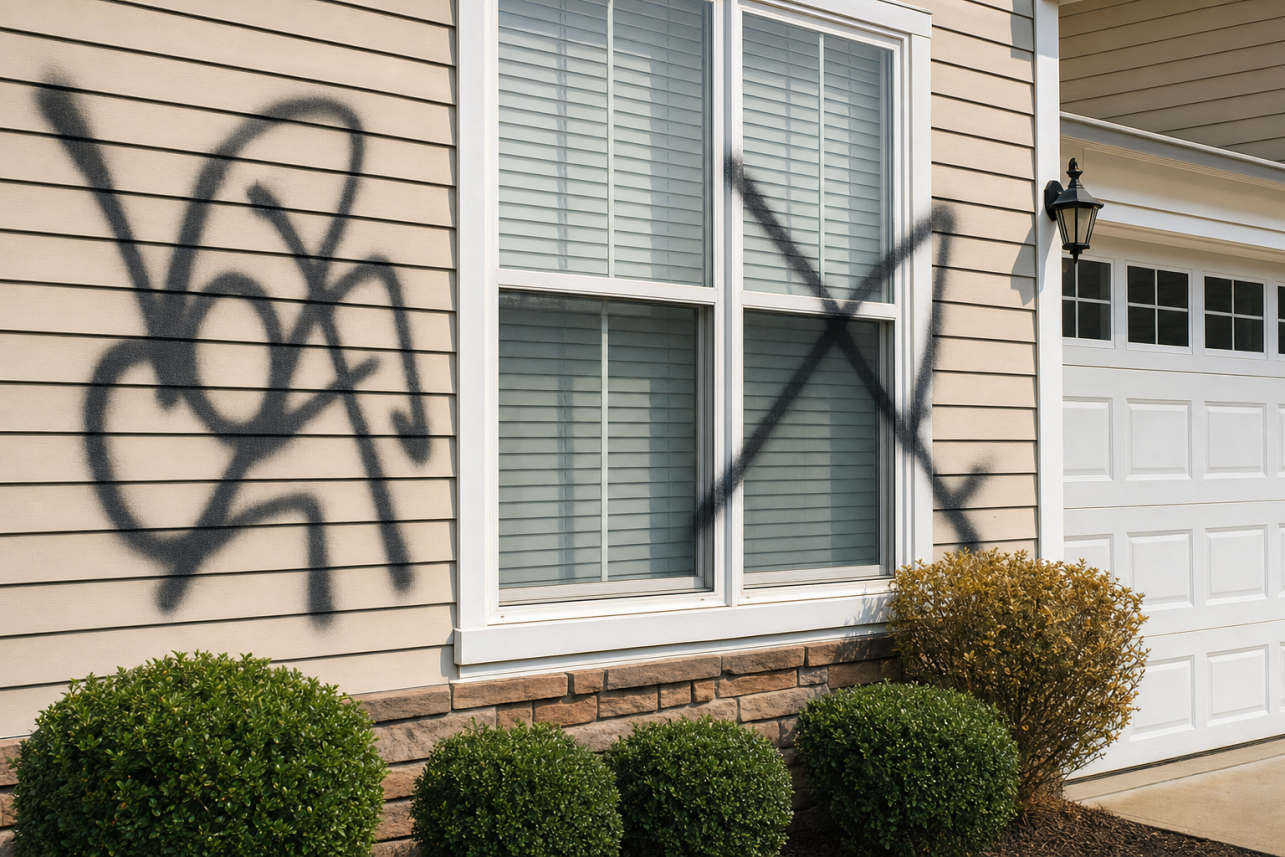
What Does It Cost To Hire For The Public Adjusters, Inc. For A Vandalism Homeowners Claim Morrisville NC Homeowners Are Filing?
We work on a contingency-fee basis, meaning our fee is a percentage of the insurance settlement we help you recover. There are no upfront costs, no hourly billing, and no fee if there is no recovery. The exact percentage is spelled out in a written agreement before any work begins, as required of licensed and bonded public adjusters in North Carolina.
For a vandalism loss, that fee covers a substantial amount of work. We inspect the damage ourselves rather than relying on the carrier's adjuster, prepare a detailed line-item repair estimate using current Wake County contractor pricing, inventory and value damaged contents, compile the police report and supporting documentation, complete the sworn proof of loss, and handle every negotiation with the insurance company on your behalf.
Homeowners in Morrisville neighborhoods like Breckenridge, Kitts Creek, and Savannah often tell us the biggest relief is not having to argue with the insurer themselves while also dealing with the violation of having their home vandalized. We attend inspections, respond to the carrier's requests, and push back when estimates come in short on scope or pricing.
One honest caveat: we never guarantee a specific dollar outcome, because every policy, loss, and carrier is different. What we can tell you is that our interests are aligned with yours. We only do well when your settlement does. If you are weighing whether professional representation makes sense for your loss, we offer a no-obligation claim review so you can decide with full information.
What Types Of Vandalism Damage Are Typically Covered Under A Morrisville Homeowners Policy?
Most homeowners policies written in North Carolina cover vandalism and malicious mischief as a named peril, and the scope is broader than many Morrisville homeowners realize. Spray-painted siding, broken windows, kicked-in doors, smashed fixtures, slashed screens, and deliberate damage to attached structures like garages and decks generally fall under the peril.
Interior damage counts too. If someone broke in and destroyed drywall, flooring, cabinetry, or built-in appliances, that destruction is part of the same claim. Personal property — furniture, electronics, clothing — damaged in the act is typically covered under the contents portion of your policy, subject to its own limits.
There are also consequential damages people miss. If a vandal shattered a window and rain later soaked your hardwood floors before you could board it up, the resulting water damage usually ties back to the vandalism event. Detached structures such as fences and storage sheds in neighborhoods off Davis Drive or Morrisville-Carpenter Road often carry separate sub-limits, so the policy language matters.
What a policy will not cover: damage to motor vehicles (that belongs to auto insurance, which we do not handle) and normal wear presented as vandalism. Our adjusters read your specific policy, identify every applicable coverage — dwelling, other structures, contents, and loss of use if the home is uninhabitable — and document the full scope. Many policyholders claim only the obvious damage and leave covered items on the table. We cannot promise a particular outcome, but a complete, well-documented scope is the foundation of a fair settlement.
My Morrisville Rental House Was Trashed By Tenants. Does That Count As Vandalism Under My Policy?
Often yes — and insurers frequently try to deny these claims by calling the destruction 'wear and tear' or an excluded intentional act. The key question is whether the damage was willful and malicious, not whether you knew the person who caused it.
Courts have sided with property owners on this exact issue. In Bowers v. Farmers Insurance Exchange, 991 P.2d 734 (Wash. Ct. App. 2000), tenants severely damaged a rental home by converting it into a marijuana grow operation. Farmers denied the claim, but the court ruled the tenants' willful destruction constituted vandalism under the policy and the landlord was entitled to coverage. That reasoning — that deliberate, malicious damage by occupants can qualify as vandalism — is persuasive for policyholders facing similar denials.
For Morrisville landlords with rental properties near RTP, the distinction matters enormously. Holes punched in walls, destroyed cabinets, ripped-out fixtures, and deliberately damaged flooring go well beyond ordinary tenant wear. Documenting the willful nature of the damage — police reports, move-in and move-out photos, witness statements — is what separates an approved claim from a denial.
As licensed and bonded public adjusters, we build that documentation, read your dwelling or landlord policy carefully, and present the claim in terms the carrier's own policy language supports. We cannot guarantee any specific result, but we can make sure the insurer evaluates the loss as the malicious act it was, not as deferred maintenance.
What Does The Process Look Like When For The Public Adjusters Handles A Vandalism Homeowners Claim Morrisville NC Residents Bring To Your Office?
The process starts with a free review of your loss and your policy. We confirm what happened, verify the police report is in place, and identify every coverage that may apply before anything is filed or supplemented with the carrier.
Next comes documentation. We inspect the property in person — whether it's a townhome near Town Hall Drive or a single-family house in Breckenridge — photographing every damaged item, measuring affected areas, and preparing a line-item estimate using the same professional estimating standards insurance companies use. Contents damage gets its own detailed inventory with values.
Then we present and negotiate. We submit the documented claim, meet the insurance company's adjuster at your property, walk them through the damage, and respond to every lowball figure or disputed line item with evidence. If the carrier's position is unreasonable, North Carolina policies include dispute tools such as appraisal, and we advise you on those options.
Throughout the claim, you make the decisions and we do the work — the calls, the paperwork, the deadlines, the follow-ups. Most policyholders handle a vandalism loss once in a lifetime; carriers handle them every day. Having a licensed, bonded professional on your side levels that imbalance.
Finally, settlement. Once funds are issued, we review the payment against the documented scope to confirm nothing was missed, including depreciation you may be able to recover after repairs. While no one can guarantee an outcome, a Vandalism Homeowners Claim Morrisville NC policyholders pursue with thorough documentation is consistently in a stronger position than one filed on a single photo and a guess.
Will Filing A Vandalism Claim Raise My Premiums, And Is It Worth Filing For Smaller Damage?
It depends on the size of the loss relative to your deductible, and this is a calculation worth doing carefully before you file. In North Carolina, vandalism is typically treated as a not-at-fault loss, but claims still appear on your CLUE report and some carriers factor claim history into renewal pricing.
Here's the honest math. If a vandal broke one window and your deductible is $1,500, filing probably doesn't make sense. But Morrisville homeowners routinely underestimate vandalism damage at first glance. Graffiti that looks like a pressure-wash job may require full repainting of matching elevations. A pried door often means a new frame, not just a lock. Broken glass can mean water intrusion, flooring damage, and drywall repair. What looks like a $900 problem is frequently a $9,000 claim once properly scoped.
That is why we offer a no-obligation damage assessment before you decide. We measure the true scope first, then you choose whether filing makes financial sense. There is no pressure either way — filing a claim that nets you little while adding to your claim history helps no one.
Courts have recognized how often carriers underpay legitimate property claims. In Watson v. United Services Automobile Association, 566 N.W.2d 683 (Minn. 1997), the court ruled an innocent homeowner could recover for willful damage to her home even after the insurer denied the claim outright — a reminder that an initial denial or low estimate is not the final word. If the damage justifies a claim, we pursue every dollar your policy allows, though no one can promise a specific amount.
Do I Need A Police Report Before Filing A Vandalism Homeowners Claim Morrisville NC Insurers Will Actually Accept?
Yes, you should file a police report as soon as you discover the damage. Nearly every homeowners policy requires you to notify law enforcement when a loss involves a criminal act, and vandalism is a crime under North Carolina law. In Morrisville, that means contacting the Morrisville Police Department and requesting a case number, or the Wake County Sheriff's Office if your property sits just outside town limits.
The report serves two purposes. First, it satisfies a policy condition, so skipping it can give the carrier grounds to delay or deny. Second, it creates an independent, dated record of the damage that supports your version of events if the insurer later questions when or how the vandalism occurred.
Many homeowners worry that the claim will fail if the vandal is never identified. It will not. Coverage does not depend on an arrest or conviction. Officers in cases like spray-painted siding, slashed window screens, or a kicked-in door often never find a suspect, and claims are still paid based on the documented damage.
When our Morrisville clients come to us, we review the police report alongside the policy language before anything is submitted. If the responding officer's narrative is thin, we supplement it with dated photographs, witness statements, and repair estimates so the file stands on its own. A complete, consistent record from day one is one of the most effective ways to keep a vandalism claim from being challenged later.
Can I Make Temporary Repairs After Vandalism, Or Will That Hurt My Claim?
Not only can you make reasonable temporary repairs, your policy almost certainly requires it. Homeowners policies include a duty to protect the property from further damage. If vandals broke windows or forced a door on your Morrisville home, boarding openings, tarping exposed areas, and securing the house are expected of you, and the reasonable cost is typically reimbursable under the claim.
The key word is temporary. Stabilize the property, but do not begin permanent repairs before the insurance company has had a fair opportunity to inspect, or before you have thoroughly documented everything. Replacing drywall, repainting graffiti, or hauling away destroyed contents too early can erase the evidence that proves the scope of your loss.
Photograph and video every damaged area before you touch it, keep every receipt for plywood, locks, tarps, and emergency labor, and save invoices from any board-up service you hire. Those costs belong in the settlement, and homeowners who do not itemize them often leave that money behind.
For The Public Adjusters, Inc. helps Morrisville policyholders strike this balance. We document the damage in detail, coordinate the timing of inspections, and present mitigation expenses as a distinct, supported line item in the claim. We are licensed and bonded, and our role is to make sure the carrier sees the full loss, including the out-of-pocket costs you incurred simply doing what the policy obligated you to do.
How Does Depreciation Work On A Vandalism Claim, And Why Was My First Check Smaller Than The Repair Estimate?
Most homeowners policies in Wake County pay vandalism losses on a replacement cost basis, but they pay in two stages. The first check reflects actual cash value, which is the replacement cost minus depreciation for age and wear, and minus your deductible. The remaining amount, called recoverable depreciation, is released after you complete the repairs and submit proof, usually invoices or a contractor's certificate of completion.
This is where many Morrisville homeowners get shortchanged without realizing it. Carriers sometimes apply aggressive depreciation to items that barely depreciate, or depreciate labor in ways the policy does not clearly permit. A ten-year-old interior door destroyed in a break-in may be depreciated heavily even though the cost to hang a new one has not dropped at all.
Deadlines matter here too. Policies typically give you a limited window, often 180 days to a year from the actual cash value payment, to complete repairs and recover the withheld depreciation. Miss that window and the insurer may keep the difference.
As part of a Vandalism Homeowners Claim Morrisville NC families bring to our office, we audit the carrier's estimate line by line, challenge inflated depreciation, confirm the replacement cost figures reflect real Triangle-area contractor pricing, and track the recoverable depreciation deadlines so nothing is forfeited. While no one can promise a specific outcome, a properly documented and professionally reviewed estimate frequently looks very different from the carrier's first version.

Have Homeowners Actually Won In Court When Insurers Wrongly Denied Vandalism-Type Damage?
Yes, and the case law shows courts will hold insurers to the plain language of their policies. A useful example is Mosley v. Pacific Specialty Insurance Co., 49 Cal.App.5th 417 (2020). There, tenants secretly converted the insureds' rental house into a marijuana grow operation, rerouting wiring and causing serious damage to the dwelling. The insurer denied the claim, arguing the policyholders were responsible for the tenants' conduct. The Court of Appeal sided with the homeowners, reversing the judgment the insurer had won below and holding that an insured cannot be charged with a tenant's concealed misconduct the insured neither knew about nor controlled.
The lesson carries directly to a vandalism homeowners claim in Morrisville NC and across Wake County. Carriers sometimes deny by pointing to exclusions, alleging the insured somehow permitted the damage, or disputing whether the act qualifies as vandalism at all. Decisions like Mosley confirm that exclusions are read narrowly and ambiguities are construed in the policyholder's favor.
Most disputes never need a courtroom. When a denial or lowball offer is challenged with strong documentation, correct policy interpretation, and a properly supported damage estimate, carriers often reassess their position during the claim or appraisal process.
Our job as your public adjuster is to build that kind of file from the start: evidence, policy analysis, and valuation that can withstand scrutiny. We cannot guarantee any particular result, but we can make certain your claim is presented with the same rigor courts have required of insurers in cases like this one.
Local Relevance
Morrisville is one of the fastest-growing towns in Wake County, sitting right against Research Triangle Park. That growth brings a specific vandalism pattern: relocation-heavy neighborhoods where homes sit empty between owners or tenants, active construction nearby, and townhome communities where one break-in affects shared walls and HOA-governed exteriors.
Vacancy matters more here than people realize. If your home was unoccupied while you waited on a corporate relocation or a tenant turnover, the carrier may raise a vacancy exclusion — and the difference between 'vacant' and 'unoccupied' under your policy language can decide the entire claim.
HOA appearance rules in Morrisville's newer subdivisions can also work in your favor. When vandalized siding, doors, or windows can't be matched to discontinued materials, matching requirements can support a wider scope of replacement than the carrier first offers. The Insurance Information Institute notes that vandalism and malicious mischief are standard covered perils on typical homeowners policies, so the fight is usually about scope and value, not whether coverage exists. We handle these claims throughout western Wake, including when a neighbor asks about a vandalism homeowners claim in Cary next door.
Morrisville's relocation-driven housing market means many homes here sit unoccupied for weeks between owners, tenants, or corporate transfers — and unoccupied homes are both more likely to be vandalized and more likely to face a vacancy-clause fight when the claim is filed. Knowing exactly how your policy defines vacancy, and documenting that the home was maintained and checked, often decides these claims before negotiation even star
Ready To Get Started?
Reach out today for a free, no-obligation conversation about your situation.
Call us: (919) 400-6440
Helpful Resources
- NCDOI Public Adjusters Guide
- Federal Emergency Management Agency (FEMA)
- National Flood Insurance Program (NFIP)
- Insurance Information Institute (III)
- National Association of Insurance Commissioners (NAIC)
- Weather Underground
- The Weather Channel
- Hurricane Center
- National Fire Protection Association (NFPA)
- American Red Cross Fire Prevention
- U.S. Fire Administration – Home Cooking Fire Safety
Serving Morrisville · Wake
Last updated: October 27, 2026