

Before you hire Insurance Dispute Lawyers Morrisville homeowners often search for, it usually pays to have a licensed public adjuster review your claim first. Many underpaid or denied property claims are resolved through better documentation and negotiation — without ever going to court. For The Public Adjusters, Inc. is licensed and bonded, works only for the policyholder, and can tell you honestly whether your dispute needs an attorney or simply a stronger, properly supported claim.
What This Service Is
A public adjuster is a state-licensed claims professional who represents you — never the insurance company — on property losses like fire, smoke, water, flood, tree damage, and vandalism. We read the policy the way the carrier does, document the full scope of damage, prepare a detailed estimate, and negotiate directly with the insurer’s adjuster.
That matters because most claim disputes are not really legal disputes. They are disagreements about scope, pricing, and documentation. A denied or lowballed house insurance claim for water damage in Morrisville, for example, often turns on moisture mapping, hidden damage behind walls, and line-item estimates — not on courtroom arguments.
The NCDOI Public Adjusters Guide explains that public adjusters in North Carolina must be licensed and act solely on behalf of the insured. When a claim genuinely does require litigation — bad faith conduct, a coverage denial that will not move — we say so, and the file we have built becomes the evidence an attorney needs. Starting with an adjuster costs you nothing in leverage and often resolves the dispute faster.
Common Problems
What Will Fighting My Underpaid Claim Actually Cost Me?
Litigation attorneys on property cases typically work on contingency fees that commonly run a third or more of the recovery, and cases can take a year or longer. A public adjuster charges a smaller percentage of the claim payment and most disputes settle in weeks or months, not years.
There is also the cost of an incomplete claim. If the carrier’s estimate missed the wet insulation, the smoke residue in the HVAC system, or code-required upgrades, you pay that shortfall out of pocket. Our job is to find and document everything the policy owes before you accept a check. We never guarantee a specific outcome — no honest professional can — but we make sure nothing covered gets left off the table.
My Claim Was Denied Or Lowballed — What Usually Went Wrong?
In our experience, most disputed claims fail on documentation, not merit. The homeowner accepted the carrier adjuster’s scope, missed the proof-of-loss deadline, or could not counter a vague ‘pre-existing damage’ or ‘wear and tear’ argument with evidence.
Courts have repeatedly sided with policyholders when the facts were properly developed. In Broussard v. State Farm Fire & Casualty Co., a couple whose home was destroyed during Hurricane Katrina challenged their insurer’s refusal to pay, and the courts held the insurer failed to prove its flood exclusion applied — the homeowners recovered their policy benefits. The lesson: the burden of proving an exclusion often sits with the carrier, and pushing back with evidence works. We apply that same pressure in negotiation, the way our team did in a hard-fought fire insurance claim dispute in Raleigh.
Insurance Dispute Lawyers Morrisville Or A Public Adjuster — Who Should I Hire First?
Ask one question: is the carrier disputing how much the loss is worth, or refusing to pay at all on a coverage argument that will not budge? If it is the amount — which describes the large majority of disputes — a public adjuster is built for exactly that fight and costs considerably less.
Judge any adjuster the same way you would judge a lawyer. Verify the North Carolina license, confirm they are bonded, ask what similar losses they have handled in Wake County, and expect a written fee agreement before any work begins. A good adjuster will also tell you plainly when your case does need an attorney, and hand over a fully documented file that makes that attorney far more effective.
Our Process
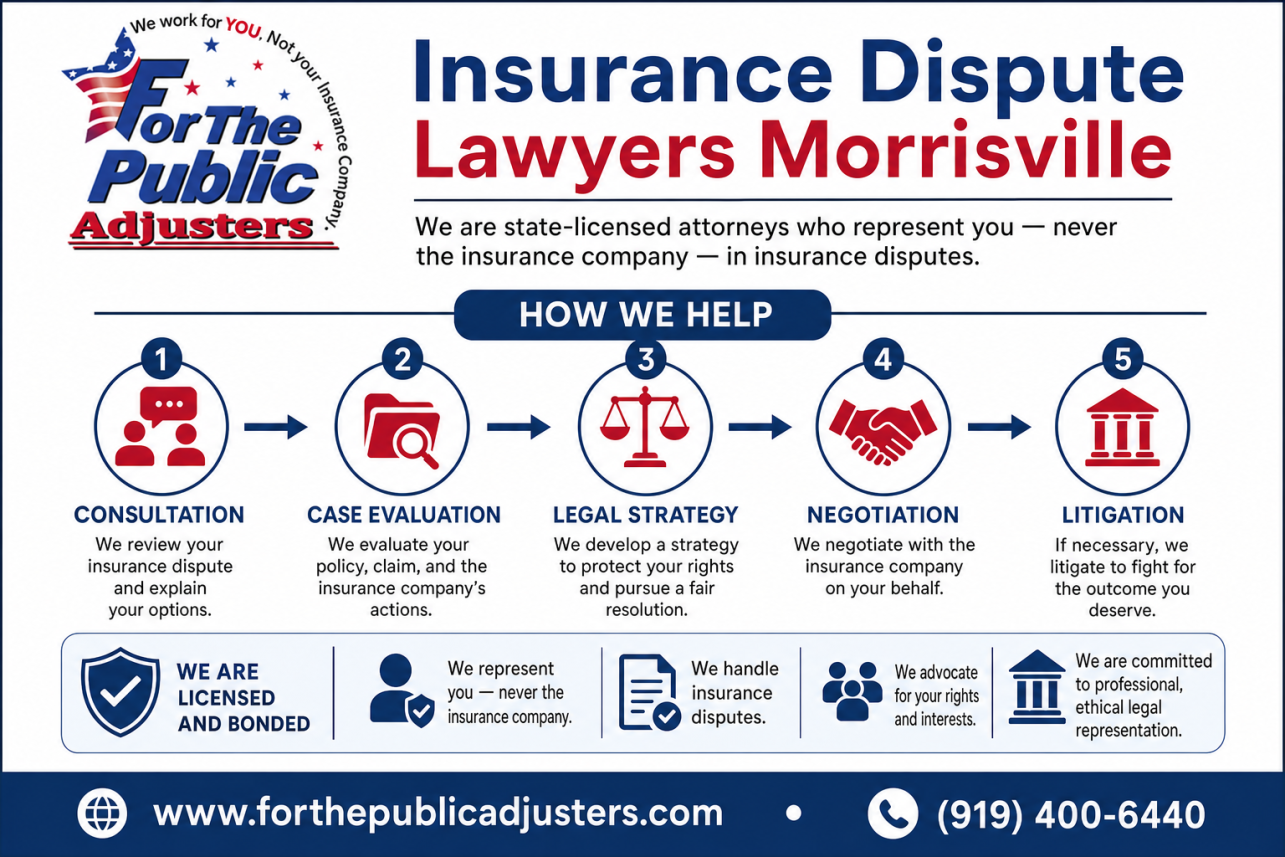
Free Policy And Claim Review
We start by reading your full policy — declarations, endorsements, and exclusions — and comparing it against what the carrier actually paid or denied. Many Morrisville homeowners are surprised to learn what coverage they were never told about, from code-upgrade provisions to additional living expenses.
Independent Documentation And Estimate
We inspect and document the entire loss: photographs, moisture readings, contents inventories, and a line-item repair estimate built the same way carriers build theirs. Water losses in particular hide damage inside wall cavities and under flooring, which is why a water damage claims adjuster in Wake Forest and across the Triangle so often finds thousands of dollars the first estimate missed.
Negotiation — And Honest Escalation If Needed
We present the documented claim to the carrier and negotiate every disputed line. If the insurer still will not pay fairly, we advise you on next steps, which can include the policy’s appraisal provision or referral to litigation counsel — armed with a file already built to win.
| Factor | Public Adjuster First | Attorney First |
|---|---|---|
| Typical fee | Percentage of the recovered amount, usually well under litigation rates | Often 33%+ contingency plus court costs and expert fees |
| Typical timeline | Weeks to a few months through negotiation and re-inspection | Many months to years if suit is filed |
| Best suited for | Underpaid claims, bad scopes, missed coverage, documentation disputes | Bad-faith conduct, final denials after full documentation, legal coverage questions |
| Who does the damage documentation | Licensed adjuster inspects, measures, and builds the estimate | Attorney typically relies on outside experts you may pay for |
| Relationship with the carrier | Negotiation stays open; carrier keeps working the claim | Claim often moves to legal counsel and negotiation slows |
| Can escalate later | Yes — the documented file strengthens any future legal case | Hard to reverse course once litigation begins |
Commonly Overlooked In The Public Adjusting Industry
- Ordinance and law coverage for Wake County code upgrades — Carrier estimates routinely price repairs to pre-loss condition and skip the code-required upgrades your policy actually pays for.
- Damage on slopes and elevations the field adjuster never inspected — Many carrier inspections cover one or two roof slopes and the visible interior, leaving documented damage elsewhere completely unclaimed.
- The appraisal clause buried in the policy — Most policyholders jump to lawsuits without knowing their policy contains a built-in dispute mechanism that’s faster and far cheaper.
- Category 3 water protocols after pipe or sewage losses — Contaminated-water losses legally require removing more material than a clean-water scope, and carrier estimates often price the cheaper version.
- Business interruption and extra expense endorsements — Owners assume income loss isn’t covered because the carrier never asks for the financial records needed to calculate it.
- Supplemental claims for hidden damage found during repairs — Policyholders accept the first check as final, not realizing claims can be reopened when contractors uncover damage behind walls or under flooring.
- Recoverable depreciation held back on replacement-cost policies — Carriers withhold depreciation until repairs are proven complete, and thousands go unclaimed because no one submits the completion documentation.
- The cost math of contingency legal fees on smaller claims — On a mid-five-figure claim, a 33% legal fee plus costs can consume more of the recovery than the underpayment itself.
Case Studies
Case Study #1
Situation: A homeowner off Morrisville Carpenter Road came to us after a July hailstorm damaged their roof, gutters, and two skylights. Their carrier had approved a partial repair worth about $6,400, and the homeowner was already searching for insurance dispute lawyers in Morrisville, convinced litigation was the only way forward.
Problem: The carrier’s field adjuster had documented only the north slope of the roof and classified the skylight damage as pre-existing wear. The estimate ignored code-required decking replacement under Wake County building requirements, and the homeowner had signed nothing yet but was days from hiring an attorney on a contingency fee.
Investigation: Before any legal step, our licensed public adjuster performed a full re-inspection: drone imagery of all four slopes, chalk-circle hail strike counts per test square, moisture readings inside both skylight wells, and a line-by-line comparison of the carrier’s Xactimate estimate against actual local repair pricing.
Findings: We documented consistent hail strikes on three slopes, not one. The skylight seals showed fresh impact fractures, not age-related failure. The carrier’s estimate also omitted drip edge, ice and water shield at valleys, and the ordinance-and-law coverage the policy actually included for code upgrades.
Solution: We compiled a supplemental claim package with photo evidence, weather data confirming the hail event over that exact address, and a corrected scope of loss. We then handled the re-inspection with the carrier’s adjuster directly, walking them through each disputed line item on the roof itself.
Outcome: The claim settled at $31,200 — nearly five times the original approval — without a lawsuit, without attorney fees taking a third of the recovery, and in roughly seven weeks instead of the year-plus a court case would have taken.
Lesson: Most underpaid claims aren’t legal disputes; they’re documentation disputes. A public adjuster can often close that gap for a fraction of the cost, and if litigation ever does become necessary, the file we build makes an attorney’s job far stronger.
Case Study #2
Situation: A small business owner near Airport Boulevard suffered a pipe burst over a holiday weekend that flooded their office suite, destroying flooring, drywall, IT equipment, and forcing a three-week closure. The carrier denied the business interruption portion entirely and lowballed the property portion.
Problem: The denial letter cited ‘insufficient documentation of income loss,’ and the owner assumed only a lawyer could fight a denial. They were quoted a 33% contingency fee plus costs before anyone had even re-examined the claim itself.
Investigation: Our team reviewed the full commercial policy, including the business income and extra expense endorsements. We reconstructed the loss timeline hour by hour, gathered twelve months of P&L statements, and brought in a drying contractor to verify the moisture migration path the carrier’s adjuster had understated.
Findings: The policy’s business interruption coverage was clearly triggered — the carrier had simply never requested the financial records needed to calculate it. The property estimate also missed Category 3 water protocols, which require removing far more material than the carrier had scoped.
Solution: We prepared a complete business income worksheet with supporting tax and sales records, submitted a corrected property scope with photographic proof of water migration, and formally requested reconsideration under the policy’s appraisal and re-evaluation provisions.
Outcome: The carrier reversed the interruption denial and paid $48,700 in combined property and income loss. The owner kept the entire recovery minus our standard fee — well below what a contingency legal fee would have cost — and reopened without ever filing suit.
Lesson: A denial letter is often the start of the negotiation, not the end. When the real issue is missing documentation or a bad scope, a Wake County public adjuster resolves it faster and cheaper than litigation ever could.
| Your Situation | Best First Call | Why |
|---|---|---|
| Carrier paid, but the check seems too low | Public adjuster | This is a scope and pricing dispute — a re-inspection and supplemental claim usually resolves it without legal action |
| Claim denied for ‘insufficient documentation’ | Public adjuster | The fix is building the documentation the carrier never received, not filing suit |
| Carrier says the damage is pre-existing or wear-and-tear | Public adjuster | Physical evidence, weather data, and expert inspection can rebut this at the negotiation stage |
| Business interruption loss was ignored or miscalculated | Public adjuster | Income loss worksheets and financial reconstruction are adjusting work, not legal work |
| Carrier is ignoring you entirely past legal deadlines | Lawyer, with an adjuster’s file behind you | Persistent non-response after documented demands can signal bad faith requiring legal pressure |
| Final written denial after a complete, well-documented claim | Lawyer | Once the factual record is exhausted, the dispute becomes a coverage or bad-faith question |
| You’ve already signed with an attorney | Ask about adding a public adjuster | Many attorneys bring in adjusters to build the damage estimate that anchors the case |
| Statute of limitations is approaching fast | Lawyer immediately | Preserving your right to sue comes first; adjusting work can run in parallel |


Reviews
After Hurricane damage to our Morrisville townhome, I had already scheduled consultations with two attorneys when a neighbor suggested calling For The Public Adjusters first. Best decision we made. They re-documented everything the insurance company’s adjuster skipped, found ordinance coverage we didn’t know we had, and turned a $9,000 offer into a $27,000 settlement in under two months. No lawsuit, no courtroom, no giving up a third of our money.
Priya Raghavan
My restaurant’s water damage claim was denied and I honestly thought suing was my only option. These folks reviewed my policy for free, showed me exactly where the carrier’s adjuster got the scope wrong, and handled the entire re-negotiation. We recovered the full business interruption loss the carrier originally said didn’t exist. They were straight with me that if it ever needed a lawyer, they’d say so — it never did.
Derek Whitfield
I was quoted a 33% contingency fee by a law firm before anyone had even re-inspected my hail-damaged roof. For The Public Adjusters found strike damage on three slopes the carrier missed and settled my claim without any legal fight. The only thing I’d change is I wish I’d called them before wasting three weeks going the lawyer route first. Genuinely knowledgeable about Wake County claims.
Melissa Chang
Frequently Asked Questions
Should I Hire Insurance Dispute Lawyers Morrisville Homeowners Recommend, Or Start With A Public Adjuster?
In most property claim disputes, a public adjuster should be your first call, not your last. Attorneys are essential when a claim reaches true legal deadlock, but the majority of underpaid or delayed claims in Wake County get resolved through documentation and negotiation, not litigation.
Here’s the practical difference. A public adjuster works the claim itself: re-measuring the damage, writing a line-item estimate on the same software carriers use, and challenging the insurer’s numbers with evidence. That’s where most disputes actually live. An attorney’s leverage, by contrast, is the threat of a lawsuit, which can take a year or more and typically costs a contingency fee of 30 to 40 percent.
Our team at For The Public Adjusters, Inc. has settled hail, wind, water, and fire claims across Morrisville, from the neighborhoods off Morrisville Carpenter Road to the townhome communities near Town Hall Drive, without a single courtroom appearance. Public adjuster fees in North Carolina are also generally lower than legal contingency fees, so more of the settlement stays with you.
That said, we’re not anti-attorney. If your carrier denies a claim in bad faith or refuses to move after a properly documented dispute, litigation may be the right path. When that happens, a file built by a licensed public adjuster, with photos, moisture readings, and a detailed estimate, becomes powerful evidence. Starting with us doesn’t close the legal door. It usually makes walking through it unnecessary.
What Can A Morrisville Public Adjuster Do That An Attorney Can’t?
A public adjuster does the hands-on claims work that attorneys typically don’t perform themselves. We climb the roof, scope the water damage, run moisture meters, photograph everything, and build a room-by-room repair estimate using Xactimate, the same pricing platform your insurance carrier uses. When we dispute a lowball offer, we’re disputing it line by line with matching methodology.
Most law firms handling insurance disputes don’t create that documentation. They either rely on what you provide or hire an outside expert, often a public adjuster, to build it anyway. Starting with us simply removes the middle step.
There’s also a timing advantage specific to how claims unfold here. Wake County sees frequent spring hail and summer wind events, and carriers often send their adjuster within days of a storm. If their scope misses damage, that early report anchors the whole claim. A public adjuster can attend the carrier’s inspection, point out missed damage in real time, and get it on record before the file hardens.
Finally, we handle the ongoing grind: supplement requests, recorded statements, proof-of-loss deadlines, and follow-up correspondence. Insurance policies in North Carolina impose strict duties on the policyholder, and missing one can genuinely hurt your claim. Having a licensed advocate managing those obligations from day one protects your position, whether the claim settles at the negotiation table or, in rare cases, eventually needs legal escalation.
How Much Does A Public Adjuster In Morrisville Cost Compared To Hiring A Lawyer?
The fee structures are very different, and the gap matters more than most policyholders realize. Attorneys handling insurance disputes usually work on contingency, commonly 30 to 40 percent of whatever they recover, plus case costs like expert witnesses, depositions, and filing fees that can run into the thousands.
Public adjuster fees in North Carolina are regulated and typically a much smaller percentage of the settlement. At For The Public Adjusters, Inc., we’re paid only from the recovery we help secure, so there’s no upfront cost and no fee if we don’t improve your outcome. On a $60,000 hail claim, that difference alone can mean tens of thousands of dollars staying in your pocket for actual repairs.
Time is the other cost. Litigation in Wake County can stretch twelve to twenty-four months before resolution, and during that time your roof still leaks and your contractor is still waiting. A negotiated settlement through a public adjuster commonly closes in weeks to a few months, depending on the carrier and complexity.
None of this means lawyers are overpriced; when a case genuinely requires litigation, that fee buys real legal firepower. The point is sequencing. Resolve what can be resolved through expert documentation and negotiation first. If your claim is among the small minority that truly needs a courtroom, you’ll enter it with a stronger file and a clearer picture of what the case is worth.
My Claim Was Denied. Is It Too Late For A Public Adjuster, Or Do I Need Insurance Dispute Lawyers Morrisville Has To Offer?
A denial is not the end of the road, and it doesn’t automatically mean you need Insurance Dispute Lawyers Morrisville has available. Many denials we see in Morrisville and greater Wake County rest on shaky ground: an adjuster who attributed hail damage to “wear and tear,” a water claim mislabeled as long-term seepage, or a scope that simply missed damage entirely.
A denial can be reopened. As licensed public adjusters, we re-inspect the property, pull weather data confirming the storm date, document the damage properly, and submit a formal dispute with a full estimate. Carriers reverse or revise denials more often than policyholders expect when confronted with evidence their own inspection didn’t gather.
Before assuming litigation is necessary, check three things. First, read the denial letter carefully; the stated reason tells us exactly what evidence is needed to counter it. Second, confirm your policy deadlines, because North Carolina policies often limit how long you have to contest a decision or file suit. Third, don’t sign anything releasing the carrier from further liability.
If the insurer stands firm after a well-documented dispute, or if the denial involves clear bad faith, that’s when an attorney earns their fee, and we’ll tell you so honestly. The file we build becomes the backbone of any legal case. But in our experience, a significant share of denied claims in this area settle once the evidence is done right, which is why the public adjuster route is worth exhausting first.
How Long Does The Public Adjusting Process Take Before I’d Ever Need Insurance Dispute Lawyers Morrisville Residents Turn To?
Most of the claims we handle in Morrisville resolve within 30 to 90 days of our involvement, and the vast majority never require an attorney at all. That timeline depends on the complexity of the damage, how quickly the carrier responds, and whether an appraisal or re-inspection is needed.
Here’s a typical sequence. In the first week, we document the loss, review your policy, and file or supplement the claim. Over the following weeks, we meet the insurance company’s adjuster on site, exchange estimates, and negotiate line by line. Many disputes come down to scope disagreements — the carrier missed the water damage behind the drywall, or underpriced roofing labor for the Wake County market — and those get resolved through documentation, not litigation.
Compare that to a lawsuit, which in Wake County can easily run 12 to 24 months through discovery, mediation, and trial scheduling. Insurance Dispute Lawyers Morrisville property owners hire do excellent work when bad faith is involved, but litigation is slow by design.
Starting with a public adjuster gives you the faster path first. If we hit a genuine wall — a wrongful denial the carrier won’t budge on, or clear bad-faith conduct — we’ll tell you honestly that it’s time for legal counsel, and your file will already be organized, documented, and ready to hand over. That preparation alone often shortens the legal process considerably.
What Types Of Morrisville Property Claims Benefit Most From A Public Adjuster Before Legal Action?
Water, wind, hail, and fire claims are the big four in this part of Wake County, and all of them tend to benefit from professional adjusting before anyone talks about lawyers.
Water losses are the most commonly underpaid claims we see in Morrisville. Burst supply lines, water heater failures, and slow leaks in townhomes near Town Hall Drive or the Breckenridge and Kitts Creek neighborhoods often involve hidden damage inside wall cavities and under flooring. Carriers frequently pay for what’s visible and stop there. We use moisture mapping and thermal imaging to document the full scope.
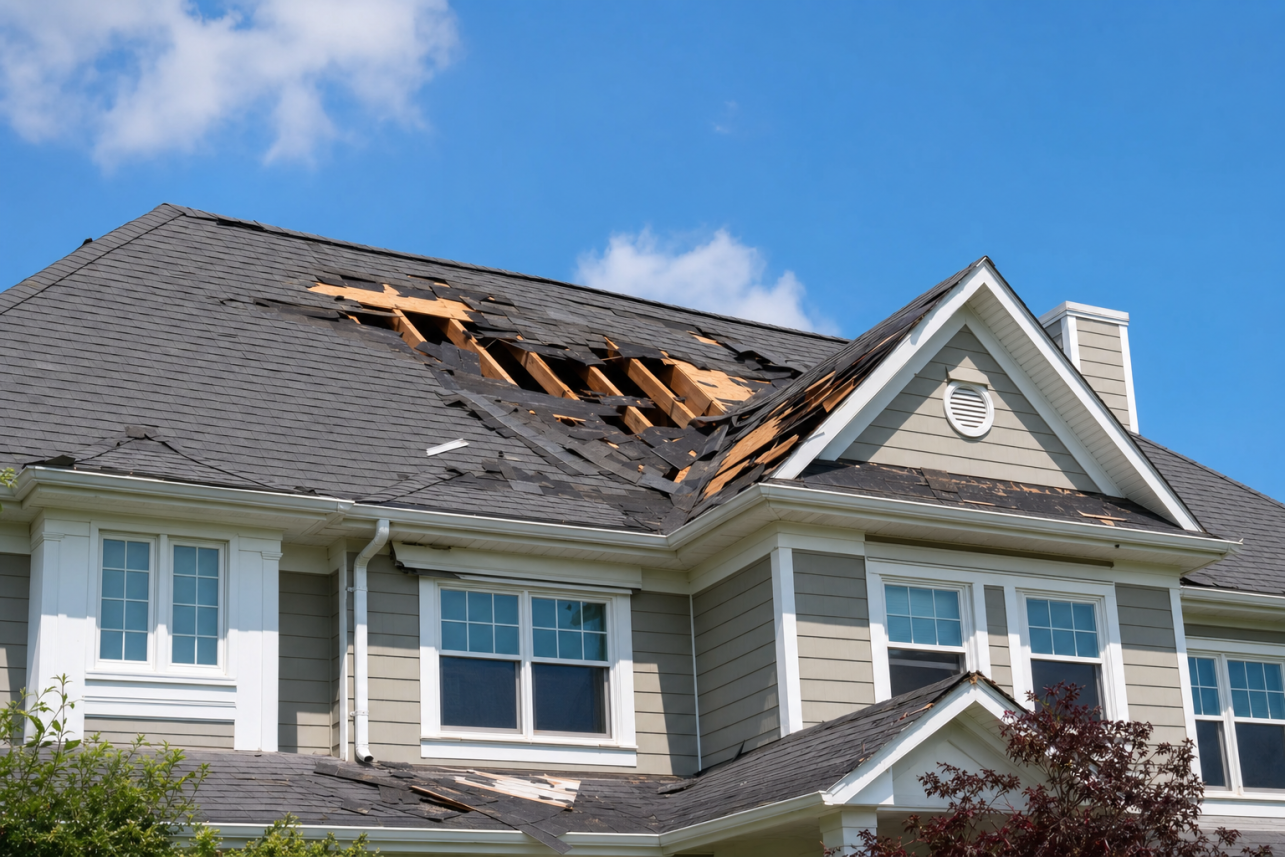
Wind and hail claims spike after the spring and summer storms that roll through the Triangle. Insurers often approve partial roof repairs when shingle discontinuation or matching issues actually justify full replacement under North Carolina’s repair standards. That’s a documentation argument, not a legal one — exactly what a public adjuster handles.
Fire and smoke claims involve contents inventories, additional living expenses, and code-upgrade coverage that homeowners routinely leave on the table simply because they didn’t know to claim them.
In each of these situations, the dispute is usually about scope and valuation, not coverage law. Those disagreements get resolved through better evidence and negotiation. Legal action makes sense when a carrier denies a clearly covered loss or acts in bad faith — and even then, the thorough file a public adjuster builds becomes the backbone of any attorney’s case.
Will Hiring A Public Adjuster In Morrisville Hurt My Case If I Need A Lawyer Later?
No — in almost every instance, it strengthens it. This is one of the most common concerns we hear from homeowners weighing their options, and the answer surprises people.
When an attorney takes on an underpaid or denied claim, the first thing they need is evidence: photographs, moisture readings, itemized estimates, correspondence with the carrier, and a clear record showing what was claimed and how the insurer responded. A public adjuster builds all of that from day one. If your claim ever escalates, your lawyer inherits an organized, professionally documented file instead of starting from scratch months after the damage occurred.
There’s also a strategic advantage. North Carolina law generally requires policyholders to comply with post-loss duties — timely notice, proof of loss, cooperation with inspections. We make sure every one of those boxes is checked, which closes off the technical defenses insurers love to raise in court.
Nothing about working with For The Public Adjusters, Inc. waives your legal rights. You keep every remedy available under your policy and under North Carolina law, including the right to demand appraisal or pursue litigation. We simply exhaust the faster, less expensive avenues first.
In practice, many attorneys in the Triangle actually refer clients to public adjusters before accepting a case, because a properly documented and valued claim either settles without a lawsuit or arrives at their desk ready to win.
How Do I Know Whether My Situation Calls For A Public Adjuster Or Insurance Dispute Lawyers Morrisville Trusts?
Ask yourself one question: is the insurance company disputing how much your loss is worth, or whether your loss is covered at all?
If the carrier accepted your claim but the check feels short — the roof estimate ignores current Wake County labor rates, the water mitigation payment doesn’t cover what the restoration company actually charged, your contents list was slashed — that’s a valuation dispute. A public adjuster is built for exactly this. We re-scope the damage, price it against real local costs, and negotiate directly with the carrier under our North Carolina license. No court dates, no legal fees, no waiting.
If the carrier denied coverage outright, accused you of misrepresentation, missed statutory deadlines, or is stonewalling in a way that suggests bad faith, that’s when Insurance Dispute Lawyers Morrisville policyholders rely on earn their fees. Those situations involve legal interpretation and potential extra-contractual damages that only an attorney can pursue.
The honest reality is that most Morrisville claims fall into the first category. Underpayment is far more common than wrongful denial, and it’s fixable without litigation.
If you’re unsure which situation you’re in, that’s what our free claim review is for. We’ll read your policy, look at the carrier’s position, and tell you plainly whether we can move the number ourselves or whether you genuinely need legal counsel. Either way, you’ll leave the conversation knowing exactly where your claim stands.
Can A Public Adjuster Negotiate Directly With My Insurance Company, Or Is That Something Only Insurance Dispute Lawyers Morrisville Can Do?
A licensed public adjuster can absolutely negotiate directly with your insurance company. In North Carolina, public adjusters are licensed by the Department of Insurance specifically to represent policyholders during the claims process, which includes documenting the loss, preparing the estimate, and negotiating the settlement on your behalf.
Where attorneys come in is when a claim moves beyond negotiation into a legal dispute, such as bad faith conduct, breach of contract, or litigation. Insurance Dispute Lawyers Morrisville policyholders hire are essential at that stage, but most Wake County claims never get that far when the loss is documented correctly from the start.
At For The Public Adjusters, Inc., we handle the entire negotiation phase: inspecting the damage, writing a line-item estimate using the same software carriers use, responding to the adjuster’s counteroffers, and pushing back on lowball figures with evidence rather than opinion. That evidence-first approach resolves the majority of underpaid claims without anyone filing suit.
If the carrier still refuses to pay what the policy owes after a thorough, well-documented negotiation, you have lost nothing by starting with us. In fact, the file we build often becomes the backbone of a legal case, and attorneys frequently tell clients that a professionally documented claim is far easier to litigate. Starting with a public adjuster keeps your options open and your costs lower.
What Happens During The First Inspection When I Hire A Morrisville Public Adjuster Instead Of Going Straight To A Lawyer?
The first inspection is where the real difference shows. When you call For The Public Adjusters, Inc., we come to your Morrisville property and physically document everything the insurance company’s adjuster may have missed or minimized.
For a roof claim after one of Wake County’s spring hailstorms, that means getting on the roof, marking hail hits, photographing soft metals like vents and gutters, and checking for wind-lifted shingles. For water damage, we use moisture meters and thermal imaging to trace how far the water actually traveled behind walls and under flooring, because visible damage is rarely the whole story.
We also review your policy line by line during that visit. Many Triangle-area homeowners don’t realize they have coverage for code upgrades, matching materials, or additional living expenses until someone reads the policy with their interests in mind.
Compare that to starting with an attorney: most law firms don’t inspect property. They work from whatever documentation already exists, which is often the carrier’s own incomplete estimate. That’s a weak foundation for any negotiation or lawsuit.
By the end of our inspection, you’ll have a clear picture of what your claim is actually worth, what the carrier offered by comparison, and a realistic plan for closing that gap. Only if the insurer refuses to honor its own policy language would we discuss bringing in legal counsel, and by then your file is already built.
Do Insurance Dispute Lawyers Morrisville And Public Adjusters Ever Work Together On The Same Claim?
Yes, and it happens more often than most homeowners expect. Public adjusters and attorneys aren’t competitors; they handle different phases of a disputed claim, and the strongest cases usually involve both working in sequence.
Here’s the typical path in Wake County. A homeowner receives a low offer or a denial. A public adjuster steps in first, re-documents the loss, prepares an independent estimate, and negotiates with the carrier. Roughly speaking, most claims settle at this stage because the carrier now faces documented evidence instead of an unrepresented policyholder.
If the insurer digs in anyway, we don’t just hand you a phone book. We work alongside attorneys in the Triangle who focus on policyholder cases, and the file we’ve built transfers directly to them: photographs, moisture readings, line-item estimates, correspondence logs, and a timeline of the carrier’s conduct. That documentation can be critical if bad faith becomes part of the case.
The attorneys benefit too. Insurance Dispute Lawyers Morrisville property owners retain will tell you that a claim professionally scoped and valued by a licensed public adjuster is far easier to litigate than one built on the homeowner’s photos and memory.
So the question isn’t really adjuster versus lawyer. It’s about sequence. Start with the documentation and negotiation phase, and escalate to litigation only if the carrier forces it. That order protects your recovery and keeps your total costs as low as possible.
My Insurance Company Sent Its Own Adjuster To My Morrisville Home. Why Isn’t That Enough?
The adjuster your insurance company sends works for the insurance company. That’s not an accusation of bad faith; it’s simply their job. Their estimate reflects the carrier’s interests, their inspection is often brief, and they have no obligation to point out coverage you didn’t ask about.
We see the consequences of that all over Morrisville and the surrounding Wake County area. A staff adjuster spends twenty minutes on a hail-damaged roof and approves a repair when the shingle manufacturer’s specs call for replacement. A water loss gets scoped for visible drywall damage while saturated insulation and subflooring go unmentioned. Depreciation gets applied aggressively, and supplements never get filed because the homeowner doesn’t know they exist.
A public adjuster works exclusively for you, the policyholder. At For The Public Adjusters, Inc., we perform our own independent inspection, write our own estimate, and compare it against the carrier’s numbers line by line. The gap between the two is frequently substantial, sometimes tens of thousands of dollars on a significant loss.
Accepting the carrier’s first figure without an independent review means trusting the other side of a financial transaction to set the price. Most people wouldn’t do that when selling a house or a car, and an insurance claim is no different.
Getting a second opinion costs you nothing upfront, since we work on contingency. If our review confirms the carrier’s offer is fair, you’ll know that too, and that peace of mind has real value.
My Insurer Made A Lowball Offer On My Claim. Should I Accept It, Or Contact Insurance Dispute Lawyers Morrisville Right Away?
Don’t accept it, and don’t rush to litigation either. A low first offer is one of the most common — and most fixable — problems we see in Wake County claims, and it’s exactly the situation a public adjuster is built to handle.
Before you call Insurance Dispute Lawyers Morrisville property owners might eventually need, let For The Public Adjusters, Inc. re-scope the loss. Most lowball offers aren’t the result of bad faith; they come from an incomplete estimate. The carrier’s adjuster may have missed hidden water damage behind drywall, undervalued code-upgrade costs, or applied pricing that doesn’t reflect what local contractors actually charge in the Triangle.
We prepare our own line-item estimate using the same software carriers use, document everything with photos and moisture readings, and submit a formal rebuttal. In many cases, the gap between the initial offer and the corrected settlement is substantial — often several times our fee.
If the carrier still refuses to pay a fair amount after we’ve documented the loss thoroughly, you’ll be in a far stronger position for legal action. You’ll have a professional estimate, a complete claim file, and a clear paper trail showing the insurer had every opportunity to do the right thing. That evidence makes an attorney’s job easier and your case more valuable. Starting with the adjusting process first costs you nothing in leverage and often resolves the dispute entirely.
What Is The Appraisal Clause In My Policy, And Can A Morrisville Public Adjuster Use It Instead Of Going To Court?
Most homeowner and commercial policies written in North Carolina include an appraisal provision — a built-in dispute resolution tool that lets you challenge the amount of your settlement without filing a lawsuit. It’s one of the strongest reasons to work with a public adjuster before hiring an attorney.
Here’s how it works. If you and your insurer disagree on the value of the loss, either side can invoke appraisal. You select an appraiser, the carrier selects one, and the two choose a neutral umpire. The appraisers evaluate the damage independently, and any two of the three can set a binding award.
For The Public Adjusters, Inc. handles appraisal disputes regularly for Morrisville and greater Wake County properties. We know how to document a loss so it holds up in that process — detailed scopes, local contractor pricing, and photographic evidence that a neutral umpire finds credible.
Appraisal typically resolves in weeks or a few months, compared to a year or more for litigation, and it costs a fraction of legal fees. It also keeps the dispute focused on what the damage is actually worth rather than on legal maneuvering.
Appraisal only settles valuation disputes, not coverage denials. If your insurer is arguing that your policy doesn’t cover the loss at all, that’s when an attorney becomes the right call. But if the fight is about dollars, appraisal handled by an experienced adjuster is usually the faster, cheaper path.
What Should I Gather Before My First Meeting About A Disputed Insurance Claim In Morrisville?
The more you can bring to that first conversation, the faster we can tell you whether your claim can be resolved through public adjusting or whether you genuinely need legal counsel. Here’s what matters most.
Start with your full policy — not just the declarations page. The endorsements and exclusions buried in the back often decide these disputes. If you can’t find it, we can request a certified copy from your carrier on your behalf.
Next, pull together all written communication: the denial or settlement letter, the carrier’s estimate, emails, and notes from phone calls with dates and names. In Wake County claims, we frequently find that what an adjuster said on the phone contradicts what the carrier put in writing, and that inconsistency matters.
Photos are critical. Gather images of the damage from the day it happened, plus anything showing the property’s condition beforehand — even casual family photos help establish pre-loss condition. If you’ve had repairs quoted, bring those contractor estimates too.
Finally, note your timeline: when the loss occurred, when you reported it, and when each response arrived. North Carolina policies impose deadlines on both sides, and slow carrier responses can strengthen your position.
At For The Public Adjusters, Inc., we review all of this at no charge during the initial consultation. Most Morrisville property owners leave that meeting knowing exactly where their claim went wrong and what it will take to fix it.
Are Public Adjusters Licensed In North Carolina, And How Is That Different From What Insurance Dispute Lawyers Morrisville Offers?
Yes. Public adjusters in North Carolina are licensed and regulated by the North Carolina Department of Insurance. That license requires passing a state examination, maintaining a surety bond, and following strict rules on contracts and fees. You can verify any adjuster’s license directly through the Department’s online lookup — and you should, before signing with anyone.
The distinction from an attorney comes down to specialty. A licensed public adjuster is a claims professional: we measure, document, estimate, and negotiate the value of property damage. Attorneys are legal professionals: they handle coverage disputes, bad-faith allegations, and litigation. Both are regulated, but by different bodies with different expertise.
For a typical Morrisville claim dispute — a hail-damaged roof the carrier underpaid, water damage that was under-scoped, a fire loss with contents the insurer won’t fully value — the licensed skill you need first is claims documentation and negotiation, not legal argument. That’s why so many disputes resolve at the adjusting stage without a lawsuit ever being filed.
For The Public Adjusters, Inc. is fully licensed for North Carolina claims, and our contracts follow the state’s required disclosures, including your right to cancel within the statutory window.
If your case does turn legal, the Insurance Dispute Lawyers Morrisville policyholders rely on will inherit a professionally built claim file rather than starting from scratch. In our experience, that combination — licensed adjusting first, legal counsel only if necessary — produces better outcomes at lower cost for Wake County property owners.
Local Relevance
Morrisville sits in the heart of western Wake County’s growth corridor, and most of its housing stock — townhomes, single-family subdivisions, and commercial space near RTP — was built during the boom of the last few decades. Newer construction is not immune to loss: supply-line failures, water heater ruptures, and washing machine hose breaks are among the most common claims we see here.
The climate adds its own risks. Humid summers bring violent thunderstorms, and the remnants of hurricanes moving inland can saturate the ground and bring mature pines and hardwoods down onto roofs — the same pattern behind cases like a tree damage insurance claim help in Carrboro matter we handled across the Triangle. Low-lying lots near local creeks can also flood, and flood losses fall under separate policies through the National Flood Insurance Program, with their own documentation rules and deadlines that trip up many policyholders.
When a Morrisville claim goes sideways, the reflex is to call a lawyer. Our advice: get the claim professionally documented first. It is often the fastest, least expensive path to a fair settlement — and if litigation truly becomes necessary, you will walk in far stronger.
So much of Morrisville is attached townhome and cluster construction that a single water loss often travels through shared walls into neighboring units, creating overlapping HOA and homeowner policies — documenting the damage path early is frequently the difference between a fair payment and a finger-pointing dispute.
Get A Second Opinion Before You Settle — Or Sue
If your Morrisville property claim was denied, delayed, or underpaid, let a licensed and bonded public adjuster review it at no cost. We will tell you honestly what your claim is worth, what the carrier missed, and whether you actually need an attorney at all.
Request Your Free Claim Review
Call us: (919) 400-6440
Helpful Resources
- NCDOI Public Adjusters Guide
- National Flood Insurance Program (NFIP)
- North Carolina Department of Insurance — State regulator that licenses public adjusters and publishes consumer claim guidance
Serving Morrisville · Wake
Last updated: August 30, 2026