Why NC Public Adjuster Reviews Matter More Than Ever
NC public adjuster reviews are the fastest way to judge a claims advocate before you hire one, and For The Public Adjusters, Inc. has just surpassed 200 five-star ratings on Customer Lobby CitySearch, Yelp, and Facebook combined. Verified reviews show how a firm actually treats policyholders during stressful fire, water, theft, and storm claims.
Key takeaways
- For The Public Adjusters, Inc. has surpassed 200 5-star client reviews across Google, CitySearch, Customer Lobby, Yelp, and Facebook combined, earning 5 out of 5 stars for service, recommendations and overall experience.
- The firm represents policyholders — not insurance companies — in fire, smoke, water, theft and storm damage claims across North Carolina, South Carolina and Virginia.
- Research by Florida’s Office of Program Policy Analysis and Government Accountability found policyholders using public adjusters received notably higher settlements, including payments 747 percent higher during the 2005 hurricane claims studied.
- For The Public Adjusters is licensed by the Department of Insurance and bonded, acting as a dedicated advocate throughout the claim valuation and negotiation process.
- Verified reviews for the firm are publicly available at customerlobby.com, giving homeowners and business owners a transparent record of past client experiences.
For The Public adjusters, Inc. of NC originally receives highest Public Adjuster Ratings for Public Adjuster Reviews from Top Rated Local, as far back as 2018, and now surpasses 200+ 5-Star reviews from satisfies customers.
A search conducted through Top Rated Local’s Score Checker shows For The Public adjusters, Inc. of NC has an overall average Review Rating of 4.9%. This average is very high considering the average is from a whopping 69 online reviews (at the time of the review conducted in Jan 2018 ).
The Score Checker produces an overall score for the business based on how many online reviews it has (in this case public adjuster reviews) and the average of those reviews.
Top Rated Local gives For The Public Adjusters, Inc.
An Overall Online Reputation Score of 94.9%

For The Public Adjusters, Inc. is a North Carolina-based public adjusting firm that acts as a policyholder advocate for insurance claimants. The firm is focused on helping homeowners and business owners obtain more proceeds from their insurer when property is damaged by fire, smoke, water, theft, or storm damage. The newly released service ratings include 5 out of 5 stars for service, client recommendations, and overall experience, with the majority of ratings on Customer Lobby and additional reviews on the firm’s Google business locations, as well as CitySearch, Yelp, and Facebook combined. You can read many For The Public Adjusters reviews at Customer Lobby and their primary Google Business Page.
What Does a Public Adjuster Actually Do?
Your insurance company has its own adjuster, but that adjuster works for the carrier, not for you. A licensed public adjuster works exclusively for the policyholder: documenting the loss, valuing the damage under the terms of your policy, and negotiating with the insurer so your rights are upheld throughout the claim process. For The Public Adjusters is licensed by the Department of Insurance and is bonded, serving clients across North Carolina, South Carolina, and Virginia. Homeowners dealing with burst pipes or appliance failures often start by searching for a water damage adjuster near Mebane and similar communities where the firm works.
Why Verified Reviews Are Your Best Shortcut
When your home has just been damaged, you don’t have weeks to vet a stranger. More than 200 five-star reviews give you something a sales pitch can’t:
- Real outcomes from real policyholders — people describing how their fire, water, theft, or storm claim was handled from start to finish.
- Consistency over time — a long track record of five-star service is far harder to fake than a handful of testimonials.
- Specifics you can relate to — one client wrote: “Despite the frustration of dealing with our water heater exploding, Joe and For the Public Adjusters made the process as pleasant and smooth as possible. The company was prompt, friendly and highly effective.”
That kind of feedback matters because the stakes are high. After a kitchen fire or structure fire, families searching for fire insurance claim help in Siler City and across the state need to know their advocate has done this successfully for others. Verified ratings on independent platforms are the clearest evidence available to a policyholder before signing anything — and the sections below explain exactly what those reviews reveal, and why representation can change the outcome of your claim.

What Do NC Public Adjuster Reviews Tell You About a Firm?
NC public adjuster reviews reveal how a firm actually treats policyholders when a claim gets stressful. For The Public Adjusters, Inc. has earned 5 out of 5 stars for service, client recommendations, and overall experience across more than 200 reviews — a consistent record that signals responsiveness, clear communication, and results clients are willing to vouch for publicly.
The majority of these ratings appear on Customer Lobby, a customer service engagement platform that keeps businesses and clients connected, with additional reviews posted across the firm’s multiple business locations and on Google. You can read the full collection on the firm’s Customer Lobby profile.
Breaking Down the Latest Ratings
- Service: 5 out of 5 stars — clients describe prompt, friendly, and effective handling of their claims.
- Client recommendations: 5 out of 5 stars — reviewers say they have referred, and will continue to refer, friends and family.
- Overall experience: 5 out of 5 stars — from first call through final settlement, clients report a smooth process even during difficult losses.
One review captures what that looks like in practice. After a sudden plumbing failure flooded their home, the client wrote: “Despite the frustration of dealing with our water heater exploding, Joe and ‘For the Public Adjusters’ made the process as pleasant and smooth as possible. The company was prompt, friendly and highly effective. I have and will continue to recommend their services to anyone that finds themselves dealing with insurance claim issues.” Sudden water losses like this are exactly the kind of claim where an experienced water damage adjuster near Mebane can take the documentation and negotiation burden off the homeowner’s shoulders.
Patterns to Look For When Reading Reviews
Star counts matter, but the details inside the reviews matter more. As you read, look for recurring themes:
- Responsiveness: Do reviewers mention quick callbacks and fast on-site visits after fire, smoke, water, theft, or storm damage?
- Communication: Do clients say the adjuster explained the policy, the process, and the next steps in plain language?
- Outcomes: Do reviewers describe settlements that allowed them to actually repair and restore their property — not vague promises?
- Repeat recommendations: Clients who say “I would use them again” are the strongest signal of trust.
One or two glowing reviews can happen to any firm. Two hundred consistent 5-star reviews across independent platforms show a pattern of advocacy that holds up claim after claim. That same licensed and bonded team serves communities across the state, including homeowners who need a public adjuster in Siler City, NC, so the standard of service reflected in these reviews is available wherever the loss occurs.
Do Policyholders With a Public Adjuster Really Get Higher Settlements?
Research says yes. A study by Florida’s Office of Program Policy Analysis and Government Accountability (OPPAGA) found that policyholders represented by public adjusters received substantially higher insurance payments than those who handled claims alone — including payments that were 747 percent higher on 2005 hurricane claims. No adjuster, however, can guarantee a specific result.
What the OPPAGA Research Found
OPPAGA is a nonpartisan government research office, which makes its findings especially credible for homeowners weighing whether professional representation is worth it. Among its key conclusions:
- Policyholders who used a public adjuster received higher settlements, on average, than those who relied solely on the insurance company’s adjuster.
- For claims arising from the 2005 hurricanes, payments on claims involving public adjusters were 747 percent higher than payments on claims without one.
- The difference often came down to thorough documentation — public adjusters identified covered damage and policy benefits that unrepresented policyholders missed.
That last point matters most. A licensed public adjuster works only for you, measuring the full scope of your loss — structure, contents, and additional living expenses — rather than accepting the carrier’s first estimate. Whether your loss involves fire, smoke, theft, or a burst pipe handled by a water damage adjuster in Mebane, the goal is the same: a settlement that reflects what your policy actually owes you.
An Honest Caveat: No One Can Guarantee Your Outcome
Be cautious of anyone who promises a specific dollar figure. Every claim turns on its own facts, policy language, and documentation. What a reputable public adjuster can promise is diligent advocacy — and strong NC public adjuster reviews from past clients are one of the best indicators that a firm delivers on that promise consistently.
North Carolina Courts Have Sided With Policyholders, Too
Higher settlements are not just a statistical trend — North Carolina case law shows that insureds who push back on wrongful denials can prevail. In Gaston County Dyeing Machine Co. v. Northfield Insurance Co., the North Carolina Supreme Court ruled in favor of the insured in a dispute with its carrier over coverage for water-related property damage, rejecting the insurer’s narrow reading of the policy. The case is a reminder that an insurance company’s initial coverage position is not the final word — policy language is often broader than the carrier’s first interpretation suggests.
You should not have to litigate to be treated fairly, though. Engaging a policyholder advocate early — for example, when you are sorting out water damage coverage insurance in Fuquay-Varina — helps ensure your claim is documented and presented correctly from the start, which is often what prevents a dispute from ever reaching a courtroom.

Why Can’t I Just Rely on the Insurance Company’s Adjuster?
The adjuster your insurance company sends works for the carrier, not for you. Their job is to evaluate the claim from the insurer’s perspective, which can mean a lower payout than your policy actually allows. A licensed public adjuster is an independent advocate who documents, values, and negotiates your loss on your behalf alone.
This is not about bad intentions on the part of any individual adjuster. It is simply about who signs their paycheck. The company adjuster answers to the insurer, follows the insurer’s guidelines, and uses the insurer’s valuation tools. You, the policyholder, are left to accept or dispute whatever figure they produce — often while you are displaced from your home, sorting through smoke-damaged belongings, or dealing with a flooded crawl space.
Two Sides of the Same Claim
Courts have long recognized that insurers owe their policyholders fair treatment. In Bi-Economy Market, Inc. v. Harleysville Insurance Co. of New York, a family food business suffered a devastating fire, and the insurer dragged out and underpaid the claim. New York’s highest court sided with the insured, holding that the policyholder could pursue consequential damages caused by the insurer’s failure to promptly and fully pay the fire loss. The case is a reminder that policyholders have real rights — but those rights rarely enforce themselves. Someone has to document the loss thoroughly and press the carrier to honor the policy.
What an Independent Policyholder Advocate Actually Does
A public adjuster works exclusively for the homeowner or business owner on fire, smoke, water, theft, and storm losses. In practice, that means:
- Documenting the full loss — structural damage, hidden damage behind walls and under floors, contents, and additional living expenses, not just what is visible on a quick walkthrough.
- Reading the policy for you — identifying every coverage, endorsement, and provision that applies to your specific loss.
- Preparing an independent valuation — a detailed estimate built for the policyholder, rather than relying solely on the carrier’s numbers.
- Negotiating directly with the insurer — handling the meetings, correspondence, and disputes so your rights are upheld from the first inspection to the final payment.
Water losses are a good example of why this matters. A burst pipe or failed water heater often causes damage far beyond what is obvious on day one, and carriers frequently scope these claims too narrowly. Understanding water damage coverage insurance in Fuquay-Varina and how your policy actually responds can change the outcome of the claim significantly.
The same holds true for fire, smoke, theft, and storm claims across the region. Working with a licensed, bonded public adjuster in Hillsborough or anywhere else in North Carolina means someone is sitting on your side of the table — reviewing, questioning, and negotiating — instead of leaving the entire process in the carrier’s hands.
What Fall Property Losses Should NC Policyholders Watch For Right Now?
North Carolina homeowners should watch for four fall hazards: early cold snaps that burst pipes or rupture aging water heaters, fires sparked by space heaters and fireplaces, leaf-clogged gutters that force water under roofing and into walls, and storm damage lingering from hurricane season. Documenting each loss immediately — before cleanup — strengthens your insurance claim considerably.
Freezing Pipes and Failing Water Heaters
The first hard freeze of the season tends to find the weak points in a home — pipes in crawl spaces, exterior walls, and unconditioned attics. Water heaters under strain from colder incoming water can also fail suddenly, releasing dozens of gallons into finished spaces. One of our own clients described exactly this scenario in a recent review, noting that after a water heater exploded, the claims process was made “as pleasant and smooth as possible.” If you are facing a sudden release of water in your home, experienced water damage insurance claim help in Chapel Hill can make the difference between a partial payment and a properly documented, fully valued claim.
Space Heater and Fireplace Fires
As temperatures drop, portable heaters and fireplaces come back into service — and so do fire and smoke losses. Smoke damage in particular is routinely undervalued because it travels far beyond the room where the fire started, settling into HVAC systems, insulation, and contents. Policyholders have successfully challenged insurers in court over property losses before. In Murray v. State Farm Fire & Casualty Co. (W. Va. 1998), homeowners whose houses were damaged prevailed when the court held that ambiguous policy language must be construed in favor of the insured — a principle that reflects why thorough documentation and a careful reading of your policy matter so much.
Leaf-Clogged Gutters and Roof Water Intrusion
- Clogged gutters push water under shingles and behind fascia boards, soaking roof decking.
- Water then migrates into attic insulation, ceilings, and interior walls — often unnoticed for weeks.
- Hidden moisture can lead to secondary damage that insurers may dispute if it isn’t documented early.
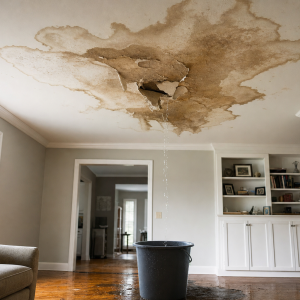
If you discover staining on ceilings or walls this fall, photograph everything before repairs begin. Homeowners seeking water damage claim help near Bynum often learn that the visible stain is only a fraction of the actual loss hiding behind drywall and under flooring.
Lingering Hurricane-Season Damage
Hurricane season doesn’t officially end until late November, and damage from earlier storms often reveals itself later — a roof opening that only leaks during the next heavy rain, for example. Report suspected storm damage promptly and keep dated photos, receipts, and notes. Many of the policyholders behind our NC public adjuster reviews first contacted us weeks after a storm, once hidden damage surfaced. Early, organized documentation is consistently what changes the outcome of these claims.
How Do I Verify a Public Adjuster Is Licensed in North Carolina?
You can verify a public adjuster’s license by searching the North Carolina Department of Insurance licensee database or calling the NCDOI directly. Confirm the license is active, ask for proof that the firm is bonded, and cross-check the adjuster’s name and firm against independent, third-party review platforms before signing anything.
Verification takes only a few minutes, and it is one of the most important steps you can take after a fire, storm, water or theft loss. The North Carolina Department of Insurance licenses public adjusters in the state, and a legitimate firm will never hesitate to provide its license number. For The Public Adjusters, Inc. is licensed and bonded, and encourages every policyholder to run this check — on them or any other firm.
A Simple Verification Checklist
- Search the NCDOI license lookup for the individual adjuster’s name and confirm the license type says “public adjuster” and the status is active.
- Ask for proof of bonding. North Carolina requires public adjusters to be bonded, which adds a layer of financial accountability for you.
- Confirm multi-state experience if your property or the firm operates in South Carolina or Virginia as well — licensing is state by state, and reputable firms hold the proper license in each state where they work.
- Read third-party reviews on platforms the firm cannot edit, such as Google and Customer Lobby. Genuine NC public adjuster reviews describe real claim situations — burst pipes, kitchen fires, storm damage — not vague praise.
- Check for complaints through the National Association of Insurance Commissioners, which offers consumer tools for researching licensing and complaint histories across states.
Questions to Ask Before Signing a Representation Agreement
- What is your fee, and is it a percentage of the settlement with everything in writing?
- Who will actually handle my claim day to day?
- Have you handled losses like mine — fire, smoke, water, theft or storm — in my area?
- Can I cancel the agreement, and under what terms?
Be cautious of anyone who promises a specific settlement amount. A licensed, bonded firm will explain the process honestly rather than guarantee an outcome. Courts have repeatedly sided with policyholders who pushed back on underpaid property claims — in Dickerson v. Lexington Insurance Co., a homeowner whose house was destroyed prevailed against the insurer when the court held the carrier owed the full insured value of the home. Proper representation and documentation matter.
Finally, confirm the firm actually serves your community. A local presence, such as a Public Adjuster in Chapel Hill NC, means the adjuster can inspect your property promptly and knows regional building costs.
The same applies across the Triangle — if you’re searching for a Public Adjuster in Garner, verify the license first, then read the reviews. Firms like For The Public Adjusters, with more than 200 5-star ratings, make that homework easy.
NC Public Adjuster Reviews: Comparing Your Claim Representation Options
| Factor | Insurance Company Adjuster | Public Adjuster (Policyholder Advocate) |
|---|---|---|
| Who they work for | The insurance carrier | You, the policyholder |
| Goal of the claim review | Settle the claim per the carrier’s assessment | Document and negotiate the full value owed under your policy |
| Settlement outcomes (per OPPAGA research) | Baseline carrier payments | Measurably higher average settlements, including 747% higher in the 2005 hurricane claims studied |
| Verified client ratings | Varies by carrier | 200+ 5-star reviews on Google and Customer Lobby for For The Public Adjusters |
Illustrative Example: A Burst Pipe Claim Handled the Right Way
Illustrative example
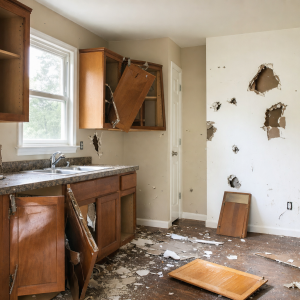
Consider a hypothetical, composite scenario: a North Carolina homeowner discovers extensive water damage after a pipe bursts behind a kitchen wall, and the carrier’s initial assessment overlooks damage to flooring, cabinetry and personal contents. A licensed public adjuster steps in, documents the full scope of the loss, and negotiates directly with the insurance company on the homeowner’s behalf. With the complete damage properly valued, the homeowner is positioned to pursue the compensation the policy actually provides for, rather than accepting the first figure offered. This composite example reflects the kind of advocacy policyholders describe in the firm’s 200-plus 5-star reviews — it is illustrative only and does not represent a specific client or guarantee any particular outcome.
Frequently asked questions
How much does a public adjuster cost in North Carolina?
Public adjusters typically work on a contingency fee, meaning they charge a percentage of the settlement your insurance company pays rather than an upfront fee. The exact percentage varies by firm and the size and complexity of the claim, so ask for the fee in writing before signing a contract. Because fees come from the settlement, many policyholders find they owe nothing unless their claim is paid.
Where can I find NC public adjuster reviews I can actually trust?
Look for reviews on independent platforms like Google and Customer Lobby, where businesses cannot edit or remove client feedback. For The Public Adjusters, Inc. has earned more than 200 5-star reviews across these platforms, with ratings covering service, client recommendations, and overall experience. When reading reviews, pay attention to mentions of communication, responsiveness, and how the firm handled specific loss types like fire or water damage.
Do people really get bigger settlements with a public adjuster?
Research by the Office of Program Policy Analysis and Government Accountability found that policyholders represented by a public adjuster received higher settlements than those who handled claims alone. During the 2005 hurricanes, that study found public adjuster claims resulted in payments that were 747 percent higher. While no adjuster can guarantee a specific outcome, having a licensed advocate who values and negotiates your claim often makes a meaningful difference.
Isn’t the adjuster my insurance company sends already working for me?
No. The adjuster your insurance carrier sends works for the insurance company, not for you. Their job is to evaluate the claim on behalf of the insurer. A public adjuster is the only type of adjuster licensed to represent the policyholder’s interests, documenting the full scope of damage and negotiating for the proceeds you are actually owed under your policy.
What happens step by step when I hire a public adjuster?
First, the adjuster reviews your policy to understand your coverage. Next, they thoroughly inspect and document the damage to your home, building, or contents. They then prepare a detailed valuation of your loss, file or supplement the claim, and negotiate directly with your insurance company on your behalf. You stay informed throughout, but the adjuster handles the paperwork, meetings, and back-and-forth so you can focus on recovery.
What are the biggest mistakes homeowners make after fire or water damage?
Common mistakes include accepting the insurer’s first offer without an independent valuation, discarding damaged contents before they are documented, giving recorded statements without understanding the policy, and missing deadlines for proof of loss. Another frequent error is assuming the carrier’s adjuster captured everything—hidden smoke, water, and structural damage is often missed. Getting a policyholder advocate involved early helps avoid these costly missteps.
Can I hire a public adjuster if my claim was already underpaid or denied?
Yes. Public adjusters can often reopen or supplement claims that were underpaid, and they can review denied claims to determine whether the denial was proper under your policy. Courts have sided with policyholders in these disputes—in Bi-Economy Market v. Harleysville Insurance, New York’s highest court held the insurer liable for additional damages after it mishandled a fire claim on the insured’s building. Timing matters, so act before policy deadlines expire.
How do I choose between public adjusters in North Carolina?
Verify the adjuster is licensed by the Department of Insurance and bonded, then check independent reviews on Google and Customer Lobby for consistent 5-star feedback. Ask about experience with your specific loss type—fire, smoke, water, theft, or storm damage—and request the fee agreement in writing. Be cautious of anyone who guarantees a specific dollar outcome; a reputable adjuster will explain the process honestly rather than make promises.
How long does an insurance claim take with a public adjuster involved?
Timelines vary with the size of the loss, how quickly damage can be documented, and how responsive the insurance carrier is. Smaller claims may resolve in weeks, while large fire or storm losses can take several months. A public adjuster often keeps claims moving by submitting complete documentation the first time, which reduces the back-and-forth requests that commonly delay payment.
What types of claims do public adjusters handle?
Public adjusters handle property claims for homeowners and business owners, including damage from fire, smoke, water (such as burst pipes), theft, and storms. They value both structural damage and damaged contents. They do not handle claims involving cell phones, motor vehicles, health insurance, or life insurance. For The Public Adjusters serves policyholders in North Carolina, South Carolina, and Virginia.
Flood Insurance Claim help near you
Related local pages
Dealing with fire, smoke, water, theft, or storm damage? Contact For The Public Adjusters for a free claim review from a licensed, bonded policyholder advocate. Get in touch.
Last updated: October 20, 2026