
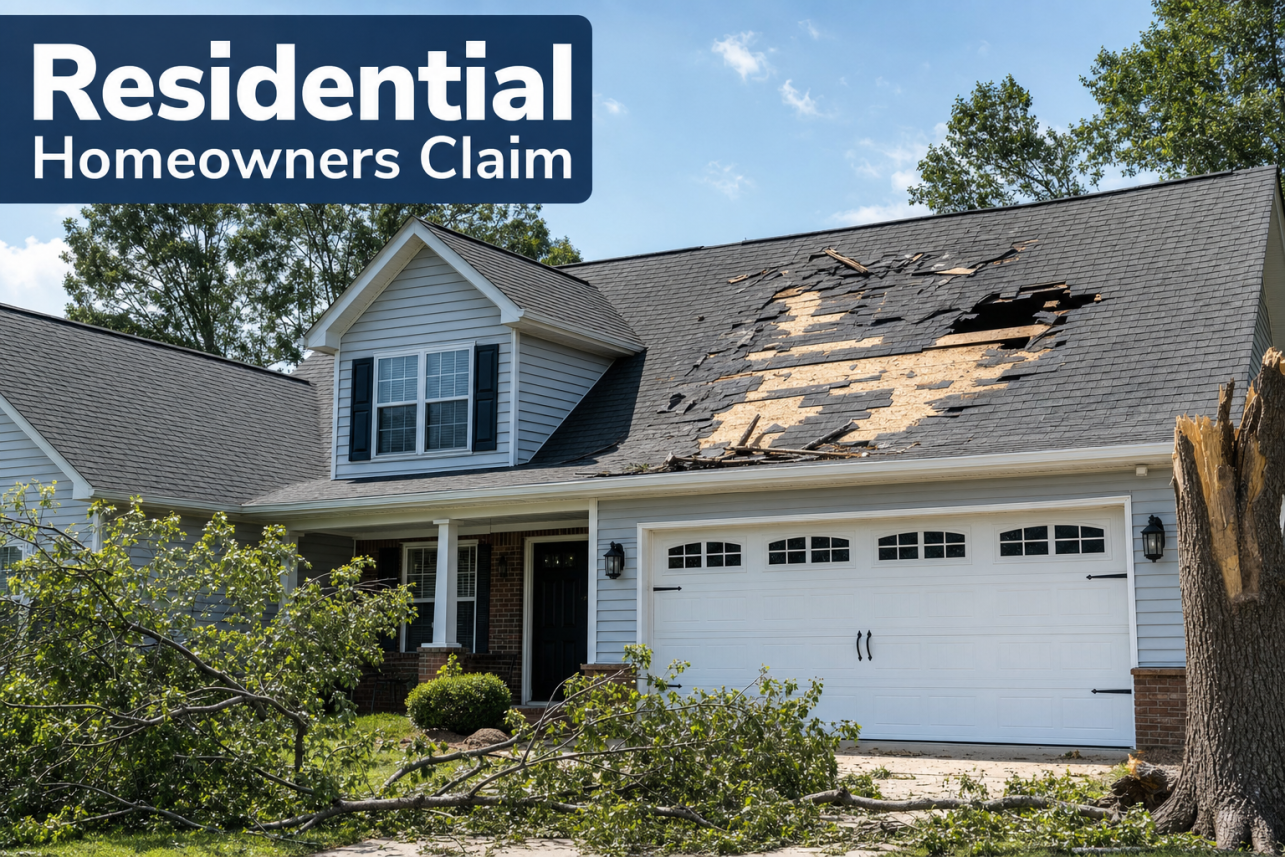
If you need help with a Residential Homeowners Claim Burlington NC policyholders can hire For The Public Adjusters, Inc. to represent them — not the insurance company. We are licensed and bonded public adjusters who document your damage, prepare the paperwork your insurer requires, and negotiate the settlement on your behalf. Whether your Alamance County home was hit by fire, a burst pipe, a fallen tree, or the remnants of a hurricane, our job is to make sure your loss is fully measured before any check is written.
What This Service Is
A public adjuster is the only type of insurance adjuster who works for you, the homeowner. The adjuster your insurance company sends is paid by the insurer, and the estimate they write reflects that relationship. When we handle a residential claim in Burlington, we read your policy line by line, inspect and photograph every area of damage — including the smoke residue, wet insulation, and structural issues that get missed on a quick walkthrough — and build an independent valuation of the loss.
That valuation covers the structure, your personal contents, and the extra costs of living elsewhere while repairs happen if your policy includes additional living expenses coverage. We then present the claim, respond to the insurer’s questions, and negotiate until the numbers reflect the real cost of putting your home back the way it was.
We handle fire, smoke, water, tree, vandalism, and hurricane or tornado damage claims, along with situations like a car striking your home. If a claim turns into a legal fight, we also work alongside insurance dispute lawyers. Courts have repeatedly sided with policyholders in these fights — in Bi-Economy Market, Inc. v. Harleysville Insurance Co., New York’s highest court ruled for an insured whose building burned, holding the insurer accountable for the consequences of failing to pay a covered fire loss promptly. Cases like that exist because insurers do underpay and delay, and homeowners who push back with proper documentation can win.
Common Problems
Will My Residential Homeowners Claim Burlington NC Payout Actually Cover The Repairs?
This is the worry we hear most, and it is a fair one. The first offer from an insurance company is often based on the insurer’s own pricing, with depreciation subtracted for the age of your roof, flooring, or siding. That is the difference between replacement cost and actual cash value — and in older Burlington homes, that depreciation deduction can strip thousands of dollars off a settlement.
After your deductible comes out too, many homeowners discover the check will not come close to a real contractor’s repair estimate. When that happens, the gap comes out of your pocket unless the claim is re-measured and renegotiated. We build our own detailed estimate first, so the conversation starts from what repairs actually cost in Alamance County, not from a number designed to close your file quickly.
My Claim Was Denied, Delayed, Or Lowballed — What Now?
A denial letter is not the end of your claim. Denials are often based on a rushed inspection, a policy exclusion applied too broadly, or missing proof of loss documentation — all of which can be challenged. Every policy also has claim filing deadlines and response timelines, and missing one can genuinely hurt you, so the worst move is to sit on a denial hoping it resolves itself.
Delays are just as common as denials. Weeks pass, the file changes hands, and meanwhile your home sits damaged. We reopen and supplement underpaid claims regularly; for example, a Water Damage Claim Help Bynum file often involves hidden moisture the first adjuster never tested for. New evidence supports a supplemental claim, and a properly documented dispute is far harder for an insurer to ignore than a frustrated phone call.
Should I Just Handle It Myself, Or Hire A Public Adjuster?
Small, simple claims — a few hundred dollars over your deductible — usually do not need professional help. But if your home has significant fire, water, or structural damage, you are negotiating against trained adjusters who handle claims every day. Most homeowners will file one or two major claims in a lifetime.
When choosing help, verify the adjuster is licensed in North Carolina. The NCDOI Public Adjusters Guide explains what public adjusters may and may not do in this state, including how fees work — we are paid a percentage of what is recovered, not upfront. A good adjuster shows you their inspection findings, walks you through your coverage limits, and explains your rights as a policyholder in plain English. If someone promises a specific dollar outcome before they have even read your policy, walk away — no honest adjuster guarantees results.

Our Process
Free Policy Review And Damage Inspection
We start by reading your actual policy — coverage limits, deductibles, exclusions, and endorsements — because everything else depends on what the contract says. Then we inspect your Burlington home thoroughly, including areas the insurance company’s adjuster may have skipped, like attics, crawl spaces, and wall cavities where smoke and moisture hide.
Documentation And Independent Valuation
We photograph and catalog the damage, inventory your personal contents, and prepare the proof of loss the insurer requires. Then we build a line-item estimate of structure and contents at current local repair pricing. This becomes the factual backbone of your claim — the document the insurance company must respond to.
Negotiation Through Settlement
We present the claim, meet the insurer’s adjuster on site if needed, and negotiate each disputed line. If your policy covers additional living expenses, we pursue those too. And if the insurer refuses to deal fairly, we coordinate with insurance dispute lawyers so you are never left facing the company alone.
| What Happens | Filing on Your Own | With For The Public Adjusters |
|---|---|---|
| Damage documentation | Carrier’s adjuster scopes what’s visible in a single visit | Independent roof-to-slab inspection with moisture mapping, photos, and lab testing when needed |
| Estimate preparation | You rely on the insurer’s numbers and pricing | Line-item Xactimate estimate covering every trade at current Alamance County pricing |
| Negotiation | You argue your own case against trained claim professionals | A licensed NC adjuster negotiates on your behalf, backed by documentation |
| Policy interpretation | Coverages like ALE, code upgrades, and matching often go unmentioned | Full policy audit so every applicable coverage is claimed |
| Typical outcome | First offers frequently miss hidden and secondary damage | Settlements routinely several times higher than the initial offer |
| Your time investment | Weeks of calls, paperwork, and follow-up on your own | We handle communication start to finish; you approve decisions |
Commonly Overlooked In The Public Adjusting Industry
- Discontinued shingle and siding matching rights — Carriers quote spot repairs without checking whether matching materials still exist, which can entitle you to full replacement of the slope or elevation.
- Wet insulation above ceilings and inside walls — It looks fine from below once the drywall dries, so nobody tests it — and it quietly loses R-value and grows mold for years.
- Ordinance and law (code upgrade) coverage — Homeowners don’t know they carry it, and adjusters rarely volunteer that rebuilt kitchens and roofs must meet current NC code at the insurer’s expense.
- Smoke residue in HVAC ductwork — Ducts are out of sight, so fire claims get scoped to the burn room while corrosive soot keeps recirculating through the whole house.
- Additional living expense (ALE) entitlement — Carriers often declare a home ‘technically livable’ to avoid paying hotel and meal costs the policy actually owes during remediation.
- Depreciation recovery after repairs — Recoverable depreciation must be claimed after work is complete, and thousands go unclaimed every year because no one tells the homeowner to ask for it.
- Roof decking delamination under ‘repairable’ shingles — You can’t see rotted or delaminated decking from the ground or even from on top of the roof, so it only surfaces when the new roof fails early.
- Contents inventory completeness — Homeowners under stress list what they remember instead of what they owned, leaving closets, garages, and attics uncounted in the settlement.
Case Studies
Case Study #1
Situation: A family in the Glen Raven area of Burlington came home after a July thunderstorm to find water staining across their living room ceiling and a soaked section of attic insulation. Their carrier sent an adjuster within a week.
Problem: The insurance company’s estimate came back at $4,200 — enough to patch a few shingles and repaint one ceiling. It ignored the saturated insulation, the damaged decking under the shingles, and moisture readings inside the wall cavity behind the fireplace chase.
Investigation: Our team performed a full roof-to-slab inspection: moisture mapping with thermal imaging, core sampling of the attic insulation, and a shingle brittleness test that showed the 14-year-old architectural shingles could not be repaired without cracking surrounding courses.
Findings: The decking was delaminated across roughly 300 square feet, the insulation held moisture well above acceptable levels, and matching shingles were discontinued — a fact that triggers full slope replacement under North Carolina’s matching considerations. Hidden wall moisture had already reached 28% in two stud bays.
Solution: We prepared a line-item Xactimate estimate documenting every trade — roofing, decking, insulation, drywall, paint, and mitigation — and submitted it with photo documentation, moisture logs, and the manufacturer’s discontinuation letter. We then handled all negotiations directly with the carrier’s desk adjuster.
Outcome: The claim settled at $38,600 — more than nine times the original offer. The homeowners received a full roof replacement, new insulation, interior repairs, and proper drying instead of a cosmetic patch over a wet structure.
Lesson: A carrier’s first estimate is a starting point, not a verdict. Water damage almost always extends beyond what’s visible from a ladder, and homeowners who accept the first number often pay for hidden damage out of pocket a year later.
Case Study #2
Situation: A retired couple near Lake Macintosh had a kitchen fire that started in a countertop appliance. The flames were out in minutes, but smoke traveled through the return-air ducts and coated most of the home.
Problem: The carrier scoped the loss as a ‘small kitchen fire’ — cabinets, one wall of drywall, and a cleaning allowance of $1,800 for the rest of the house. The couple was also told their additional living expense coverage ‘probably wouldn’t apply’ since the home was technically livable.
Investigation: We brought in an independent hygienist to test for soot and protein residue throughout the home, documented odor penetration in soft goods and HVAC components, and audited the couple’s policy for ALE, contents, and code-upgrade coverage the carrier never mentioned.
Findings: Lab results confirmed corrosive soot residue in bedrooms two floors from the kitchen, contamination inside the ductwork, and smoke absorption in insulation above the kitchen. NC building code required updated electrical work in the rebuilt kitchen — a covered code-upgrade cost the carrier omitted entirely.
Solution: We rebuilt the claim from scratch: full contents inventory with photographs and replacement pricing, duct cleaning and partial HVAC replacement, whole-home smoke remediation, code-compliant electrical, and documented hotel and meal costs under ALE while remediation made the home uninhabitable.
Outcome: Final settlement reached $94,300, including four weeks of additional living expenses the couple had been told they weren’t owed. Their home was professionally remediated rather than ‘wiped down.’
Lesson: Smoke doesn’t respect room boundaries, and neither should a claim. If a fire loss is scoped only where the flames touched, the settlement will fall short — often by tens of thousands of dollars.
| Your Situation | Best Move | Why It Matters |
|---|---|---|
| Storm or hail damage, offer seems low | Get a free claim review before accepting anything | First offers rarely account for decking, discontinued shingles, or multi-elevation damage |
| Water leak with visible ceiling or wall stains | Request moisture mapping before repairs begin | Painting over wet drywall traps moisture and voids future mold claims |
| Claim already denied | Have the denial letter and policy reviewed by a licensed adjuster | Many NC denials hinge on causation arguments that documented evidence can overturn |
| Fire or smoke damage beyond one room | Insist on hygienist testing throughout the home | Soot travels through ductwork; a ‘kitchen-only’ scope shortchanges the whole house |
| Small claim under your deductible | Consider paying out of pocket | Filing tiny claims can affect your record without meaningful payout |
| Carrier delaying past 30 days without explanation | Document every contact and bring in representation | NC claims-handling standards give you leverage when delays are unreasonable |
| Home uninhabitable during repairs | Confirm your ALE coverage before booking lodging | Additional living expenses are often owed even when carriers say the home is ‘livable’ |


Reviews
After hail hit our neighborhood off Church Street, our insurance company offered us $6,000 to ‘repair’ a roof their own contractor said needed replacing. For The Public Adjusters found damage on three elevations of siding the first adjuster never even photographed. We ended up with a full roof and siding settlement. I honestly didn’t know homeowners could hire their own adjuster until a neighbor told me.
Denise M., Burlington
A pipe burst in our crawl space while we were out of town and the carrier tried to blame it on ‘long-term neglect.’ These folks documented the plumbing failure, pulled moisture readings under the whole house, and pushed back with actual evidence. The denial got reversed and the claim paid for subfloor replacement and mold remediation. Worth every penny of their fee.
Marcus T., Alamance County
We filed a lightning claim ourselves and got stuck for three months with unreturned calls. Once we brought in this team, they took over every conversation with the adjuster, itemized all the fried electronics and the HVAC board we’d forgotten about, and had a revised offer in about five weeks. Only wish we’d called them on day one instead of month three.
Karen and Bill S., Burlington
Frequently Asked Questions
How Does The Process Work When I File A Residential Homeowners Claim Burlington NC With A Public Adjuster?
When you contact For The Public Adjusters, Inc., we start with a free consultation and a walkthrough of your Burlington home to assess the damage firsthand. Whether it’s roof damage from one of the spring hailstorms that roll through Alamance County, water intrusion from a burst pipe, or fire and smoke damage, we document everything before the insurance company’s adjuster ever sets foot on your property.
From there, we review your policy line by line. Most homeowners in Burlington have never read their full policy, and carriers count on that. We identify every coverage that applies to your loss, including dwelling, other structures, personal property, and additional living expenses if you’ve had to relocate during repairs.
Next, we prepare a detailed, itemized estimate using the same industry software insurance companies use, then submit and negotiate the claim on your behalf. We handle all communication with the carrier, attend inspections, and push back when the insurer’s numbers come in low, which they often do on first offers.
Throughout the process, you stay informed but off the phone with the insurance company. Our goal is a settlement that actually covers the cost of restoring your home to pre-loss condition at real Alamance County contractor pricing, not the discounted figures carriers like to use. Most residential claims we handle in Burlington resolve within 30 to 90 days, though complex fire or large water losses can take longer. We only get paid a percentage of what we recover for you, so there is no upfront cost and no fee if there is no recovery.
My Insurance Company Already Sent An Adjuster To My Burlington Home. Is It Too Late To Get Help?
No, it is not too late, and this is actually one of the most common situations we handle. Many Burlington homeowners call us after the insurance company’s adjuster has already inspected the damage and issued an estimate that seems far too low to cover actual repairs.
Remember, the adjuster your insurance company sends works for the carrier, not for you. Their estimates frequently miss hidden damage, underprice materials, or omit line items entirely, such as code-upgrade costs required by Alamance County building requirements, matching for discontinued shingles or siding, or proper drying and remediation after water losses.
We can step in at any stage: before you file, after the carrier’s inspection, after a low settlement offer, or even after a denial. In North Carolina, you generally have three years from the date of loss to pursue a property claim, and most policies allow supplemental claims when additional damage or costs are discovered after the initial payment.
When we take over an underpaid claim, we re-inspect the property, prepare our own detailed estimate, and reopen negotiations with documentation the carrier cannot easily dismiss. It is common for us to find damage the original inspection missed, especially with hail on architectural shingles, wind-lifted roofing that has resealed, or moisture trapped behind walls and under flooring.
If you have already cashed a settlement check, that usually does not close the door either. Cashing a check is rarely a final release in North Carolina. Bring us your paperwork and the carrier’s estimate, and we will tell you honestly whether there is more money on the table.
What Types Of Damage Are Covered Under A Residential Homeowners Claim Burlington NC Policyholders Typically File?
Most homeowners policies in Burlington cover a broad range of sudden and accidental losses, though the details depend on your specific policy form. The claims we handle most often in Alamance County involve wind and hail damage to roofs, siding, and gutters, which is a regular occurrence given the severe thunderstorms that track through the Triad each spring and summer.
Water damage is another major category. Burst supply lines, failed water heaters, washing machine hose ruptures, and HVAC condensation leaks are all typically covered when the damage is sudden. Slow leaks and long-term seepage are usually excluded, which is exactly where carriers dispute claims and where our documentation makes a difference.
Fire and smoke losses, lightning strikes, tree falls onto the home, theft, and vandalism are also standard covered perils. Older homes in Burlington’s established neighborhoods often face additional complications, such as plaster walls, hardwood floors, and materials that are expensive to match or replace, and carriers routinely underestimate those costs.
What is generally not covered: flood damage from rising water requires a separate flood policy, and gradual wear, deterioration, and deferred maintenance are excluded. Wind-driven rain can fall into a gray area depending on how the water entered the home, and we frequently fight for coverage in those disputes.
If you are unsure whether your loss qualifies, call For The Public Adjusters, Inc. before assuming anything. We review your policy at no charge and give you a straight answer about whether filing makes sense, because filing a claim that will not pay can affect your record without any benefit to you.
How Much Does It Cost To Hire A Public Adjuster In Burlington, And Is It Worth It For A Smaller Claim?
For The Public Adjusters, Inc. works on contingency, meaning we charge a percentage of the settlement we recover for you. There are no upfront fees, no hourly billing, and no charge at all if we do not recover money. North Carolina regulates public adjuster fees, and we put our percentage in writing before any work begins, so there are never surprises.
For many Burlington homeowners, the math strongly favors representation. Industry studies and our own case history show that professionally adjusted residential claims routinely settle for significantly more than homeowners obtain on their own, often enough that the increase far exceeds our fee. That gap tends to be widest on roof claims, fire losses, and water damage, where hidden or underscoped damage is common.
For smaller claims, we will tell you honestly whether hiring us makes sense. If your loss is straightforward and the carrier’s offer is fair relative to real Alamance County repair costs, we will say so during the free consultation. We would rather give you a candid assessment than take on a claim where we cannot add meaningful value.
That said, claims that look small often are not. A modest kitchen water leak can involve cabinet replacement, flooring continuation into adjoining rooms, and drying costs the carrier’s first estimate ignored. Hail damage that looks cosmetic may justify full roof replacement once properly documented.
The consultation costs nothing, so before you accept any settlement on a homeowners claim in Burlington, let us review the numbers. At minimum, you will know exactly where you stand.
How Long Does A Residential Homeowners Claim Burlington NC Typically Take To Settle With A Public Adjuster Involved?
Most residential claims we handle in Burlington settle within 60 to 120 days, though the timeline depends on the damage type and how the insurance carrier responds. A straightforward wind or hail claim on a roof might wrap up in six to eight weeks, while a major fire or water loss involving structural repairs and personal property inventories can run three to five months.
North Carolina insurance regulations require carriers to acknowledge a claim promptly and to pay undisputed amounts within 30 days of reaching an agreement. Where things slow down is the negotiation phase, especially when the carrier’s initial estimate misses damage or underprices local repair costs. Our job is to compress that phase by presenting a complete, well-documented estimate from the start, which leaves the carrier far less room to delay.
We also account for local factors. After a widespread hail event across Alamance County, carriers get flooded with claims and response times stretch. Having a professional pushing your file, following up on every deadline, and escalating when needed keeps your claim from sitting at the bottom of a desk adjuster’s queue.
If your claim has already been open for months without resolution, that is often a sign it was underdocumented from the beginning. We can step in mid-claim, rebuild the estimate, and get the negotiation moving again. Homeowners are frequently surprised how quickly a stalled file progresses once the carrier receives a detailed, defensible scope of loss they have to respond to line by line.
My Homeowners Claim In Burlington Was Denied Or Underpaid. Can For The Public Adjusters, Inc. Still Help?
Yes, and this is actually one of the most common situations we handle. A denial or a low payment is rarely the end of the road. In North Carolina, you generally have the right to dispute the carrier’s decision, submit new evidence, request a re-inspection, and invoke the appraisal clause found in most homeowners policies.
The first thing we do is review your policy and the carrier’s denial or estimate letter line by line. Denials often hinge on how the damage was characterized. For example, a carrier may call roof damage “wear and tear” when a closer inspection shows clear hail impact marks consistent with a documented storm date in Alamance County. Reframing the loss with proper evidence changes the conversation entirely.
For underpaid claims, we build our own independent estimate using current Burlington-area labor and material pricing, then compare it against the carrier’s numbers. Missing line items like code-required upgrades, matching requirements for siding or shingles, and proper drying protocols after water damage are frequent sources of underpayment.
Timing matters. North Carolina policies typically include deadlines for disputing a claim decision and filing suit, so do not sit on a denial letter for a year. Bring us your paperwork as soon as possible, even if the claim was closed. We regularly reopen claims and recover significantly more than the original offer, and our review of your situation costs you nothing upfront.
What Should I Document Before Filing A Residential Homeowners Claim Burlington NC Insurers Will Take Seriously?
Strong documentation from day one is the single biggest factor in how a claim turns out. Before you even call your insurance company, photograph and video everything. Capture wide shots of each affected room or roof slope, then close-ups of specific damage, water lines, hail impacts, or charring. Time-stamped photos are best.
Do not throw anything away until it has been documented. Damaged furniture, electronics, clothing, and even food spoiled by a power outage after a covered event can all be part of your recovery. Make a written list with approximate purchase dates and values, and pull receipts, credit card statements, or old photos showing the items in your home when you can.
Protect the property from further damage, because your policy requires it, but keep receipts for tarps, board-up materials, water extraction, or emergency contractors. Those mitigation costs are typically reimbursable. If you have to leave your home, save every receipt for lodging, meals, and mileage, since additional living expense coverage may apply.
Finally, locate your full policy, not just the declarations page. The endorsements and exclusions buried in the back determine what you can actually claim. When homeowners in Burlington bring us in early, we handle this documentation professionally, including moisture readings, detailed room-by-room inventories, and a contractor-grade estimate. That upfront work is exactly what makes a carrier take the claim seriously and pay it correctly the first time.

Are Storm And Hail Claims Common For Burlington And Alamance County Homes, And Does That Affect How My Claim Is Handled?
Very common. The Piedmont Triad sits in a corridor that sees severe thunderstorms, damaging straight-line winds, and hail nearly every spring and summer, and Burlington takes its share of hits. We also see winter claims from ice damming, frozen pipe bursts, and tree limbs brought down on roofs by ice accumulation.
The frequency of storms here cuts both ways for homeowners. On one hand, carriers are familiar with the weather patterns and have storm date records they can verify. On the other hand, after a major event, insurers deploy out-of-state catastrophe adjusters who may spend fifteen minutes on your roof, miss damage on shaded slopes, and apply pricing that does not reflect what local roofers actually charge in Alamance County.
Hail damage is especially tricky. Bruised shingles and fractured mats are not always obvious from the ground, and carriers frequently deny roofs that a trained eye would document as a total loss. Older homes in established Burlington neighborhoods add another wrinkle, since discontinued shingle and siding styles can trigger matching disputes that inflate what you are truly owed.
Our team inspects the property independently, ties the damage to a verified storm date, and prices repairs using real local market rates. If your roof or exterior was hit and the carrier’s response felt rushed or the number felt low, a second professional opinion costs nothing and often reveals thousands of dollars in missed damage.
What Deadlines Apply To A Residential Homeowners Claim Burlington NC Homeowners Need To Know About?
North Carolina gives you a limited window to act, and missing a deadline can sink an otherwise valid claim. Most homeowners policies require “prompt” notice of loss, which in practice means reporting damage within days, not months. Waiting too long gives the insurer grounds to argue the damage worsened because of your delay.
Beyond the notice requirement, North Carolina generally allows three years to file suit on a property insurance dispute, though many policies attempt to shorten that contractual window. Some carriers also impose deadlines for submitting a sworn proof of loss, often 60 days after they request it. These clocks run whether or not you understand them.
For storm damage in Burlington and the surrounding Alamance County area, timing matters even more. Hail bruising on shingles and wind-lifted flashing can look minor for months, then cause interior leaks the carrier blames on wear and tear rather than the storm. Documenting and reporting quickly protects the causal link between the weather event and the damage.
Our team tracks every deadline from day one — notice, proof of loss, supplemental claim windows, and appraisal demands. If you’re already past a deadline, don’t assume the claim is dead. Some deadlines are enforceable only if the insurer can show your delay actually harmed its investigation, and North Carolina courts have pushed back on carriers who use technicalities to avoid paying. Call us and we’ll review where your specific claim stands before you give up anything.
My Insurer Paid Actual Cash Value On My Burlington Claim. How Do I Recover The Depreciation They Held Back?
This trips up more homeowners than almost anything else. If you carry replacement cost coverage — and most Burlington homeowners do — the insurer typically pays in two stages. The first check is actual cash value: the replacement cost minus depreciation. The withheld depreciation, called recoverable depreciation, is only released after you complete the repairs and prove what you spent.
Here’s where people lose money. If you never finish the work, never submit final invoices, or miss the policy’s deadline for claiming the holdback — often 180 days to two years depending on the policy — the insurer keeps that money. On a roof claim, recoverable depreciation can be 30% to 50% of the total, so this is real money left on the table.
The depreciation calculation itself is also negotiable. Carriers sometimes apply aggressive depreciation schedules, treating a 12-year-old architectural shingle roof as if it were near the end of its life when it had another decade of service. We routinely challenge those percentages with documentation of the roof’s actual condition before the loss.
As your public adjuster in Burlington, we manage the entire two-stage payout: verifying the ACV payment is calculated correctly, tracking the deadline to claim the holdback, compiling contractor invoices in the format the carrier requires, and pushing back when the released amount doesn’t match what was withheld. If you’ve already completed repairs and the insurer is stalling on the second check, that’s a common and very fixable problem.
My Mortgage Company Is Listed On The Insurance Check. How Does That Work During A Homeowners Claim In Burlington?
If you have a mortgage, your lender is almost certainly named on your policy, which means claim checks above a certain amount will be made out to both you and the mortgage company. You can’t just deposit it — the lender has to endorse it, and most route the funds through a loss draft department that releases money in stages as repairs progress.
This catches Burlington homeowners off guard constantly. The lender may require a signed contractor agreement, a W-9 from the contractor, inspections at 50% and 100% completion, and lien waivers before releasing each installment. National servicers handle this through centralized processing centers, and paperwork gets lost or stalled more often than it should.
The practical risk is a cash-flow squeeze. Your roofer in Alamance County wants a deposit to order materials, but the loss draft department won’t release the first installment until documents clear. We help homeowners sequence this correctly — getting the carrier’s payment schedule, the contractor’s draw schedule, and the lender’s release schedule aligned so the project doesn’t stall mid-repair.
One more thing worth knowing: the mortgage company’s involvement applies to payments for damage to the structure itself. Payments for your personal property contents and additional living expenses typically come to you alone, without the lender’s endorsement. If your carrier lumped everything into one jointly-payable check, we can request the payment be split correctly, which often frees up funds you need right away.
Will I Have To Move Out During A Residential Homeowners Claim Burlington NC Repairs, And Who Pays For That?
Whether you can stay in your home depends on the damage, but who pays if you can’t is spelled out in your policy under additional living expenses, sometimes called loss of use coverage. If a fire, major water loss, or storm damage makes your Burlington home uninhabitable, your policy pays the reasonable increase in your living costs while repairs are underway.
That coverage is broader than most people realize. It includes temporary rent or hotel costs, but also the increased cost of meals if you’re stuck without a kitchen, pet boarding, extra mileage if your temporary housing is farther from work or your kids’ schools, laundry costs, and storage for furniture during reconstruction. Carriers rarely volunteer this list.
The standard for “uninhabitable” is also worth fighting over. A house with no functioning HVAC in a North Carolina August, no usable bathroom, or active mold remediation is not reasonably livable, even if the walls are standing. We’ve seen adjusters pressure families to stay in homes mid-demolition to cut ALE costs, and that’s not something you have to accept.
When we handle a Residential Homeowners Claim Burlington NC families are dealing with after a serious loss, we build the ALE claim from day one: comparable rental rates in Alamance County, receipts, mileage logs, and a realistic repair timeline so the coverage doesn’t run out before the work is done. If your carrier is trying to cap your ALE early or move you back in prematurely, get in touch — that’s a negotiation we handle regularly.
Will Filing A Residential Homeowners Claim Burlington NC Affect My Insurance Premiums Or Policy Renewal?
It can, but the picture is more nuanced than most homeowners fear. In North Carolina, insurers generally cannot single you out for a rate increase because of a single weather-related claim, since acts of nature like hail or wind are outside your control. Widespread storm events across Alamance County often lead to area-wide rate adjustments regardless of whether you personally filed.
Where claim history matters more is with non-weather losses, such as water leaks or theft, especially if there is more than one within a few years. Those show up in the CLUE database that insurers check at renewal, and multiple claims can affect renewal offers.
Here is the practical advice we give Burlington homeowners: never avoid a legitimate claim out of fear. If a storm damaged your roof and you skip the claim, you absorb the full repair cost yourself, and unrepaired damage can lead to future denials for neglect. For smaller losses close to your deductible, it may make sense to pay out of pocket, and we will tell you honestly when that is the case.
What you should not do is call your insurer to “ask about” damage before deciding. Many carriers log that inquiry as a claim with a zero payout, which still appears on your record. Talk to our team first. We can evaluate the damage, estimate the real repair cost, and help you make an informed decision before anything goes on your record.
My Contractor’s Repair Estimate Is Much Higher Than What My Insurance Company Offered For My Burlington Home. Why The Gap, And What Can Be Done?
This is one of the most common calls we get from homeowners in Burlington, and the gap is rarely because your contractor is inflating numbers. Insurance company estimates are typically written in Xactimate using pricing and scope decisions that favor the carrier. They often omit items a real contractor cannot skip: code-required upgrades, drywall matching, paint for entire rooms rather than patches, debris removal, and overhead and profit for jobs requiring multiple trades.
Local pricing matters too. Labor and material costs in Alamance County have risen significantly, and carrier price lists do not always keep pace with what Triad-area contractors actually charge. A roofer quoting real 2024 material costs will almost always land above a desk adjuster’s figure.
When we take over a homeowners claim in Burlington, we prepare our own line-by-line estimate with photographs, measurements, and documentation supporting every item. Then we negotiate directly with the carrier’s adjuster, item by item, until the scope reflects what it genuinely costs to restore your home.
Importantly, you are not obligated to accept the insurer’s first estimate, and cashing an initial check usually does not close your claim in North Carolina. Supplements are a normal part of the process. If your contractor’s bid and the carrier’s offer are thousands of dollars apart, that gap is exactly the problem For The Public Adjusters, Inc. exists to close, and our fee comes only from the additional money we recover.
The Insurance Company Wants A Recorded Statement About My Burlington Homeowners Claim. Should I Give One, And Can You Be There?
Be careful here. A recorded statement is one of the most consequential moments in a homeowners claim, and most policyholders walk into it unprepared. Your policy likely requires you to cooperate with the investigation, so refusing outright can jeopardize coverage. But how and when you give that statement matters enormously.
Carriers use recorded statements to lock in your version of events early, often before you fully understand the extent of your damage. An innocent guess about when a leak started, or an offhand comment about prior wear, can later be used to limit or deny payment. Adjusters ask questions designed to surface exclusions, and homeowners answer honestly without realizing the coverage implications.
When we represent a Burlington homeowner, we prepare you before any statement is given. We review your policy, walk through the timeline of the loss, and make sure you understand what the questions are really asking. In many cases we can be present or coordinate the scheduling so the statement happens after the damage has been properly documented, not before.
One more distinction: a recorded statement is different from an examination under oath, which is a formal, sworn proceeding. If your carrier requests an examination under oath, that is a signal the claim is being scrutinized closely, and you should get professional representation before proceeding. Call us before you agree to either one. Getting the facts on record correctly the first time is far easier than trying to undo a damaging statement later.

My Roof Shingles Or Siding Are Discontinued And Nothing Matches. Does My Insurer Have To Replace Everything?
This is known as a matching issue, and it comes up constantly in older Burlington neighborhoods where roofing and siding products from the 1990s and 2000s have long been discontinued. If hail damages one slope of your roof but the shingle line no longer exists, a patch repair leaves you with a visibly mismatched home.
North Carolina does not have a statute that flatly requires full replacement for mismatch, which is exactly why carriers often try to pay for repairing only the damaged section. But that is not the end of the story. Policy language about restoring the property to its pre-loss condition, uniform appearance arguments, and manufacturer discontinuation documentation can all support a full-slope or full-elevation replacement. Some policies also include matching endorsements homeowners do not realize they have.
When we handle a Residential Homeowners Claim Burlington NC homeowners bring us involving discontinued materials, we obtain written confirmation from suppliers and manufacturers that the product is unavailable, document the visual mismatch a partial repair would create, and present the carrier with a scope that restores the home properly. In many cases this turns a few-thousand-dollar patch offer into full replacement of the roof or an entire siding elevation.
If your carrier’s estimate only covers a section of roof or one wall of siding, do not sign off until the matching question has been fully explored. The difference in settlement value on Alamance County homes is often substantial, and it is one of the areas where professional representation earns its keep fastest.
Local Relevance
Burlington sits in the heart of the North Carolina Piedmont, and its weather does real damage to homes. Humid summers bring severe thunderstorms with hail and lightning, the remnants of Atlantic hurricanes push heavy rain and tornado risk inland to Alamance County, and winter ice storms bring mature oaks and pines down onto roofs. We handle those storm and tree losses locally, the same way our team manages a Tree Damage Insurance Claim Help Carrboro file one county east.
Burlington’s housing stock also matters. As a historic textile mill town, the city has a large share of homes built in the early and mid twentieth century, with plaster walls, original hardwood floors, and aging plumbing and electrical systems. Those features make fire and water losses more expensive to repair correctly — and easier for an insurer to undervalue. The National Fire Protection Association has long noted that cooking and heating are leading causes of home fires, and in older houses those fires spread through wall cavities in ways a surface-level estimate never captures.
We serve homeowners throughout Alamance County and across the central Piedmont — the same claim expertise behind our work as a Public Adjuster in Garner and our Fire Claim Adjuster Wake Forest services. If rising water from a creek or storm is involved, that typically falls under a separate flood policy rather than your homeowners coverage, and the Federal Emergency Management Agency’s flood insurance program has its own rules and deadlines — another reason to get experienced help before you file.
Many Burlington homes date to the city’s mill-town era, and insurers often apply steep depreciation to original plaster, millwork, and hardwood when settling fire or water losses; documenting true replacement cost for those materials — not modern drywall equivalents — is frequently where the largest recovery gap sits in an Alamance County claim.
Get An Honest Read On Your Burlington Claim Before You Settle
Before you accept the insurance company’s number, let For The Public Adjusters, Inc. review your policy and inspect the damage — at no upfront cost. We are licensed and bonded, we work only for policyholders, and we are paid from what we recover, never in advance. One conversation can tell you whether your claim is being valued fairly.
Request Your Free Claim Review
Call us: (336) 331-8300
Helpful Resources
- NCDOI Public Adjusters Guide
- National Fire Protection Association (NFPA)
- Federal Emergency Management Agency (FEMA)
- North Carolina Department of Insurance — State regulator that licenses public adjusters and protects NC policyholders
- FEMA flood insurance information — Federal resource explaining flood coverage under the NFIP
Serving Burlington · Alamance
Last updated: September 12, 2026