A public adjuster Mebane NC policyholders hire works for you — not the insurance company — to document your property loss, value the damage correctly, and negotiate your claim. For The Public Adjusters, Inc. is licensed and bonded, handling fire, water, smoke, tree, flood, and storm-related claims for homes and businesses throughout Mebane and Alamance County. We review your policy, build the estimate the carrier's adjuster often leaves incomplete, and manage the claim from first notice to final settlement.
What This Service Is
When a fire, burst pipe, fallen tree, or flood damages your property, your insurance company sends its own adjuster to assess the loss. That adjuster is paid by the carrier. A public adjuster is the licensed professional who represents the policyholder's side instead.
Our job is to read your policy line by line, inventory the damage to the structure and your contents, prepare a detailed independent estimate, and negotiate directly with the insurer on your behalf. In North Carolina, this work is regulated — the NCDOI Public Adjusters Guide explains that public adjusters must be licensed by the state and act solely in the interest of the insured, which is exactly how we operate.
For The Public Adjusters, Inc. handles residential homeowners claims and commercial business claims across Mebane. That includes fire and smoke damage, water damage from plumbing or appliance failures, tree damage, vandalism, arson claims where you are the innocent policyholder, a car striking your home, and flood losses under NFIP flood policies. We do not handle claims involving vehicles, health, life, or cell phones — property claims are our entire focus.
We work on a percentage of the recovered claim, so our interests are aligned with yours from day one. While no adjuster can guarantee a specific outcome, our role is to make sure nothing covered under your policy gets missed, minimized, or quietly excluded.
Common Problems
What Does A Public Adjuster Mebane NC Homeowners Hire Actually Cost — And Is It Worth It?
Public adjusters in North Carolina work on contingency: a percentage of what the claim pays, with no upfront fee. If the claim recovers nothing, you owe nothing for our adjusting work.
The real question is what an incomplete claim costs you. Carrier estimates on fire and water losses frequently omit items like code-required upgrades, hidden moisture damage inside wall cavities, smoke residue in HVAC systems, and full contents inventories. A properly documented claim often changes the settlement conversation entirely.
We never promise a specific dollar result — no honest adjuster can. What we can promise is that every covered item gets identified, documented, and put in front of the insurer in a form they have to respond to.
My Insurance Company Is Delaying, Lowballing, Or Denying My Claim. What Now?
This is the most common reason Mebane policyholders call us. The carrier's first offer arrives weeks late, covers a fraction of the repair cost, or the claim gets denied on a technicality buried in the policy language.
Courts have long recognized that insurers can be held accountable when they mishandle property claims. In Bi-Economy Market, Inc. v. Harleysville Insurance Co., the New York Court of Appeals sided with a business owner whose fire claim was badly delayed and underpaid, allowing the insured to pursue consequential damages beyond the policy limits. Cases like that exist because insurers do not always get it right the first time.
Our role is to reopen the conversation with documentation the carrier cannot dismiss — an independent estimate, photographs, moisture readings, contents inventories, and a clear reading of your own policy provisions. Most disputes resolve through negotiation once the file is complete.
Should I Just Handle The Claim Myself, Or Hire Someone — And How Do I Pick?
For a small, straightforward loss, handling it yourself can be reasonable. For a significant fire, a whole-house water loss, or a flood claim, the paperwork, deadlines, and estimating standards get complicated fast — and every gap in your documentation becomes a reason to pay less.
If you do hire help, verify the license. North Carolina requires public adjusters to be licensed, and you can confirm any license through the state Department of Insurance. Ask whether they are bonded, whether they handle your specific loss type, and whether the fee agreement is in writing.
For The Public Adjusters, Inc. is licensed and bonded, and we put every fee term in writing before work begins. A good adjuster should be able to explain your policy to you in plain language — if they can't, keep looking.
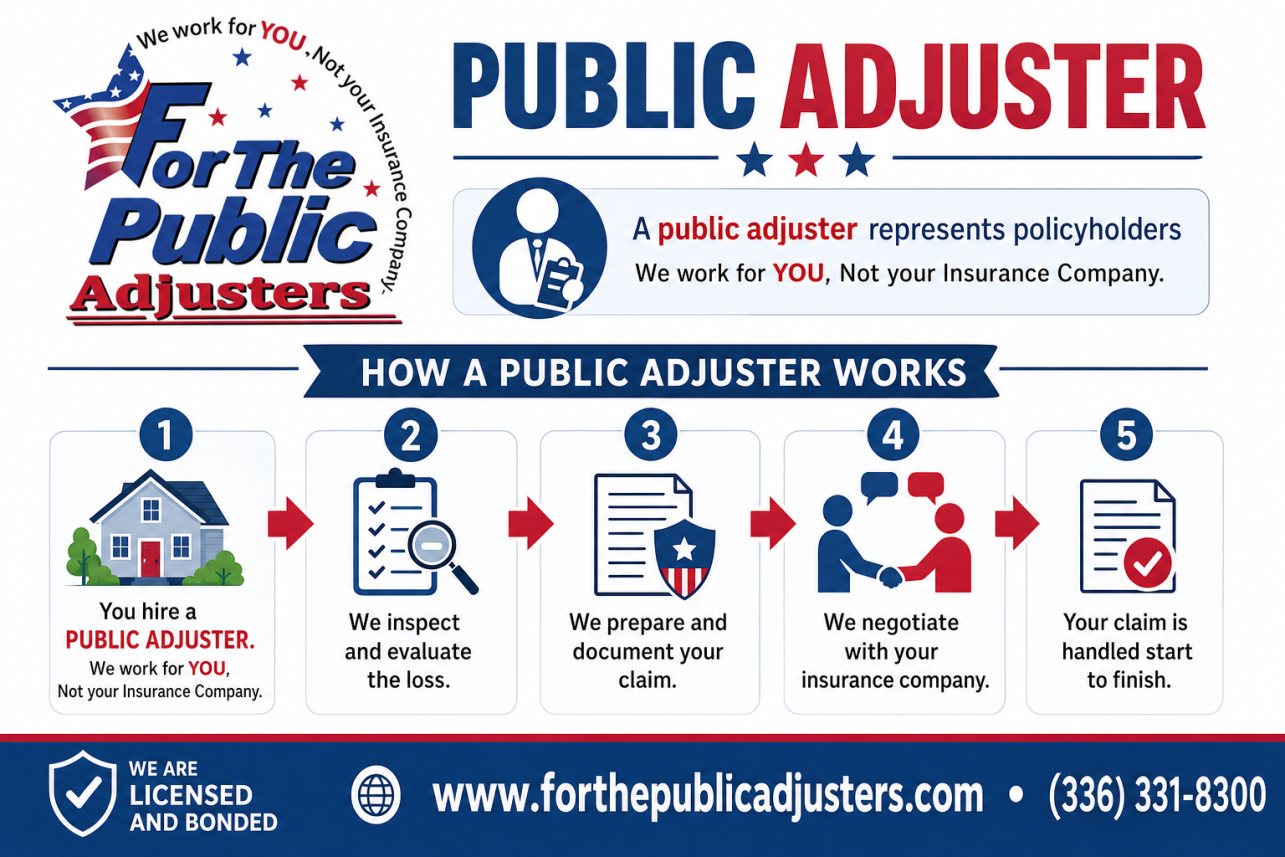
Our Process
Free Policy And Damage Review
We start by reading your actual policy — coverage limits, endorsements, exclusions, and deadlines — then inspect the damage in person. This tells us what the claim is genuinely worth before anyone negotiates. There is no cost or obligation for this review.
Documentation And Independent Estimate
We photograph and measure everything, inventory damaged contents room by room, and build a line-item estimate using the same estimating standards insurers use. Hidden damage — smoke in ductwork, moisture behind drywall, compromised framing under a fallen tree — gets found and included now, not discovered after the claim closes.
Negotiation And Settlement
We submit the claim package, meet the carrier's adjuster at the property, and negotiate every disputed line item on your behalf. You approve any settlement before it is accepted. We stay on the file until the claim is resolved, including supplemental claims if additional damage surfaces during repairs.
| What Happens | Filing Alone | With Our Team |
|---|---|---|
| Who scopes the damage | The carrier's adjuster, who works for the insurance company | An independent adjuster working only for you, using moisture meters, thermal imaging, and line-item estimating |
| Policy interpretation | You rely on the carrier's reading of exclusions and coverage limits | We read the full policy — including matching provisions, code upgrade coverage, and loss-of-use benefits carriers rarely volunteer |
| Negotiation | You against a trained claims professional | Documented supplements, rebuttals to engineer reports, and appraisal when needed |
| Hidden damage | Often missed until after you've settled and signed | Found and documented before settlement — wall cavities, ductwork, subfloors, roof decking |
| Typical result | First offers frequently cover a fraction of the true repair cost | Our clients routinely recover multiples of the initial offer |
Commonly Overlooked In The Public Adjusting Industry
- Matching coverage for continuous flooring and siding — Carriers offer to patch the damaged section, and homeowners don't realize North Carolina claims often support replacing the full continuous run when a reasonable match doesn't exist.
- Code upgrade (ordinance or law) coverage — Repairs in Mebane must meet current building code, but carriers pay to rebuild to old standards unless someone specifically invokes the ordinance-or-law provision in the policy.
- Smoke contamination inside HVAC ductwork — It's invisible without opening the system, so carrier estimates cover visible soot on walls while contaminated ducts keep recirculating smoke residue for years.
- Moisture trapped behind cabinet bases and inside wall cavities — Field adjusters scope what they can see in a single visit and rarely pull toe kicks or use thermal imaging, so hidden saturation becomes a mold claim six months later.
- Additional living expense (ALE) benefits — Families paying for hotels, meals, and laundry during repairs often don't know their policy reimburses those costs — and carriers seldom bring it up unprompted.
- Depreciation recovery deadlines — Replacement-cost policies hold back depreciation until repairs are complete, and homeowners routinely forfeit thousands by missing the window to claim it back.
- Roof decking and underlayment damage beneath intact shingles — A roof can look fine from the ladder while hail-fractured decking underneath fails inspection, which is why core samples and attic-side checks matter.
- The appraisal clause as an alternative to lawsuits — Most policyholders think a low offer means hiring a lawyer, not realizing their own policy contains a faster, cheaper dispute-resolution process built in.
Case Studies
Case Study #1
Situation: A family off Fifth Street in Mebane came home from a weekend trip to find their upstairs bathroom supply line had burst, sending water through the ceiling into the kitchen and dining room below.
Problem: Their carrier's field adjuster spent forty minutes on site and issued an estimate of $11,400 that covered drywall patching and carpet cleaning but ignored the hardwood flooring, the kitchen cabinets that had wicked water up from the base, and any mold remediation despite visible growth behind the toe kicks.
Investigation: We performed our own moisture mapping with thermal imaging and pin meters, documented elevated readings inside wall cavities the carrier never opened, and pulled cabinet bases to photograph swelling and microbial growth. We also reviewed the policy for matching provisions on the continuous hardwood flooring that ran through three rooms.
Findings: The moisture had traveled far beyond the carrier's scoped area. The hardwood could not be partially replaced and reasonably matched, the lower cabinet run was structurally compromised, and mold remediation required containment and third-party clearance testing — none of which appeared in the original estimate.
Solution: We prepared a line-item estimate with photo documentation tied to each entry, submitted a formal supplement with the moisture logs and remediation protocol, and negotiated directly with the desk adjuster and their reinspection team.
Outcome: The claim settled at $58,900 — more than five times the original offer — covering full flooring replacement across the continuous run, a matched cabinet package, professional mold remediation with clearance testing, and additional living expenses for the two weeks the kitchen was unusable.
Lesson: Water claims are almost never as small as the first estimate suggests. What you can see on day one is rarely the full extent of the damage, and carriers scope what is visible, not what is hidden.
Case Study #2
Situation: The owner of a small commercial building near downtown Mebane, housing two tenant businesses, took significant hail and wind damage to the flat membrane roof during a spring storm that rolled through Alamance County.
Problem: The insurance company's engineer report attributed the roof leaks to 'wear and tear and deferred maintenance' and denied the roof portion of the claim entirely, offering only $4,200 for interior water staining. The owner was facing a $90,000+ roof replacement out of pocket.
Investigation: We brought in an independent roofing consultant, pulled NOAA weather data confirming 1.5-inch hail on the date of loss, and conducted a core sample inspection that showed fresh fracture patterns in the membrane consistent with impact — not age. We compared pre-storm satellite imagery against post-storm conditions.
Findings: The fracture patterns, hail spatter on rooftop HVAC units, and dated weather records directly contradicted the wear-and-tear conclusion. The carrier's engineer had inspected on a dry day, weeks after the storm, and never performed core samples.
Solution: We filed a detailed rebuttal package challenging the engineer report point by point, invoked the policy's appraisal provision when the carrier held firm, and presented our evidence to the umpire.
Outcome: The appraisal award came in at $187,300, covering full membrane replacement, interior repairs to both tenant suites, and lost rental income during the repair period.
Lesson: A denial based on 'wear and tear' is an opinion, not a final answer. Independent testing and documented weather data can overturn an engineer report — but you have to build the evidence, not just argue.
| Your Situation | Handle It Yourself? | What It Depends On |
|---|---|---|
| Small claim under your deductible or barely above it | Usually yes | If the total loss is close to your deductible, a claim may not be worth filing at all — we'll tell you honestly |
| Water damage that spread beyond one room | No | Hidden moisture in walls, subfloors, and cabinets almost always exceeds the carrier's first scope |
| Fire or smoke loss of any size | No | Smoke contamination in HVAC systems, insulation, and contents is routinely undervalued or missed entirely |
| Storm damage the carrier calls 'cosmetic' or 'wear and tear' | No | These denials are opinions that can be challenged with core samples, weather data, and independent inspections |
| Claim already denied or delayed for weeks | No | Denials can be reversed with proper documentation, and NC policies include appraisal rights most homeowners never invoke |
| Carrier's offer feels low but you're not sure | Get a free review first | We review settlements at no cost — if the offer is fair, we'll say so; if it's short, you'll know exactly by how much |
| Commercial or rental property loss with income interruption | No | Business interruption and lost rent calculations are complex, and carriers rarely calculate them in your favor |

Reviews
After a kitchen fire, our insurance company offered $23,000 and acted like we should be grateful. For The Public Adjusters found smoke damage in our HVAC ducts and attic insulation that the carrier's adjuster never even looked at. Final settlement was over $71,000. They handled every call so I didn't have to argue with anyone.
Danielle R., Mebane
Hail hit our neighborhood and my carrier said the roof damage was 'cosmetic.' My neighbor two doors down got a full replacement, so I called these guys. They documented every hit with chalk and photos, filed a supplement, and got my full roof plus gutters and window screens covered. Wish I'd called them before I ever filed.
Marcus T., Alamance County
We had a slow pipe leak that turned into a mold problem behind our laundry room. The insurance company initially denied it as 'long-term seepage.' The team dug into the policy language, brought in a leak detection specialist to prove when it started, and got the denial reversed. It took a couple of months, but they kept us updated the whole way.
Sandra K., Mebane
Frequently Asked Questions
What Does A Public Adjuster Mebane NC Homeowners Hire Actually Do For My Insurance Claim?
A licensed public adjuster works exclusively for you — the policyholder — not the insurance company. When you hire For The Public Adjusters, Inc., we take over the entire claim: documenting the damage, reading your policy line by line, preparing a detailed estimate, and negotiating directly with your carrier's adjuster.
That matters because the adjuster your insurance company sends is paid by the insurer. Their estimate often misses hidden damage — water that traveled behind walls, hail bruising on shingles that only shows up on close inspection, or code-upgrade costs your policy actually covers.
In Mebane, we see this constantly with wind and hail claims on homes near downtown and in the newer neighborhoods off Mebane Oaks Road. A roof that looks fine from the driveway can have fractured mat under the granules, and carriers rarely volunteer that finding.
We photograph everything, measure it, price it with the same estimating software insurers use, and then argue the file until the settlement reflects what repairs genuinely cost in Alamance County. You stay informed at every step, but the paperwork, phone calls, and negotiation are our job, not yours.
How Much Does It Cost To Hire A Mebane Public Adjuster, And Is It Worth It?
We work on contingency, which means there is no upfront fee and no hourly billing. Our compensation is a percentage of the claim settlement, agreed to in writing before we start, under a contract that follows North Carolina Department of Insurance rules. If we don't recover money for you, you don't owe us a fee.
Is it worth it? For most substantial claims, yes — and the math usually makes that obvious. When a carrier's first offer misses damaged decking, matching requirements for siding, water mitigation, or the true cost of labor and materials in the Triangle-Triad corridor, the gap between their number and a complete estimate is often tens of thousands of dollars.
We're candid during the free initial review. If your claim is small or the insurer's offer is already fair, we'll tell you that and you'll owe nothing. Homeowners in Mebane call us most often after hail events, tree strikes, pipe bursts, and kitchen fires — the kinds of losses where damage hides behind finishes and first offers routinely fall short.
Before you sign anything, we'll walk you through the fee agreement, answer every question, and make sure the expected recovery justifies bringing us on.
When Should I Call A Claims Adjuster Of My Own After Storm Damage In Alamance County?
The short answer: as early as possible, ideally before you file the claim or immediately after. The first weeks of a claim set the tone for everything that follows — the damage scope, the estimate, and the carrier's reserve on your file.
Alamance County gets hit hard by spring hail, straight-line winds, and the remnants of tropical systems moving up from the coast. After a big storm rolls through Mebane, Graham, or Haw River, out-of-town roofers and carrier adjusters flood the area, and homeowners often accept quick inspections that miss real damage.
Calling us early means we inspect before temporary repairs disturb the evidence, before recorded statements lock you into a version of events, and before a lowball estimate becomes the baseline you have to fight against. We document interior staining, attic moisture, soft decking, and collateral damage on gutters and window screens — the details that prove a storm claim.
That said, it's never too late. If your claim is already open and stalling, or you've received an offer that won't cover a licensed local contractor's bid, we can step in mid-claim, re-inspect, and submit a supplemented estimate. Earlier is easier, but later still works.
My Claim Was Underpaid Or Denied — Can A Public Adjuster Mebane NC Residents Trust Still Help?
Yes. Reopening underpaid and wrongly denied claims is a large part of what a public adjuster Mebane NC property owners bring us for, and North Carolina policies generally allow supplemental claims well after the initial payment as long as you're within the policy's time limits.
Here's how it works. We start by pulling apart the carrier's estimate and denial letter against your actual policy language. Denials often lean on exclusions that don't apply — a "wear and tear" call on a roof that actually has fresh hail impact, or a "maintenance" label on sudden pipe failure.
Then we re-inspect the property ourselves. On Mebane homes we frequently find damage the original adjuster never scoped: saturated insulation above ceilings, cracked shingle mats, damaged HVAC fins, or interior repairs priced far below what Alamance County contractors actually charge.
From there, For The Public Adjusters, Inc. submits a documented supplement or a formal rebuttal to the denial, complete with photos, measurements, and code citations. If the carrier still won't move, we can invoke the appraisal clause in most policies, which forces an independent resolution process.
Bring us your estimate, denial letter, and policy — the review costs nothing, and you'll know quickly whether the claim has room to recover more.
What Types Of Property Damage Claims Does A Public Adjuster Mebane NC Property Owners Rely On Typically Handle?
For The Public Adjusters, Inc. handles the full range of property claims that hit Mebane homes and businesses. That includes fire and smoke damage, water damage from burst pipes or appliance failures, wind and hail damage to roofs and siding, storm and fallen-tree claims, and vandalism or theft losses.
In Alamance County, wind and hail claims are among the most common we see, especially after the spring and summer storm systems that roll through the Triad and Triangle corridor along I-40 and I-85. These claims are also where insurers most frequently underestimate damage, because hail bruising on shingles and hidden moisture behind siding are easy to miss on a quick inspection.
Water losses are another frequent call. Older homes near downtown Mebane and newer builds in developments off Mebane Oaks Road alike can suffer pipe failures, and the resulting damage often extends into wall cavities, insulation, and flooring layers that a surface-level estimate ignores.
We also represent commercial policyholders — restaurants, retail shops, and light industrial properties — where business interruption coverage adds another layer of complexity. If your loss involves lost income on top of physical damage, documentation standards get stricter and the stakes get higher.
If you are unsure whether your specific loss qualifies, call us and describe what happened. We review the damage and your policy language at no charge, and we will tell you honestly whether professional representation makes sense for your situation.
Are Public Adjusters Licensed In North Carolina, And How Do I Verify One Before Hiring?
Yes. North Carolina requires anyone who negotiates insurance claims on behalf of policyholders for a fee to hold a public adjuster license issued by the North Carolina Department of Insurance. Licensees must pass a state examination, carry a surety bond, and follow strict rules governing contracts and fees.
Before signing with anyone, verify their license through the NC Department of Insurance licensee lookup tool on the department's website. Search by name or license number — a legitimate adjuster will give you their license number without hesitation. If someone hedges or claims they "work under" another company's license without holding their own, walk away.
This matters in practice, not just on paper. After major storms, out-of-state operators sometimes canvass neighborhoods in Alamance County offering to "handle everything" for cash up front. North Carolina law prohibits public adjusters from charging fees before recovery, and it caps how contracts must be structured. An unlicensed operator leaves you with no recourse if things go wrong.
For The Public Adjusters, Inc. is fully licensed in North Carolina, and we encourage every prospective client to verify that before signing anything with us or anyone else. We will provide our license information at the first conversation.
A few other things worth checking: how long the firm has worked claims in this part of the state, whether they can reference recent settlements involving damage similar to yours, and whether their contract clearly spells out the contingency percentage with no hidden add-ons.
How Long Will My Insurance Claim Take If I Hire A Public Adjuster Mebane NC Clients Recommend?
Most residential claims we handle in Mebane resolve within 60 to 120 days from the date we take over, though timelines vary with the size of the loss and how cooperative the insurance carrier is. A straightforward roof claim after a hailstorm may settle in six to eight weeks. A major fire loss with structural damage, contents inventory, and additional living expenses can take four to six months or longer.
Here is the important part: hiring representation usually does not slow your claim down, and in many cases it speeds things up. Delays most often happen when documentation is incomplete or when the carrier disputes scope. We front-load the process — thorough inspection, detailed line-item estimates, photo documentation, and moisture readings where relevant — so the insurer has less room to stall with repeated information requests.
North Carolina also gives you leverage on timing. Insurers operating here are expected to acknowledge claims promptly and act in good faith on settlement. When a carrier drags its feet, we know how to apply pressure through documented follow-ups and, when necessary, formal complaints.
A public adjuster Mebane NC homeowners bring in early can also prevent the biggest time-killer of all: a lowball first offer that forces you into weeks of back-and-forth or a supplemental claim. Getting the scope right the first time is the fastest path to a fair check.
During our free initial review, we will give you a realistic timeline estimate based on your specific damage, your carrier, and what we have seen on similar Alamance County claims.
What's The Difference Between The Insurance Company's Adjuster And One I Hire Myself?
The adjuster your insurance company sends works for the insurance company. That is not a criticism — it is simply who signs their paycheck. Their job is to evaluate your claim within the carrier's guidelines, and those guidelines are built to control payout costs. Many are handling dozens of files at once and may spend twenty minutes at your property.
An adjuster you hire works exclusively for you, the policyholder. Our loyalty, our fee, and our license obligations all run to you and no one else. We read your policy for every coverage that applies — dwelling, other structures, contents, code upgrades, additional living expenses — not just the obvious line items.
The practical difference shows up in the details. A carrier adjuster might scope a hail claim as "repair 12 shingles." Our inspection might document mat fractures across the entire slope, damaged gutters and window screens, and dented HVAC fins, supporting full replacement instead of a patch. On a water loss, we test for moisture migration the carrier's estimate never accounted for.
You may also hear about "independent adjusters." Despite the name, they are contractors hired by insurance companies, not by you. Only a licensed representative retained by the policyholder actually advocates for your side.
For The Public Adjusters, Inc. built its reputation in Mebane and across Alamance County on exactly this difference: documenting the loss the way it deserves to be documented, then negotiating from evidence rather than accepting the carrier's first number.
What Should I Have Ready Before Meeting With A Public Adjuster Mebane NC Homeowners Can Call?
The most important thing to bring is a complete copy of your insurance policy, including the declarations page and any endorsements. If you can't find it, request one from your carrier — you're entitled to it, and we can't accurately evaluate your coverage without it.
Beyond the policy, gather anything that documents the loss. Photos and videos of the damage, a list of damaged or destroyed items, receipts for emergency repairs like tarping or water extraction, and any letters or emails from your insurance company all help. If the carrier has already sent an adjuster, bring their estimate and any payment breakdowns you've received.
Don't worry if your documentation feels thin. Many Mebane homeowners call us within days of a storm or fire, before they've had time to organize anything. Part of our job at For The Public Adjusters, Inc. is building that documentation properly — photographing the property, measuring rooms, cataloging contents, and pulling weather records for Alamance County if the date of loss is in question.
One caution: hold off on throwing anything away or making permanent repairs before the damage is fully documented. Your policy requires you to prevent further damage, so temporary fixes are fine, but discarding damaged materials too early can weaken your claim. If you're unsure whether something should stay or go, take detailed photos first and ask us before disposing of it.
Will Hiring My Own Adjuster Cause My Insurer To Raise My Rates Or Drop My Policy?
No. Hiring your own licensed representative does not affect your premiums or your standing with your insurance company. Rates in North Carolina are driven by factors like your claims history, the type and frequency of losses, regional risk, and statewide rate filings — not by who represents you during a claim.
Filing the claim itself is what appears in your claims history, and that happens whether you handle it alone or with professional help. In fact, working with an experienced advocate often results in a cleaner, better-documented file, which reduces disputes and back-and-forth with the carrier.
Some Mebane homeowners worry that pushing back on a low settlement will get them flagged as a difficult policyholder. That fear is understandable but misplaced. You have a contractual right to be paid what your policy owes, and North Carolina law explicitly allows you to hire licensed representation. Insurers deal with public adjusters every day; it's a normal part of the claims process, not an adversarial red flag.
What can genuinely hurt you is an underpaid claim that leaves repairs unfinished. Incomplete storm or water damage repairs can lead to secondary problems — mold, rot, structural issues — that may be denied later as neglect or pre-existing damage. Recovering the full amount the first time protects both your home and your future insurability far more than quietly accepting a low check ever will.
Is There A Deadline To File Or Reopen A Property Insurance Claim In North Carolina?
Yes, and it's one of the most common reasons Alamance County property owners lose money they were owed. North Carolina generally gives you three years from the date of loss to bring a claim under a property insurance policy, but your individual policy may impose shorter contractual deadlines for filing suit or submitting proof of loss — some as short as one or two years. Always check your specific policy language.
Separate from legal deadlines, most policies require "prompt" notice of a loss. Waiting months to report hail damage or a slow roof leak gives the carrier an opening to argue the damage worsened due to delay. Reporting quickly, even if you're still assessing the full scope, protects your position.
Reopening a claim is different from filing a new one. If you were paid on a claim and later discover the settlement missed damage — say, a roofer finds decking damage the original inspection skipped — you can typically submit a supplemental claim, provided you're within the applicable time limits. We handle supplements regularly for Mebane homeowners whose original payouts covered shingles but ignored underlayment, flashing, gutters, or interior water staining.
If you're anywhere near a deadline, don't wait. A public adjuster Mebane NC property owners bring in early has time to document thoroughly, but even late in the window, a fast professional review can determine whether a supplement or dispute is still viable. A short phone call costs nothing and can preserve rights you didn't know you had.
Can I Bring In Help If My Claim Is Already Open Or I've Received A Partial Payment?
Absolutely, and this is actually one of the most common situations we handle in Mebane. You can hire your own licensed adjuster at any stage of a claim — before filing, mid-negotiation, after receiving an estimate, or even after depositing a check you believe was too low.
A partial or initial payment does not close your claim in most cases. Insurance settlements in North Carolina are frequently paid in stages: an initial actual-cash-value payment, then recoverable depreciation after repairs, plus supplements for damage found during the work. Cashing an early check rarely waives your right to pursue the full amount, though you should never sign a release or final settlement agreement without having it reviewed first.
When we take over an open claim, we start by comparing the carrier's estimate against the actual damage. Around Alamance County we routinely find missed items: matching issues on roofing and siding, code-upgrade costs that older Mebane homes trigger during repairs, contents losses that were never inventoried, and additional living expenses homeowners didn't know they could claim.
From there, we prepare our own detailed estimate, submit the supplemental documentation, and negotiate directly with the carrier's adjuster so you're not stuck making those calls yourself. If your claim feels stalled, or the numbers simply don't cover what your contractor says the repairs will cost, that gap is exactly the signal that a professional second look is worth your time. Reviews of already-paid claims are how many of our clients first find us.
What Happens During The First Property Inspection With A Public Adjuster Mebane NC Residents Hire?
The first visit is a top-to-bottom documentation of your loss, and it usually takes one to three hours depending on the size of the damage. Our adjuster walks the entire property — not just the obvious problem areas — because storm, fire, and water damage in Mebane homes often extends into attics, crawl spaces, and wall cavities where carriers rarely look.
We photograph and measure everything, pull moisture readings where water is involved, and note code-related items that older Alamance County homes frequently trigger, like outdated wiring or framing that must be brought up to current standards during repairs. Those code upgrades are covered under many policies but almost never volunteered by the insurance company.
We also review your policy on the spot. Deductibles, endorsements, matching provisions, and ordinance-and-law coverage all shape what your claim is actually worth, and most homeowners have never had those sections explained in plain English.
By the end of the inspection you'll know three things: what damage we found, what your policy likely covers, and what the realistic path forward looks like. There's no obligation at that point. If the claim is small enough that you're better off handling it yourself, we'll tell you that honestly — a public adjuster Mebane NC property owners can trust should never take a file just to take it. Bring your policy declarations page, any correspondence from your carrier, and photos from before the loss if you have them, and the inspection will move even faster.
Do You Handle Commercial And Business Property Claims In Mebane, Or Only Residential Homes?
We handle both. Mebane's growth along the I-40/85 corridor means the area has a real mix of commercial property — warehouses and distribution space near the interstate, retail and restaurants downtown, medical and professional offices, and light industrial buildings — and commercial claims are frequently where owners lose the most money without representation.
Commercial policies are more complicated than homeowners policies. Coinsurance penalties, business income and extra expense coverage, tenant improvements, and equipment breakdown provisions all interact in ways that can dramatically raise or lower a settlement. A roof claim on a 40,000-square-foot warehouse isn't just a roofing estimate; it may involve business interruption during repairs, inventory protection, and code compliance across the entire structure.
For business owners, the biggest hidden loss is usually time. Every week spent arguing with a carrier is a week you're not running your company. We take over the documentation, the meetings with the insurer's adjusters and engineers, and the negotiation, so operations can continue.
We also represent landlords and property managers with multi-tenant buildings in Mebane and throughout Alamance County, where a single hail event can generate claims across several structures at once. If you own or manage commercial property and your carrier's number doesn't reflect the true cost to restore the building and the income it produces, that gap is exactly what a Mebane public adjuster is licensed to close on your behalf.
What Is The Appraisal Clause In My Policy, And Can My Own Adjuster Help Me Use It?
Most North Carolina property policies contain an appraisal clause — a built-in method for resolving disputes about the amount of a loss without going to court. If you and your insurer agree the damage is covered but disagree on what it costs to repair, either side can demand appraisal.
Here's how it works. You select an appraiser, the insurance company selects its own, and the two appraisers choose a neutral umpire. The appraisers each present their valuation, and when any two of the three agree, that figure becomes binding on the amount of loss. It's typically faster and far cheaper than litigation.
Appraisal is one of the most powerful tools available to a public adjuster Mebane NC policyholders bring in on disputed claims, because carriers know an underpriced estimate won't survive scrutiny in front of an umpire. Simply invoking the clause with well-documented figures often prompts a carrier to return to the table with a better offer before the process finishes.
That said, appraisal only resolves the dollar amount — it doesn't settle coverage disputes, so timing and strategy matter. Demanding it too early, before the damage is fully documented, can lock in a weak position. We evaluate whether your file is ready, prepare the detailed estimate and evidence an appraiser needs, and can serve in or coordinate the appraisal role depending on the situation. For underpaid roof, hail, and water claims in Alamance County, appraisal is frequently where the real settlement gets decided.
Can A Mebane Public Adjuster Help With Living Expenses And My Damaged Personal Belongings, Not Just The Building?
Yes, and these two categories are where homeowners commonly leave the most money unclaimed. Your policy isn't limited to the structure. Most Mebane homeowners policies include Additional Living Expenses (ALE) coverage and personal property (contents) coverage, and both require documentation the carrier will not build for you.
ALE pays the extra costs of living elsewhere while your home is unlivable after a fire, major water loss, or storm damage — a rental or extended-stay hotel, increased mileage if you're temporarily farther from work in Burlington or the Triangle, restaurant meals beyond your normal grocery budget, even pet boarding. Carriers often approve a short hotel stay and quietly stop there. We track every legitimate expense and push for ALE that lasts as long as the actual repairs do, not as long as the insurer prefers.
Contents claims are their own project. After a fire or flooding, you're expected to produce a room-by-room inventory with quantities, ages, and replacement values — often hundreds of line items — while you're displaced and stressed. We build that inventory with you, photograph and value the items properly, and make sure the difference between actual cash value and replacement cost is handled correctly so you recover depreciation you're owed.
Many families accept a lump-sum contents offer that's a fraction of what a documented inventory would support. If you're staring at a house full of smoke-damaged or waterlogged belongings anywhere in Alamance County, get help before you sign off on the carrier's number.
Local Relevance
Mebane sits in the North Carolina Piedmont, where a humid subtropical climate delivers heavy summer thunderstorms, winter ice events, and the occasional remnants of hurricanes tracking inland from the coast. Those tropical remnants and severe storms are behind many of the tree damage and roof-related claims we see across Alamance County — mature hardwoods coming down on rooflines is a recurring story here.
The housing stock is a real mix. Mebane's older neighborhoods include early-twentieth-century homes from its furniture-town era, while rapid growth along the I-40/85 corridor has added waves of newer subdivisions. Older homes bring aging plumbing, older wiring, and construction details insurers scrutinize hard on fire and water claims; newer homes bring builder-grade materials and code-upgrade questions when repairs begin.
For flood losses, coverage typically comes through a separate flood policy rather than the homeowners policy, and National Flood Insurance Program (NFIP) claims follow their own strict documentation rules and deadlines — a proof of loss must be filed on time, and low-lying properties near local creeks are the ones most often caught off guard. We handle NFIP flood claims alongside standard homeowners and commercial claims, so Mebane policyholders don't have to learn two claim systems at once.
Many of Mebane's established neighborhoods sit under mature oaks and other large hardwoods, and the Piedmont's saturated-soil summer storms and winter ice loading tend to bring those trees down onto roofs and vehicles' worth of structure below — so tree damage claims here often involve hidden framing and truss damage that a quick carrier inspection can miss. Insist on a full structural documentation of the roof system, not just the visible shingle damage, before any tree claim is settled.
Talk To A Licensed Adjuster On Your Side
Whether it's fire, water, smoke, a fallen tree, or a flood loss, For The Public Adjusters, Inc. reviews your policy and your damage at no cost and no obligation. We're licensed, bonded, and we only get paid when your claim does. Serving Mebane and all of Alamance County.
Call us: (336) 331-8300
Helpful Resources
- NCDOI Public Adjusters Guide
- National Flood Insurance Program (NFIP)
- Federal Emergency Management Agency (FEMA)
- North Carolina Department of Insurance consumer resources — State regulator overseeing insurance and public adjuster licensing in NC
Our services in this city
- Fire Insurance Claim Mebane NC: Help After House Fires, Smoke Damage & Firefighting Water Loss
- Insurance Dispute Lawyers Mebane: Why A Public Adjuster Should Be Your First Call — Not A Law Firm
Last updated: August 5, 2026