
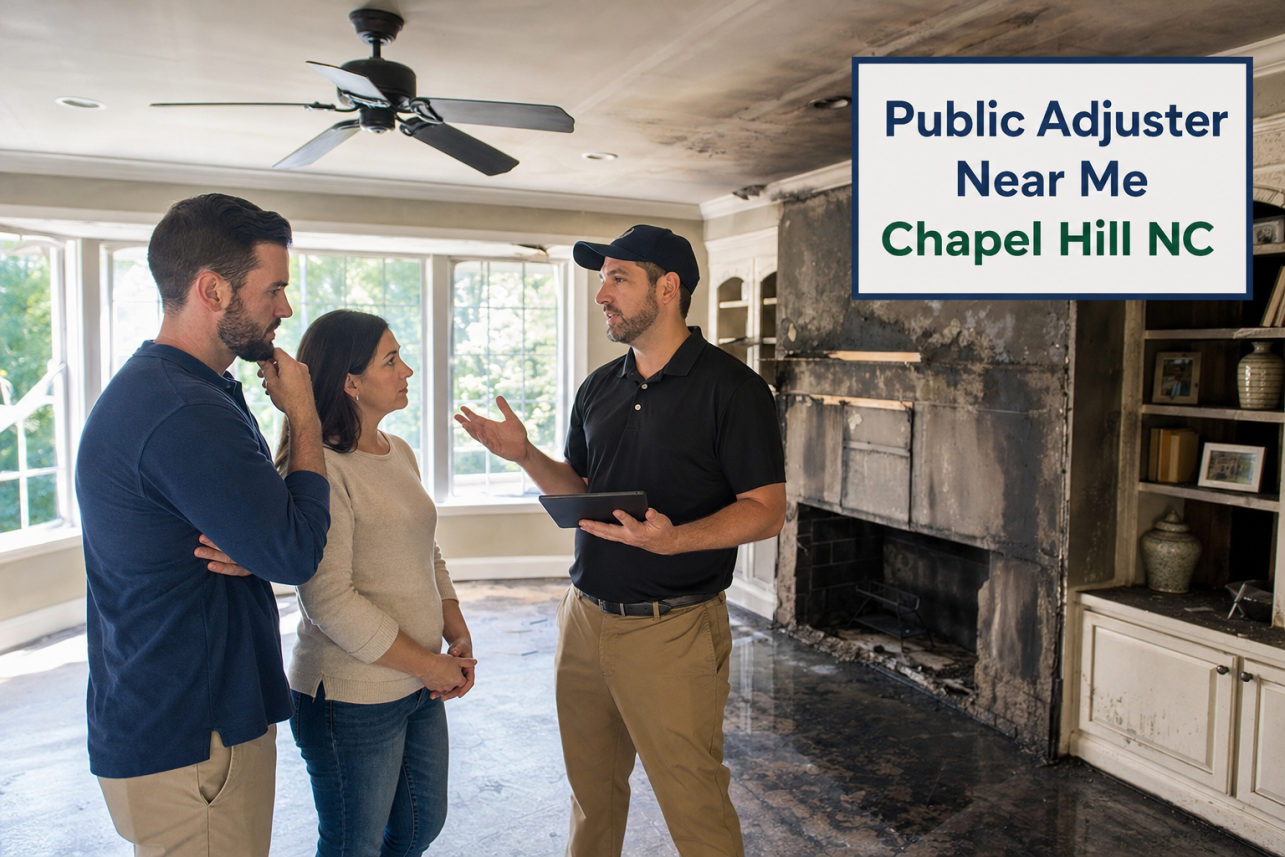
If you are searching for a Public Adjuster Near Me Chapel Hill NC, For The Public Adjusters, Inc. represents homeowners and business owners in Orange County — not the insurance company. We are licensed and bonded, and we document, value, and negotiate fire, smoke, water, tree, and flood damage claims on your behalf. The initial claim review is free, and we only get paid when your claim does.
What This Service Is
A public adjuster is the only type of insurance adjuster licensed to work for the policyholder. The adjuster your insurance company sends works for the carrier; an independent adjuster is hired by the carrier. We sit on your side of the table.
In practice, that means we read your policy line by line, inspect and photograph the damage, write a detailed estimate using the same pricing software carriers use, and handle every call, email, and inspection until the claim is resolved. You never have to argue scope or pricing with the company alone.
We handle residential and commercial property claims: fire and smoke, water and flood, tree strikes, vandalism, arson defense for innocent homeowners, and car-hits-home losses. We do not handle auto, health, life, or cell phone claims. For example, a tree damage insurance claim help in Carrboro file often involves roof structure, interior water intrusion, fencing, and tree removal costs the first estimate never included.
The NCDOI Public Adjusters Guide explains how public adjusters are licensed and regulated in North Carolina, and we encourage every homeowner to read it before hiring anyone — including us.
Common Problems
Is A "Free Public Adjuster Near Me" Actually Free — And What Does Hiring One Really Cost?
The claim review is genuinely free. We look at your policy, your damage, and the carrier's estimate at no charge and tell you honestly whether representation makes sense.
If you hire us, we work on a contingency percentage of the claim recovery, capped by North Carolina rules. There is no hourly billing and no upfront fee. If the claim pays nothing, we earn nothing.
We never guarantee a specific dollar outcome — no honest adjuster can. What we can promise is a complete, properly documented claim that includes items carriers routinely leave out: code upgrades, matching materials, contents, smoke cleaning, and additional living expenses.
Public Adjuster Near Me Chapel Hill NC: What If My Claim Is Delayed, Underpaid, Or Denied?
Delays and lowball first offers are the most common problems we see in Chapel Hill. The carrier's estimate often covers patching when the policy actually owes for full replacement, or blames "wear and tear" on storm damage.
A denial is not the end. Courts have repeatedly sided with policyholders on these disputes — in Sebo v. American Home Assurance Co., the Florida Supreme Court ruled for a homeowner whose house suffered water damage from multiple combined causes, rejecting the insurer's attempt to deny the loss because an excluded cause contributed to it.
We reopen underpaid claims, file supplements, and invoke appraisal when needed. A fire insurance claim dispute in Pittsboro we handled turned on exactly this kind of documentation gap — the loss was real, but nobody had proved it on paper yet.
How Do I Choose Among The Insurance Adjusters Near Me — And Can I Just Handle It Myself?
You can file a claim yourself, and for small, clean losses you probably should. Hire a public claims adjuster when the damage is significant, the policy language is contested, or the carrier's number does not come close to real repair costs.
Verify three things before signing with anyone: a current North Carolina public adjuster license, a written contingency fee stated as a percentage, and a bond. We carry all three and will show them to you.
A good adjuster also knows local repair pricing. Chapel Hill contractors, older-home materials, and matching discontinued brick or siding all price differently than a software default — and that local knowledge is often where the underpayment hides.

Our Process
Free Policy And Damage Review
We start by reading your actual policy — coverages, endorsements, exclusions, and deadlines — then inspect the damage in person. You get a straight answer about whether your claim is worth pursuing with representation. If it is not, we tell you that for free.
Full Documentation And Valuation
We photograph everything, moisture-map water losses, inventory contents room by room, and build a line-item estimate. Hidden damage drives most underpayments: wet insulation behind walls, smoke residue in ductwork, cracked framing under a tree strike. A water damage claim help in Bynum file we built nearly doubled in documented scope once the walls were opened.
Negotiation Through To Settlement
We present the claim to your carrier, attend every re-inspection, answer every pushback in writing, and negotiate until the settlement reflects the documented loss. If the gap cannot be closed, we pursue appraisal or coordinate with insurance dispute attorneys. You stay informed at every step without having to fight the fight yourself.
| What's Involved | Handling It Yourself | With For The Public Adjusters, Inc. |
|---|---|---|
| Damage documentation | Phone photos and the carrier's one-time inspection | Moisture mapping, itemized room-by-room inventories, specialist and engineer reports when warranted |
| Estimate review | Accepting the carrier's scope or guessing at what's missing | Line-by-line comparison against contractor pricing and your actual policy language |
| Policy interpretation | Reading dense policy forms alone | A licensed, bonded adjuster who identifies coverages like additional living expenses, code upgrades, and contents you may not know apply |
| Negotiation | Calls and emails with a trained claims examiner, on their terms | Documented supplemental claims and direct negotiation handled for you |
| Who they represent | The carrier's adjuster works for the insurance company | We work exclusively for you, the policyholder — never the insurer |
| Legal awareness | Most homeowners never learn their rights | We know North Carolina precedent — like Guessford v. Pennsylvania National, where a homeowner's bad-faith claims over an underpaid property loss moved forward in federal court |
Commonly Overlooked In The Public Adjusting Industry
- Additional living expenses (ALE) coverage — Carriers rarely volunteer that your policy pays for hotels, meals, and temporary housing while your home is uninhabitable, so most policyholders never claim it.
- Ordinance and law (code upgrade) coverage — Chapel Hill and Orange County building codes have changed since older homes were built, and rebuilding to current code costs more than the carrier's like-for-like estimate includes.
- Hidden moisture in wall cavities and subfloors — Carrier adjusters typically scope only what's visible, and saturation behind walls quietly becomes a mold problem months after the claim is closed.
- Smoke and soot contamination in HVAC ductwork — Ducts carry soot to every room in the house, but duct cleaning almost never appears on a first estimate because nobody tested for it.
- Itemized contents inventories instead of lump sums — A quick walkthrough lump sum feels generous in the moment, but it routinely misses a third or more of what a 400-line inventory would capture.
- Matching requirements for continuous materials — Spot-repairing one section of flooring, siding, or roofing leaves an obvious mismatch, and many policies owe for continuous runs — a detail first estimates conveniently skip.
- Supplemental claims after the first check — Policyholders assume the first payment is final, but North Carolina claims can be supplemented when documented damage was missed or underpaid.
- The flood versus homeowner's policy line — Rising water is an NFIP matter while a burst pipe is a homeowner's claim, and misfiling with the wrong policy can delay or sink an otherwise valid claim — FEMA and FloodSmart.gov are the right starting points for flood losses.
Case Studies
Case Study #1
Situation: A family in the historic Franklin-Rosemary district of Chapel Hill owned a 1920s craftsman home with original heart-pine floors and plaster walls. During a January freeze, a supply line in the upstairs bathroom burst overnight, sending water through two floors and into the kitchen below.
Problem: The insurance company's adjuster spent under an hour on site and issued an estimate that priced the plaster repairs as standard drywall and offered to refinish only the visibly stained sections of flooring. The offer did not come close to covering like-kind restoration in a home subject to Chapel Hill historic district guidelines.
Investigation: Our team brought in a moisture-mapping specialist and documented saturation readings inside wall cavities the carrier never opened. We photographed cupping across continuous floor runs, pulled the town's historic district standards, and obtained a plaster restoration quote from a craftsman experienced with homes of that era.
Findings: Moisture had wicked well beyond the visible stains, meaning spot refinishing would leave mismatched flooring across connected rooms. The policy's like-kind-and-quality language supported true plaster repair, not drywall substitution, and hidden framing moisture created a documented mold risk the first estimate ignored.
Solution: We prepared a line-by-line counter-estimate with the moisture data, restoration quotes, and the applicable policy language, then negotiated directly with the carrier's examiner. We also pointed to Guessford v. Pennsylvania National Mutual Casualty Insurance Co., 983 F. Supp. 2d 652 (M.D.N.C. 2013), a North Carolina federal case where a homeowner's bad-faith and unfair-practices claims against an insurer that lowballed a property damage claim were allowed to proceed — a reminder that carriers in this state are expected to evaluate claims fairly.
Outcome: The carrier reissued the estimate to include full plaster restoration, continuous-run floor refinishing, and proper drying and remediation of the concealed cavities. The revised settlement was several times the original offer, and the family restored the home to its pre-loss character.
Lesson: In older Chapel Hill homes, the first estimate often prices modern materials for historic construction. Documenting what the policy actually owes — like kind and quality — changes the entire conversation.
Case Study #2
Situation: A couple in Southern Village experienced a kitchen fire in their townhome when a range-top grease flare spread to the cabinets. The fire was extinguished quickly, but smoke traveled through the HVAC system into every room, including closets full of clothing and a home office with books and electronics.
Problem: The carrier's adjuster scoped the kitchen itself reasonably but treated the rest of the home as a light cleaning job. The contents offer was a lump sum based on a quick walkthrough, with no itemized inventory, and it excluded dozens of smoke-affected belongings the homeowners assumed were covered.
Investigation: We performed a room-by-room contents inventory — over 400 line items with photos, ages, and replacement pricing. We had the HVAC system inspected for soot contamination and brought in an industrial hygienist to test for smoke residue in bedrooms the carrier had labeled unaffected.
Findings: Soot residue was present on surfaces two floors from the kitchen, and the ductwork tested positive for contamination, meaning the system needed professional cleaning rather than a filter change. Roughly a third of the contents value was missing from the carrier's lump-sum figure, and the homeowners were also owed additional living expenses for the time the home was uninhabitable during remediation.
Solution: We submitted the full inventory, the hygienist's report, and the HVAC findings as a supplemental claim and walked the carrier's examiner through each category. We kept the homeowners out of the back-and-forth entirely so they could focus on their family.
Outcome: The settlement grew substantially from the initial offer, adding the duct cleaning, whole-home smoke remediation, the itemized contents, and additional living expenses the carrier had never mentioned. The homeowners were back in a fully cleaned home rather than one that still smelled like smoke a year later.
Lesson: Smoke doesn't stop at the room where the fire burned. A lump-sum contents offer without an itemized inventory is almost always an undercount — and policyholders rarely know additional living expense coverage exists until someone shows them.
| Your Claim Situation | Can You Likely Handle It Alone? | What It Depends On |
|---|---|---|
| Small, visible water leak with damage under your deductible range | Often yes | Whether moisture readings confirm the damage truly stops where you can see it — hidden saturation changes everything |
| Burst pipe affecting multiple rooms or floors | Risky | Carriers frequently scope only visible staining; wall cavities, subfloors, and continuous flooring runs are where underpayment hides |
| Kitchen or electrical fire with any smoke odor beyond the fire room | No — get help | Smoke migrates through HVAC systems; lump-sum contents offers without itemized inventories almost always undercount |
| Tree or structural damage from a hurricane remnant or tornado | No — get help | Structural scope requires engineering documentation; a surface patch estimate can leave cracked framing unaddressed |
| Flood damage from rising water | Separate process | Flood losses go through the NFIP, not your homeowner's policy — start at FEMA.gov and FloodSmart.gov, and we can help you understand how flood and homeowner coverages interact |
| Carrier denied your claim outright | No — get help | Denials often rest on contested policy interpretation; North Carolina courts, as in Guessford v. Pennsylvania National, have let homeowners pursue insurers over wrongful claim handling |
| Carrier's offer feels low but you can't say why | Get a review first | A policyholder-side review of the estimate against your policy costs you nothing to ask about and reveals exactly what's missing |
| Damage to a historic-district home | No — get help | Chapel Hill historic guidelines require like-kind materials; standard estimates price modern substitutes that violate both the guidelines and your policy's restoration language |
Reviews
After a pipe burst in our 1930s home near campus, the insurance estimate treated our plaster walls like drywall. For The Public Adjusters re-documented everything, found moisture the first adjuster missed, and the final settlement actually covered restoring the house properly. I only wish I'd called them before accepting the carrier's first inspection.
Margaret H., Gimghoul neighborhood
Our kitchen fire claim seemed simple until the smoke damage offer came in. These adjusters built a 400-item contents inventory, got our ductwork tested, and handled every call with the insurance company. We ended up with a settlement that covered things we didn't even know were claimable, like our hotel stay during remediation.
David R., Meadowmont
A tornado-warned storm dropped a large oak limb through our roof and the carrier wanted to patch a section instead of addressing the structural damage underneath. For The Public Adjusters brought in an engineer, documented the cracked rafters, and negotiated a proper repair scope. Professional, responsive, and they explained every step in plain English.
Priya S., near Estes Hills
Frequently Asked Questions
What Does A Public Adjuster Near Me Chapel Hill NC Actually Do For Homeowners?
When you search for a Public Adjuster Near Me Chapel Hill NC, you're looking for a licensed professional who works exclusively for you, the policyholder — never the insurance company. For The Public Adjusters, Inc. documents your property damage, reads your policy line by line, prepares a detailed estimate, and negotiates directly with your insurer on your behalf.
The insurance company's adjuster is paid by the carrier. We are licensed and bonded, and our only client is you. That distinction matters when a fire, hurricane, tornado, hail, or water loss damages your home in Chapel Hill or anywhere in Orange County.
North Carolina courts have long recognized that policyholders deserve a fair reading of their coverage. In Gaston County Dyeing Machine Co. v. Northfield Insurance Co., 351 N.C. 293 (2000), the North Carolina Supreme Court sided with the insured in a property damage dispute, holding that ambiguous policy language must be construed in favor of the policyholder. That principle guides how we press carriers to honor the full scope of your policy.
We handle claims involving homes, commercial buildings, and contents. We do not handle claims involving cell phones, motor vehicles, health, or life insurance. And while no adjuster can promise a specific outcome, having a trained advocate reviewing every line item means nothing in your claim gets overlooked.
When Should I Hire A Public Adjuster In Chapel Hill Instead Of Handling The Claim Myself?
The best time to bring in a Chapel Hill public adjuster is before you accept the insurance company's first offer — ideally right after the loss occurs. Early involvement lets us document damage before repairs begin, which is critical for fire losses, burst pipes, roof damage from hurricanes or tornadoes, and hail events that hit Orange County neighborhoods.
You should strongly consider professional help if the carrier's estimate seems low, if your claim has been delayed or partially denied, or if the damage is complex — think smoke contamination throughout a home, hidden water intrusion behind walls, or structural issues in an older Chapel Hill property near Franklin Street or in Southern Village.
Policyholders who stand their ground often prevail. In Gaston County Dyeing Machine Co. v. Northfield Insurance Co., the North Carolina Supreme Court ruled for the insured in a dispute over property damage coverage, confirming that carriers cannot lean on ambiguous policy wording to shrink a payout. Our job is to apply that same scrutiny to your claim from day one.
If your loss involves flooding, keep in mind that flood damage is typically covered under a separate policy through the National Flood Insurance Program (NFIP), administered by FEMA. We can help you understand how your flood and homeowners policies interact, and resources at FEMA.gov and FloodSmart.gov are worth reviewing as well. We are licensed and bonded, and we never promise a specific dollar outcome — only a thorough, professional fight for what your policy owes.
How Much Does It Cost To Hire For The Public Adjusters, Inc. In Orange County?
Our team works on a contingency fee basis, which means we are paid a percentage of the insurance settlement — not an hourly rate or upfront retainer. If your claim doesn't pay, our fee structure reflects that. This keeps our interests aligned with yours: we only do well when your claim is handled properly.
For homeowners in Chapel Hill, Carrboro, Hillsborough, and the rest of Orange County, this means you can get professional representation on a fire, hurricane, tornado, hail, or water damage claim without writing a check out of pocket at the start. The exact percentage is spelled out in a written agreement before we begin, with no hidden charges.
It's fair to ask whether the fee is worth it. Carriers often rely on their own estimates, and policyholders without representation rarely know what to challenge. North Carolina case law — including the state Supreme Court's decision in Gaston County Dyeing Machine Co. v. Northfield Insurance Co., where the insured won a property damage coverage dispute — shows that insurers' narrow readings of a policy don't always hold up. We bring that same adversarial review to your estimate and your policy language.
To be clear: we are licensed and bonded, and we never guarantee a particular settlement amount. Every claim is different. What we do promise is a complete, documented, professionally argued claim. We handle losses to homes, buildings, and contents only — not cell phones, motor vehicles, health, or life insurance claims.
Can A Public Adjuster Near Me Chapel Hill NC Help With Hurricane, Fire, And Flood Claims?
Yes. Searching for a Public Adjuster Near Me Chapel Hill NC usually starts after a major loss, and those are exactly the claims we handle. For The Public Adjusters, Inc. represents Orange County policyholders on hurricane and tornado damage, fire and smoke losses, hail damage, burst pipes, and other covered damage to homes, commercial buildings, and personal contents.
Hurricanes in particular cause complicated claims this far inland. When remnants of a storm push through Chapel Hill, you may face roof damage, water intrusion, fallen trees on structures, and extended power outages that spoil contents — each needing separate documentation under different policy provisions.
Flood losses work differently. Rising water is generally excluded from standard homeowners policies and covered instead by a separate flood policy, most often through the National Flood Insurance Program (NFIP) under FEMA. If your Chapel Hill property took on floodwater, we recommend reviewing FEMA.gov and FloodSmart.gov while we help you sort out which policy responds to which portion of the damage.
When carriers resist, the law can favor the policyholder. In Gaston County Dyeing Machine Co. v. Northfield Insurance Co., 351 N.C. 293 (2000), North Carolina's highest court ruled for the insured in a property damage coverage fight, construing unclear policy terms against the insurance company that drafted them. We are licensed and bonded, we make no guarantees about settlement amounts, and we do not handle cell phone, motor vehicle, health, or life insurance claims — but for building and contents losses, we're built for exactly this work.
How Long Does The Claim Process Take When I Search For A Public Adjuster Near Me Chapel Hill NC?
Every claim is different, but most Chapel Hill property claims we manage resolve within 60 to 120 days from the date we are retained. Straightforward kitchen fires or burst-pipe losses often settle faster, while large structural losses, hurricane damage, or disputed claims can take longer.
When you hire a Public Adjuster Near Me Chapel Hill NC through For The Public Adjusters, Inc., the first week is spent inspecting the property, photographing damage, reviewing your policy, and building a detailed estimate. From there, we submit documentation to the insurance company and handle every phone call, email, and site meeting on your behalf.
North Carolina law gives insurers specific timeframes to acknowledge, investigate, and pay claims, and we hold them to those deadlines. Delays usually happen when carriers request repeated inspections or dispute scope and pricing. Because we prepare a complete, itemized claim package up front, there are fewer reasons for the insurer to stall.
It is worth remembering that North Carolina courts have backed policyholders who push back on coverage disputes. In Gaston County Dyeing Machine Co. v. Northfield Insurance Co., 351 N.C. 293 (2000), the North Carolina Supreme Court ruled in favor of the insured on a property damage coverage question, confirming that carriers cannot read coverage more narrowly than the policy language allows. We cannot promise a specific timeline or outcome, but thorough documentation and persistent follow-up are the two factors that most reliably keep an Orange County claim moving.
My Insurance Company Already Denied Or Underpaid My Claim. Can Your Chapel Hill Team Still Help?
Yes. A denial or low settlement offer is not necessarily the end of your claim. For The Public Adjusters, Inc. regularly reviews closed, denied, and underpaid claims for homeowners and business owners throughout Chapel Hill and Orange County.
We start by reading your full policy and the insurer's denial or settlement letter line by line. Many denials rest on a single adjuster's interpretation of policy language, an incomplete inspection, or missing documentation. We then re-inspect the property, document damage the carrier's adjuster may have overlooked, and prepare a supplemental or re-opened claim supported by photos, measurements, and line-item pricing.
North Carolina generally allows policyholders time after a loss to pursue payment, though your specific policy sets contractual deadlines, so acting quickly matters. Courts in this state have sided with insureds when carriers construe coverage too narrowly. The Gaston County Dyeing Machine decision from the North Carolina Supreme Court is a well-known example where the insured prevailed on a building and equipment damage dispute.
We are licensed and bonded in North Carolina, and we work on your behalf, not the insurance company's. We cannot guarantee that a denied claim will be reversed or that a settlement will increase, because every policy and loss is unique. What we can promise is an honest assessment: if we review your file and believe the carrier paid fairly, we will tell you that too. There is no obligation to have us take a look at a closed Chapel Hill claim.
What Should I Do Right After Fire Or Water Damage To My Chapel Hill Home, Before An Adjuster Arrives?
First, make sure everyone is safe and the property is secure. Then take reasonable steps to prevent further damage, because your policy requires it. That might mean shutting off the water main after a pipe burst, tarping a roof opened by a fallen tree, or boarding broken windows after a fire. Keep every receipt for emergency work.
Second, document everything before anything is cleaned, moved, or thrown away. Photograph and video each room, including inside cabinets and closets. Damaged contents matter: smoke-saturated furniture, soaked rugs, and ruined clothing all have value under most homeowner policies. Do not discard damaged items until they have been inventoried and photographed.
Third, be careful what you say when you report the loss. Stick to the facts of what happened and when. Avoid guessing at causes or estimating costs on the phone, because early statements get recorded in the claim file.
If your loss involves flooding, know that standard homeowner policies in Chapel Hill typically exclude rising water. Flood coverage usually comes through the National Flood Insurance Program, and resources at fema.gov and floodsmart.gov explain how NFIP claims work. We can help you navigate a flood claim alongside any covered damage under your homeowner policy.
Finally, call For The Public Adjusters, Inc. before the insurance company's adjuster inspects, if possible. Having your own licensed representative present at that first inspection helps ensure nothing is missed and the scope of damage is recorded accurately from day one.

What Types Of Claims Does A Public Adjuster Near Me Chapel Hill NC Handle, And Are There Claims You Don't Take?
For The Public Adjusters, Inc. handles property damage claims for homes, commercial buildings, and the contents inside them. In Chapel Hill and across Orange County, the most common losses we manage are house fires, smoke damage, lightning strikes, burst and frozen pipes, water damage from appliance and plumbing failures, hurricane damage, tornado damage, hail, fallen trees, theft, and vandalism.
We also assist with flood claims filed through the National Flood Insurance Program. Because NFIP policies have their own rules and deadlines that differ from standard homeowner coverage, it helps to have an experienced advocate preparing the documentation. FEMA's site at fema.gov is a useful starting point for understanding flood claim requirements.
There are claims we do not handle. We do not represent policyholders on cell phone, motor vehicle, health, or life insurance claims. Our work is strictly limited to damage involving buildings, structures, and personal or business contents.
If you are typing Public Adjuster Near Me Chapel Hill NC into a search engine, you are likely dealing with a significant loss and an unfamiliar claims process. We are licensed and bonded in North Carolina, and we represent only you, never the insurance company. North Carolina courts have shown that policyholders who document and press their claims can prevail; the state Supreme Court's ruling for the insured in Gaston County Dyeing Machine Co. v. Northfield Insurance Co. is one example involving physical damage coverage. While no one can guarantee a particular result, we make sure your Orange County claim is presented completely, accurately, and on time.
Is For The Public Adjusters, Inc. Licensed And Bonded To Work As A Public Adjuster Near Me Chapel Hill NC?
Yes. When homeowners search for a Public Adjuster Near Me Chapel Hill NC, licensing should be the first thing they verify, and we welcome that scrutiny. For The Public Adjusters, Inc. is fully licensed and bonded in North Carolina, which means we meet the state's examination, background, and continuing-education requirements set by the North Carolina Department of Insurance.
The bond matters just as much as the license. It exists to protect you, the policyholder, and it signals that we operate under real financial accountability rather than empty promises. You can confirm any adjuster's license status directly through the Department of Insurance before signing anything, and we encourage every Orange County homeowner to do exactly that.
Why does this matter locally? Chapel Hill sees everything from aging plumbing failures in historic Franklin Street-area homes to hurricane remnants pushing heavy rain through Orange County. After a major storm, out-of-state operators sometimes canvass neighborhoods offering to 'handle' claims without proper credentials. Working with an unlicensed representative can jeopardize your claim and leave you with no recourse if something goes wrong.
When you hire our team, you get a credentialed professional who documents your fire, water, or storm damage, interprets your policy, and negotiates with the carrier on your behalf. We never guarantee a specific dollar outcome — no honest adjuster can — but we do guarantee that a licensed, bonded professional is advocating for your interests at every stage of the claim.
Does North Carolina Law Actually Favor Homeowners When Policy Language Is Unclear?
In many situations, yes — and this is one of the most important tools a Chapel Hill public adjuster brings to the table. North Carolina courts have repeatedly held that when an insurance policy contains ambiguous language, that ambiguity must be construed in favor of the insured, not the insurance company that drafted the contract.
A leading example is Gaston County Dyeing Machine Co. v. Northfield Insurance Co., 351 N.C. 293 (2000). In that case, the North Carolina Supreme Court sided with the insured in a dispute over property damage coverage, reinforcing the principle that unclear or undefined policy terms are interpreted against the insurer. The insured won because the court refused to let the carrier benefit from vague wording in its own policy.
What does that mean for your home in Orange County? Policies are dense, and carriers often lean on narrow readings of terms like 'collapse,' 'water damage,' or 'ensuing loss' to reduce payouts. Knowing how North Carolina courts have treated those terms changes the negotiation entirely.
When we review a denial or a low estimate for a Chapel Hill homeowner, we examine the exact policy language against established case law and documented damage. We cannot promise a particular result — every claim stands on its own facts and its own policy — but we can make sure the carrier's interpretation is challenged with the same legal reasoning North Carolina courts have already endorsed.
How Do Flood Claims Work In Chapel Hill, And Can Your Team Help With NFIP Policies?
Flood claims follow a different track than standard homeowner claims, and that catches many Chapel Hill residents off guard. Most flood coverage in Orange County comes through the National Flood Insurance Program (NFIP), administered by FEMA, rather than through a private homeowner policy. Standard home insurance almost never covers rising water, so the first step is identifying which policy actually applies to your loss.
NFIP claims carry strict deadlines. You generally must submit a signed Proof of Loss within 60 days of the flood, and the documentation requirements are more rigid than a typical fire or pipe-burst claim. Missing those deadlines can forfeit money you were otherwise entitled to receive. FEMA's site at fema.gov and the NFIP's resource at floodsmart.gov explain the program rules, and we recommend every homeowner near Bolin Creek, Booker Creek, or other flood-prone areas review them before a storm hits.
Our team helps policyholders document flood damage room by room, separate structure losses from contents losses, prepare the Proof of Loss correctly, and respond to the NFIP adjuster's findings. If part of your damage stems from a non-flood cause — say, hurricane rain entering through a damaged roof — we help sort out which policy owes what, since carriers often dispute that line.
We can't guarantee any specific recovery under NFIP rules, but accurate documentation and on-time filings consistently put homeowners in a far stronger position than going it alone.
What's The Difference Between The Insurance Company's Adjuster And A Public Adjuster Near Me Chapel Hill NC?
The difference comes down to one word: loyalty. The adjuster your insurance company sends — whether a staff adjuster or an 'independent' adjuster hired by the carrier — works for the insurance company. Their estimate reflects the carrier's interests. A Public Adjuster Near Me Chapel Hill NC works exclusively for you, the policyholder, and is paid only from what you recover.
That distinction shows up in the details. A carrier's adjuster might spend thirty minutes walking your fire-damaged home off Weaver Dairy Road and produce an estimate that misses smoke infiltration in the HVAC system, hidden moisture behind drywall, or code-upgrade costs required by Orange County inspections. Our job is to catch what gets missed, document it with photos, moisture readings, and contractor-level estimates, and present a complete claim.
North Carolina courts have recognized how one-sided these disputes can become. In Gaston County Dyeing Machine Co. v. Northfield Insurance Co., 351 N.C. 293 (2000), the state Supreme Court ruled for the insured in a property damage coverage dispute, holding that ambiguous policy language is construed against the insurer who wrote it. Having someone on your side who knows precedent like that changes the conversation with your carrier.
To be clear about scope: we handle claims involving homes, buildings, and contents — fire, smoke, water, hurricane, tornado, and similar losses. We do not handle claims for cell phones, motor vehicles, health, or life insurance. And while we never promise a specific payout, we do promise that every finding is yours, not the carrier's.
Do You Handle Commercial Property Claims In Chapel Hill, Or Only Residential?
We handle both. Our Chapel Hill public adjusters work with homeowners across neighborhoods like Southern Village, Meadowmont, and the historic districts near Franklin Street, and we also represent commercial policyholders — restaurants, retail shops, offices, and owners of rental properties that serve the UNC community.
Commercial claims tend to be more complicated than residential ones. Beyond building damage, there's often business personal property, tenant improvements, and business interruption coverage to document. Insurance carriers frequently dispute the scope of those losses, which is exactly where professional representation earns its keep.
North Carolina courts have shown they will hold insurers to the language of their own policies in commercial property disputes. In Gaston County Dyeing Machine Co. v. Northfield Insurance Co., 351 N.C. 293 (2000), the North Carolina Supreme Court sided with the insured in a property damage dispute, reinforcing the principle that ambiguous policy language must be construed in favor of the policyholder, not the carrier.
One note on what we don't do: we never take claims involving motor vehicles, cell phones, health, or life insurance. Our focus is strictly damage to homes, commercial buildings, and the contents inside them — fire, smoke, water, hurricane, tornado, hail, flood, theft, and vandalism losses throughout Orange County. If your loss fits that description, whether it's a kitchen fire in a Carrboro-adjacent home or smoke damage in a Franklin Street storefront, we can review your situation at no cost.
Can A Public Adjuster Near Me Chapel Hill NC Reopen A Claim I Already Settled?
In many situations, yes — a settled claim is not always a closed door. If you accepted a payment and later discovered additional damage, or you realize the original estimate missed entire categories of loss, a supplemental claim may be possible under your policy. We review these cases regularly for Orange County homeowners.
North Carolina generally allows three years from the date of loss to pursue a property claim, though your specific policy may set its own deadlines, so timing matters. The sooner we review your settlement paperwork and the carrier's estimate, the more options you typically have.
Common examples we see in Chapel Hill include water losses where hidden moisture led to mold behind walls months later, fire claims where smoke residue in HVAC systems wasn't scoped, and hurricane claims where interior damage surfaced after the initial inspection. In each case, we compare what was actually paid against what the policy owes, then document the gap with photos, moisture readings, contractor estimates, and line-item pricing.
To be straightforward with you: we can't promise a specific outcome or additional payment on any reopened claim. What we can promise is a thorough, honest review by a licensed and bonded firm. If we believe the settlement was fair, we'll tell you that too — it costs you nothing to find out, and it protects you from leaving legitimate policy benefits on the table.
What Documents Should I Gather Before Meeting With Your Adjusters In Chapel Hill?
The most important document is your full insurance policy, including the declarations page that lists your coverages, limits, and deductibles. If you can't locate it, don't worry — we can request a certified copy from your carrier on your behalf.
Beyond the policy, gather anything that shows the damage and the property's condition before the loss. That includes photos and videos of the damage, any pre-loss photos of your home or building, receipts or records for damaged contents, repair estimates you've already received, and any letters, emails, or estimates from the insurance company. If you've spoken with the carrier's adjuster, jot down dates and what was discussed.
For flood losses, the paperwork is stricter. NFIP policies require a signed, sworn Proof of Loss, typically within 60 days, and missing that deadline can jeopardize your recovery. If your Chapel Hill property flooded — common near Booker Creek and other low-lying areas after heavy storms — review your NFIP requirements at fema.gov/flood-insurance and floodsmart.gov, and contact us quickly so nothing lapses.
Don't throw anything away before we've documented it. Damaged contents are evidence, and discarding them before they're photographed and inventoried can shrink your claim. If local officials require debris removal for safety, photograph everything thoroughly first. When in doubt, call us before you clean up — a short conversation at the start often prevents expensive documentation gaps later.

Will Hiring A Public Adjuster Near Me Chapel Hill NC Slow Down My Claim Or Upset My Insurer?
No — in our experience, professional representation usually keeps a claim moving, not the opposite. Carriers are accustomed to working with public adjusters, and North Carolina law expressly licenses us to represent policyholders. For The Public Adjusters, Inc. is licensed and bonded in the state, and we follow the same regulatory standards insurers must respect.
Delays most often happen when a claim is poorly documented: the carrier requests more information, the homeowner scrambles to respond, and weeks slip by. We front-load the work instead — a detailed scope of damage, a line-item estimate, a contents inventory, and organized correspondence — so the insurer has fewer reasons to stall or send repeated requests.
Your insurer also cannot legally penalize you for exercising your rights. North Carolina's unfair claims settlement practices statutes require carriers to handle claims in good faith, and the courts back policyholders when they don't. In Accardi v. Hartford Underwriters Insurance Co., 373 N.C. 292 (2020), the North Carolina Supreme Court ruled for the homeowner in a property damage dispute, holding that ambiguous policy terms must be read in the insured's favor.
What changes when you hire us is simple: the adjuster's calls, inspections, and negotiations go through our office instead of landing on you. You stay informed and make every final decision, but you're no longer debating repair pricing with a claims professional on your own. For most Orange County families and business owners, that alone is worth the conversation.
Local Relevance
Chapel Hill's housing stock works against policyholders in claims. The town mixes historic and mid-century homes near the university with subdivisions built during the 1990s and 2000s boom, and carriers lean on "age" and "wear and tear" arguments for both. Older plaster, hardwoods, and discontinued brick and siding make matching a real fight here.
The tree canopy that makes Chapel Hill beautiful also makes it risky. Mature oaks and pines come down in summer thunderstorms, winter ice, and the narrow tornado and hail swaths that cut through the Triangle in spring. Because those paths are thin, your street can be hit hard while the next one over sees nothing — "nobody else filed" means very little.
Flooding is the quiet one. Low-lying lots along local creeks like Bolin Creek take water outside the Federal Emergency Management Agency (FEMA) high-risk zones, and homeowners policies exclude flood — that coverage comes only through a separate flood policy. We handle flood claims alongside fire and water losses, and we serve neighboring communities too, from smoke damage claim help in Rolesville to claims across Chatham and Johnston counties, including work as a public adjuster in Garner.
Ice is the most underrated peril in Chapel Hill claims: this area's periodic ice storms snap heavy limbs onto roofs and drive ice-dam leaks into older attics, yet carriers tend to treat each leak or strike as a minor one-off. Documenting the storm event and tracing every water path — not just the visible ceiling stain — is often the difference between a patch payment and a properly scoped repair.
Get A Free Claim Review From A Chapel Hill Public Adjuster
Before you accept the insurance company's number — or give up on a denial — let us read your policy and look at your damage. For The Public Adjusters, Inc. is licensed and bonded, works only for policyholders, and charges nothing unless your claim recovers. One conversation will tell you where your claim really stands.
Call us: (919) 400-6440
Helpful Resources
- NCDOI Public Adjusters Guide
- Federal Emergency Management Agency (FEMA)
- North Carolina Department of Insurance — State regulator that licenses public adjusters
- FloodSmart — the National Flood Insurance Program — Official NFIP resource on flood coverage
Serving Chapel Hill · Orange
Last updated: November 7, 2026