Before you search for Insurance Dispute Lawyers Elon NC, it helps to know that many denied, delayed, or underpaid property claims can be resolved without ever stepping into a courtroom. For The Public Adjusters, Inc. is a licensed and bonded public adjusting firm serving Elon and greater Alamance County, and we advocate for policyholders — not the insurance company. We document the damage, rebuild the claim on your terms, and negotiate directly with the carrier. If your dispute truly requires litigation, we can work alongside your attorney and hand over a fully documented file.
What This Service Is
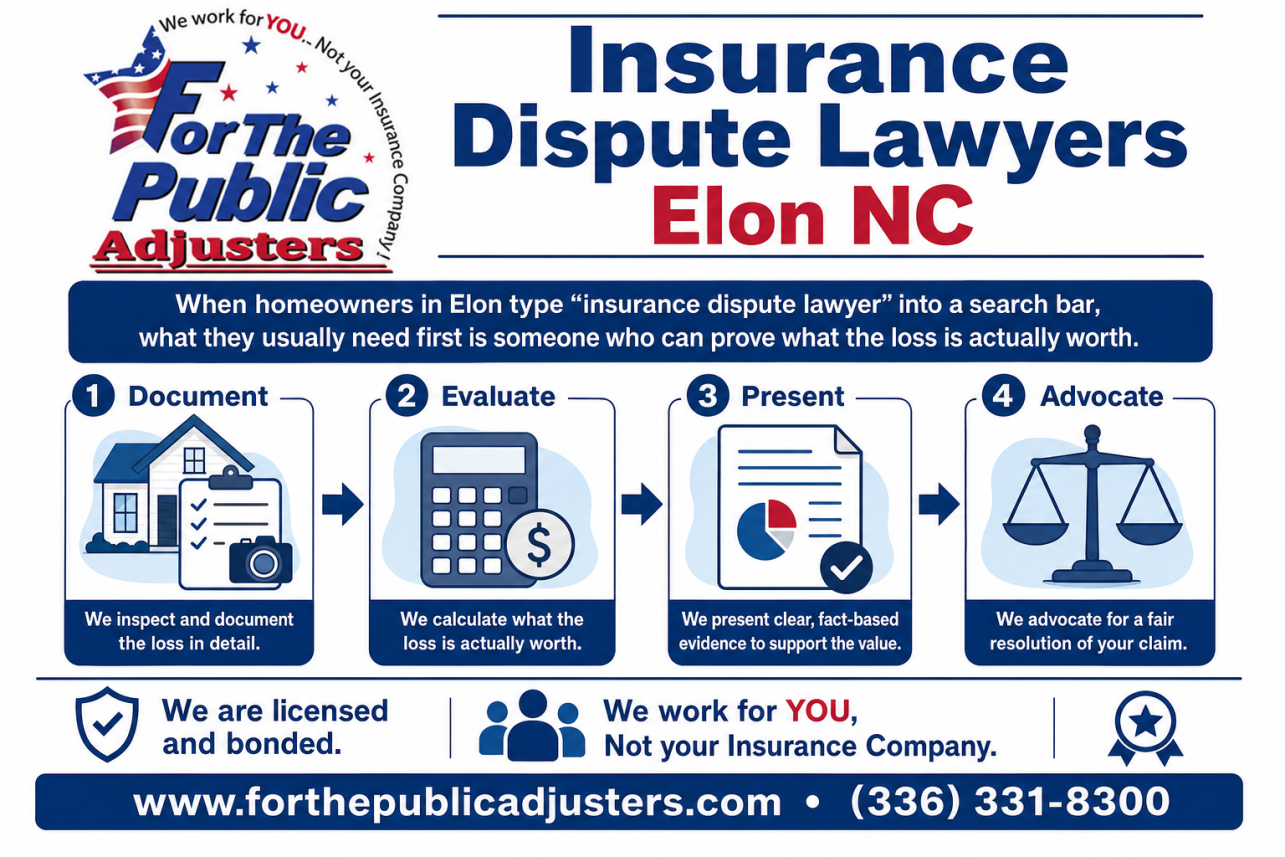
When homeowners in Elon type “insurance dispute lawyer” into a search bar, what they usually need first is someone who can prove what the loss is actually worth. That is the job of a public adjuster. We are licensed under North Carolina law to represent the policyholder in a property insurance claim — fire, smoke, water, tree damage, vandalism, arson-related homeowners claims, and commercial building losses.
The NCDOI Public Adjusters Guide draws a clear line: the adjuster your insurance company sends works for the insurance company. A public adjuster works only for you. Most disputes over a denied or lowballed claim come down to documentation — the scope of damage, the quality of materials, code upgrades, and contents — and that is a fight over evidence long before it is a fight over law.
We have seen this play out across the region, from a fire insurance claim help in Siler City case to structural losses here in Alamance County. When the file is built correctly, many disputes settle at the negotiating table. And policyholders do win when they push back: in Windridge of Naperville Condominium Association v. Philadelphia Indemnity Insurance Co., a federal appeals court sided with the insured building owner, ruling the insurer had to replace undamaged siding so the storm-damaged buildings would match — not just patch the panels it felt like paying for.
We do not handle claims involving cell phones, motor vehicles, health, or life insurance. Our work is homes, buildings, and their contents.
Common Problems
What Is My Disputed Claim Actually Worth — And What Does Getting Help Cost?
The number on your denial letter or lowball estimate is the carrier’s number, not necessarily the true cost to restore your property. Depreciation, overlooked code requirements, and missed contents routinely shave thousands off a settlement.
Public adjusters in North Carolina typically work on a percentage of the recovered amount, so there is no hourly bill piling up while you wait. We can never guarantee a specific outcome — no honest advocate can — but we can make sure the claim reflects everything your policy owes you, documented line by line.
My Claim Was Denied, Delayed, Or Underpaid. What Do I Actually Do Now?
First, do not accept the first offer as final and do not sign a release under pressure. In North Carolina you generally have the right to dispute the carrier’s findings, submit your own estimate, and demand a re-inspection.
The most common obstacle we see is the “pre-existing damage” argument, especially on older homes with aging roofs and plumbing. That is a documentation battle. On a recent water damage claim help in Bynum file, the difference came down to proving when the intrusion started — the kind of evidence a homeowner rarely knows to collect on their own.
Insurance Dispute Lawyers Elon NC Or A Public Adjuster — Who Should Handle My Claim?
It depends on where your dispute stands. If the carrier has committed clear bad faith or a lawsuit is already inevitable, an attorney belongs on your team. But if the fight is over how much the damage is worth, a public adjuster is usually the faster, more economical first move — and many claims settle once the evidence is undeniable.
The National Association of Insurance Commissioners (NAIC) encourages policyholders to verify licensing before hiring any claim representative, and we welcome that check. We are licensed and bonded, and when a case does need to go legal, the file we build becomes the backbone of your attorney’s argument.
Our Process
Free Policy And Claim Review
We read your full policy — endorsements, exclusions, deadlines — and compare it against the carrier’s position. Many Elon homeowners are surprised to learn coverage exists that the adjuster’s estimate simply ignored. You will know where you stand before you commit to anything.
Independent Damage Documentation
We inspect and document the loss ourselves: structure, finishes, contents, and hidden damage the first inspection missed. From a house fire in Elon to a tree damage insurance claim help in Carrboro assignment, thorough scoping is what turns a dispute into a settlement conversation.
Negotiation — And Litigation Support If It Comes To That
We present the documented claim to the carrier and negotiate on your behalf. Most disputes resolve here. If yours does not, we coordinate with your attorney and supply the estimates, photos, and correspondence trail a courtroom fight requires. Either way, you are never facing the insurance company’s team alone.
| Question | Public Adjuster | Insurance Dispute Attorney |
|---|---|---|
| What do they do? | Documents, values, and negotiates your property or contents claim directly with the carrier | Litigates coverage denials, bad faith, and contract disputes in court |
| When is it the right fit? | Underpaid or disputed home, building, or contents claims where the carrier is still negotiating | Flat denials with no movement, alleged bad faith, or claims already in litigation |
| Typical cost structure | Percentage of the recovered claim amount, regulated in North Carolina | Contingency fee or hourly billing, often a larger share of recovery |
| Timeline | Often weeks to a few months through negotiation or appraisal | Frequently a year or longer if the case goes to court |
| Licensing | Licensed and bonded by the NC Department of Insurance | Licensed by the North Carolina State Bar |
| Can they work together? | Yes — adjusters often build the documented claim file attorneys later rely on | Yes — many attorneys prefer a professionally documented loss before filing suit |
Commonly Overlooked In The Public Adjusting Industry
- Recoverable depreciation on replacement cost policies — Policyholders often accept the initial actual-cash-value check and never realize they can recover the withheld depreciation after completing repairs.
- Ordinance and law coverage for code upgrades — Carriers frequently omit the cost of bringing older Elon-area homes up to current building code, even when the policy includes coverage for it.
- Smoke and soot contamination in HVAC systems — Ductwork damage is invisible from a walk-through inspection, so it rarely appears in a carrier’s first estimate after a fire.
- The appraisal clause as an alternative to lawsuits — Most policyholders have never read their policy’s dispute provisions and assume court is the only way to challenge a low number.
- Proof of loss deadlines and documentation requirements — Missing a sworn proof of loss deadline can jeopardize an otherwise valid claim, and carriers rarely volunteer reminders.
- Hidden moisture behind walls and under flooring after pipe breaks — Surface drying looks complete while trapped moisture in wall cavities quietly leads to mold that the original settlement never funded.
- Additional living expenses and fair rental value — Displaced homeowners and landlords often pay out of pocket for housing or absorb lost rent without knowing the policy reimburses those costs.
- Matching requirements for roofing and siding materials — Carriers may pay to patch a damaged slope or wall section even when discontinued materials mean a reasonable match is impossible.
Case Studies
Case Study #1
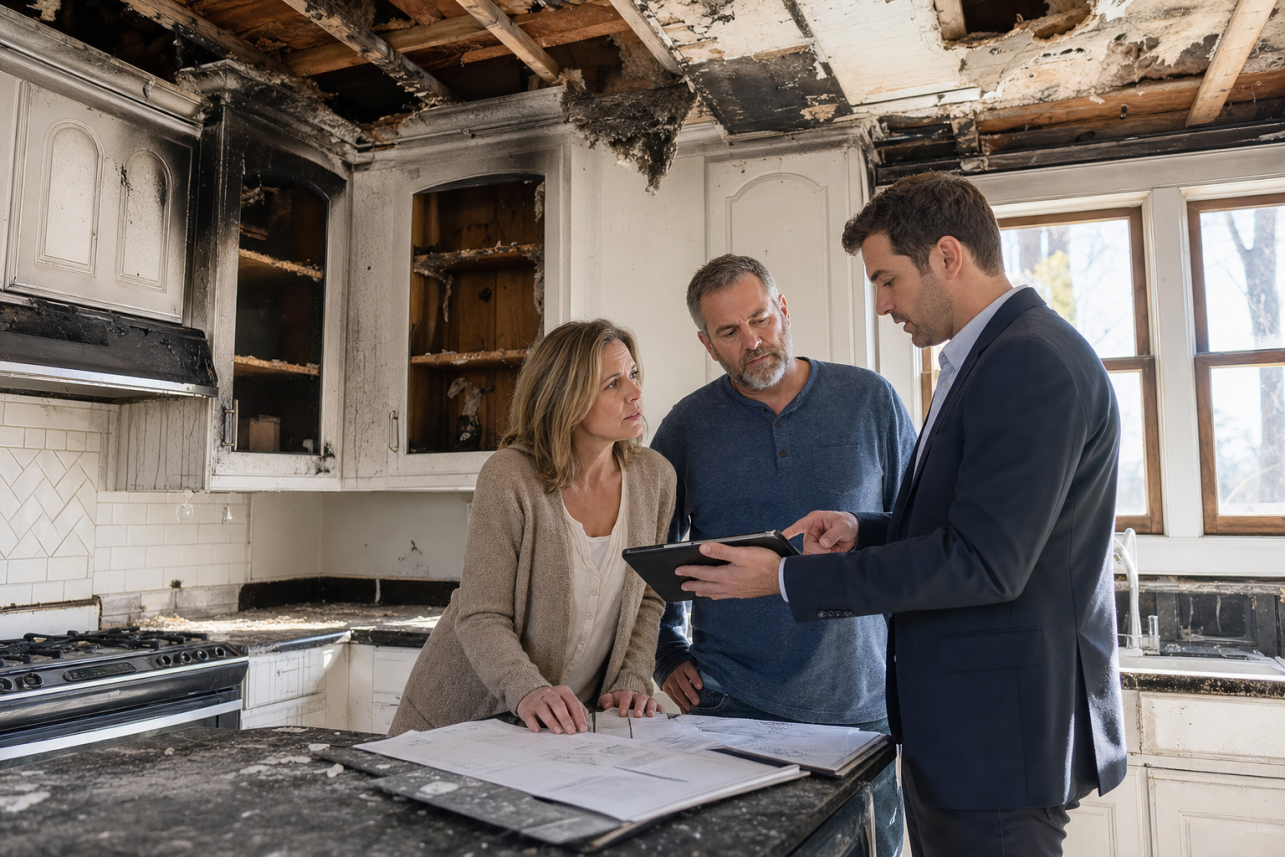
Situation: A family near downtown Elon suffered a kitchen fire that spread smoke and soot through their two-story home. Their insurer’s adjuster inspected quickly and issued a settlement covering only the kitchen and adjacent hallway.
Problem: The carrier’s estimate ignored soot contamination in the HVAC ductwork, smoke odor absorbed into insulation and soft contents, and heat damage to wiring above the kitchen ceiling. The family was told the rest of the house just needed ‘a good cleaning.’
Investigation: Our team performed a room-by-room inspection with surface wipe sampling, opened the attic access to check insulation, and had the duct system scoped. We also built a full contents inventory instead of the carrier’s two-page summary.
Findings: Soot residue was present on surfaces three rooms away from the fire. The blown-in insulation held smoke odor that no surface cleaning would remove, and the duct system was recirculating contaminants every time the HVAC ran. The contents inventory was roughly triple what the carrier had listed.
Solution: We prepared a revised estimate with photographic and testing documentation, filed a detailed proof of loss, and negotiated directly with the carrier’s adjuster. When negotiations stalled on scope, we referenced how North Carolina courts have sided with policyholders on fire losses — including Bryant v. Nationwide Mutual Fire Insurance Co., 313 N.C. 362 (1985), where the North Carolina Supreme Court protected an innocent policyholder’s right to recover on a home fire claim the insurer had refused to pay.
Outcome: The claim was reopened and settled for substantially more than the original offer, with the duct cleaning, insulation replacement, and full contents inventory included. The family also recovered additional living expenses for the weeks they could not occupy the home.
Lesson: A fast first offer on a fire claim is almost never a complete offer. Smoke travels far beyond the burn area, and documentation — not argument — is what changes a carrier’s position.
Case Study #2
Situation: A rental property owner in Alamance County had a home damaged when a tornado tracked through the area, tearing shingles, cracking rafters, and driving rain into the second floor. The insurer denied most of the structural claim, calling the roof damage ‘pre-existing wear and tear.’
Problem: The denial left the owner facing a roof replacement, interior water remediation, and lost rental income with almost no payment. The carrier’s inspection lasted under thirty minutes and never included the attic.
Investigation: We pulled weather data confirming the tornado’s path, brought in a structural inspection of the rafters, and documented fresh fracture patterns and creasing consistent with a single violent storm event rather than gradual aging. Interior moisture mapping tied the water intrusion directly to the storm date.
Findings: The rafter cracks showed clean, recent breaks with no weathering inside the fracture. Interior staining had a single-event moisture profile. Nothing supported the wear-and-tear theory, and the policy plainly covered direct physical loss from a tornado.
Solution: We submitted a rebuttal package and invoked the policy’s appraisal provision when the carrier held its position. We also reminded the carrier that North Carolina courts have repeatedly enforced homeowners’ recovery rights on disputed property losses, as in North Carolina Farm Bureau Mutual Insurance Co. v. Sadler, 365 N.C. 178 (2011), where the state Supreme Court ruled in favor of an innocent policyholder on a disputed dwelling fire loss.
Outcome: The appraisal award covered the full roof structure, interior repairs, and code-required upgrades under the ordinance and law provision. The owner also recovered fair rental value for the months the unit was uninhabitable.
Lesson: ‘Wear and tear’ is one of the most common denial reasons after a tornado, and it is also one of the most beatable — if the damage is documented properly and quickly, before repairs erase the evidence.
| Your Situation | Best First Step | What It Depends On |
|---|---|---|
| Fire or smoke claim underpaid | Independent damage documentation and a revised proof of loss | Whether hidden smoke, soot, and odor damage was ever inspected |
| Tornado or hurricane damage called ‘wear and tear’ | Storm-date evidence, structural inspection, and a scope rebuttal | How soon the property is documented before repairs alter the evidence |
| Water damage from a burst pipe partially paid | Moisture mapping and a line-by-line estimate comparison | Whether damage behind walls and under flooring was measured |
| Claim flatly denied with the insurer refusing to reconsider | Consultation with a licensed adjuster; attorney referral if the denial holds | Whether the denial rests on facts that new documentation can disprove |
| Insurer’s number and yours are far apart, but coverage is accepted | Invoke the appraisal clause in your policy | Whether your policy contains an appraisal provision and deadlines allow it |
| Flood damage from rising water | Confirm NFIP or flood policy coverage and file with the correct program | Standard homeowners policies exclude flood; FEMA (fema.gov) and the NFIP (floodsmart.gov) govern most flood claims |
| Business or rental building loss with lost income | Full documentation of both physical damage and business or rental interruption | Whether the policy includes loss-of-income or fair rental value coverage |
| Suspected bad faith or unfair claim handling | Preserve all correspondence, then seek legal counsel | Whether the carrier’s conduct goes beyond a valuation disagreement |
Reviews
Our insurance company denied our house fire claim and hinted they thought the fire was suspicious. We were about to call an attorney when a friend recommended For The Public Adjusters instead. They documented everything — fire department report, contents, smoke damage upstairs — and got the claim paid without us ever setting foot in a courtroom. They were honest that a lawyer is the right call in some situations, but this wasn’t one of them.
Marcus T., Elon
After the tornado came through, our carrier’s adjuster spent maybe twenty minutes on our roof and offered us a fraction of the repair cost. For The Public Adjusters found cracked rafters and water damage the first inspection completely missed. They handled the appraisal process and the final settlement covered the actual repairs. I had no idea a policyholder could hire their own adjuster until this.
Deborah H., Alamance County
Burst pipe flooded our downstairs over a holiday weekend. The insurer wanted to pay for drying only, not the flooring or the mold remediation behind the baseboards. This team fought the scope line by line and got a much fairer result. Only reason for four stars is the process took longer than I hoped — though I understand that was the carrier dragging its feet, not them. They kept me informed the whole way.
James R., Elon
Frequently Asked Questions
Do I Need Insurance Dispute Lawyers Elon NC, Or Can A Public Adjuster Resolve My Claim?
Many Elon homeowners searching for legal help with a denied or underpaid claim are surprised to learn that most property insurance disputes never need a courtroom. For The Public Adjusters, Inc. is a licensed and bonded public adjusting firm, and in the majority of cases we resolve disputes directly with the insurance company through documentation, policy analysis, and negotiation.
A public adjuster works exclusively for you, the policyholder — never the carrier. We inspect the damage, prepare a detailed independent estimate, and challenge the insurer’s numbers line by line. Attorneys typically become necessary only when a carrier acts in bad faith or refuses a reasonable settlement after every other avenue is exhausted.
When litigation truly is the right path, we can coordinate with counsel and hand over a fully documented file, which strengthens the case considerably. Courts do side with policyholders in property disputes. In Sproull v. State Farm Fire & Casualty Co. (Illinois Supreme Court, 2021), the court ruled in favor of the insured homeowner, holding that the insurer could not depreciate labor costs when calculating actual cash value on a property damage claim — a decision that put real money back in policyholders’ pockets.
For most Alamance County families, starting with a public adjuster is faster and less expensive than starting with a law firm. We cannot promise a specific outcome — no honest professional can — but we can promise your claim will be documented, valued, and argued the way the policy language actually requires.
What Types Of Property Claims Do You Handle For Homeowners In Elon And Alamance County?
We handle disputed insurance claims involving damage to homes, commercial buildings, and their contents throughout Elon and the surrounding Alamance County communities.
Common claims we work on include fire and smoke damage, water damage from burst pipes or appliance failures, roof and structural damage from hurricanes and tornadoes, hail damage, and theft or vandalism losses. When remnants of a hurricane push through the Piedmont — as this area has seen more than once — the resulting roof, siding, and interior water damage often gets undervalued by carriers, and that’s exactly where an independent adjuster on your side makes a difference.
For flood losses, coverage usually falls under a separate flood policy through the National Flood Insurance Program rather than your homeowners policy. If your Elon property took on floodwater, we recommend reviewing resources at FEMA.gov and FloodSmart.gov (the official NFIP site) to understand how those claims are structured — and we can help you dispute an NFIP or private flood claim that was handled unfairly.
To be clear about what we do not handle: we do not take claims involving cell phones or other personal electronics disputes, motor vehicles, health insurance, or life insurance. Our focus is real property and contents, period. That specialization is why our estimates and dispute files hold up under scrutiny when a carrier in Alamance County tries to lowball a legitimate loss.
Have Policyholders Actually Won Cases Against Insurance Companies Over Building Damage?
Yes — and those victories shape how carriers behave at the negotiating table, which is why anyone comparing Insurance Dispute Lawyers Elon NC options should understand the case law that favors policyholders.
One of the most cited examples is Sproull v. State Farm Fire & Casualty Co., decided by the Illinois Supreme Court in 2021. The homeowner’s roof was damaged, and State Farm depreciated not just the materials but also the labor when paying the actual cash value. The court held for the insured, ruling that labor does not depreciate and the carrier had underpaid the claim. Similar rulings across the country have forced insurers to correct how they value damaged homes and buildings.
Another instructive win is Cedell v. Farmers Insurance Company of Washington (2013), where a homeowner whose house was damaged by fire fought back against a delayed, lowballed claim. The Washington Supreme Court sided with the insured, limiting the carrier’s ability to hide its claim-handling conduct behind privilege in bad-faith cases.
What these cases mean for an Elon or Alamance County property owner is practical: insurers know courts will scrutinize improper depreciation, delay tactics, and undervalued estimates. When we present a dispute backed by thorough documentation and correct policy interpretation, carriers understand the legal landscape behind it.
We never guarantee any particular settlement — every loss and every policy is different — but the record shows that well-documented, properly argued property claims get taken seriously.
How Does The Claim Dispute Process Work With Your Elon Team, And What Does It Cost?
The process starts with a review of your denial letter or settlement offer alongside your full policy — including endorsements and exclusions most homeowners never read. If we believe the carrier undervalued or wrongly denied your Elon property claim, we move forward.
Next comes documentation. We perform our own inspection of the structure and contents, photograph and measure the damage, and build an independent estimate using the same industry pricing tools carriers use. For a fire loss on a home near downtown Elon or storm damage to a building out toward the county line, this step alone often reveals thousands of dollars the original adjuster missed — hidden moisture, code-upgrade costs, matching requirements for siding or shingles, and undervalued contents.
We then present the dispute to the insurance company in writing, negotiate directly with their adjusters, and if needed invoke the appraisal clause found in most North Carolina property policies, which brings in a neutral umpire to resolve valuation disagreements without a lawsuit.
As for cost, public adjusters in North Carolina work on a contingency percentage of the recovered amount, agreed to in writing before any work begins. There are no upfront fees and no hourly billing. If your claim recovery doesn’t improve, you owe nothing for the adjusting work.
We are licensed and bonded in North Carolina, and while we can’t promise a specific dollar figure, we can promise your claim will be fought with the documentation and policy knowledge it deserves.
What Deadlines Do I Face Before Contacting Insurance Dispute Lawyers Elon NC About A Denied Or Underpaid Claim?
Deadlines matter more than most policyholders realize. In North Carolina, most property insurance policies include a contractual suit-limitation clause, often requiring legal action within one to three years of the date of loss. Miss that window and even a strong claim can become unenforceable.
On top of the policy language, North Carolina’s general statute of limitations for breach of contract is three years. Which deadline controls depends on your specific policy wording, so pull out your declarations page and the conditions section before assuming you have time.
Our Elon team encourages homeowners in Alamance County to act well before any deadline. Evidence disappears fast — repairs get made, contractors move on, and receipts get lost. The earlier we review your denial letter and policy, the more options remain, whether that means a supplemental claim, appraisal, or referral to litigation counsel.
North Carolina courts have shown they will hold insurers accountable when policyholders act in time. In Gray v. North Carolina Insurance Underwriting Association, 352 N.C. 61 (2000), homeowners whose dwelling was damaged by Hurricane Fran pursued their carrier over claim handling, and the North Carolina Supreme Court allowed their bad-faith and unfair-practices claims to proceed. Timely action made that outcome possible.
We never promise a specific result, but acting promptly protects every avenue you have.
My Flood Claim In Elon Was Underpaid — Can Your Team Help With That?
Yes, flood claims are among the disputes we review most carefully, because they follow different rules than standard homeowners claims. If your Elon property flooded and your policy is through the National Flood Insurance Program, your coverage is governed by federal regulations, not just North Carolina insurance law.
That distinction matters. NFIP claims carry strict requirements, including a sworn proof of loss that generally must be submitted within 60 days of the loss unless FEMA extends the deadline. Many underpayments happen simply because documentation was incomplete, not because the damage wasn’t covered.
Our role as licensed and bonded public adjusters is to re-inspect the property, build a detailed line-item estimate of structural and contents damage, and compare it against what the flood carrier paid. Low Buffalo Creek areas and older Alamance County homes with finished lower levels often see disputes over what counts as covered building damage versus excluded items.
We recommend every flood policyholder review the official resources at FEMA.gov and FloodSmart.gov, the NFIP’s consumer site, to understand appeal rights and deadlines. If your dispute ultimately requires litigation, we can coordinate with an insurance dispute lawyer serving the Elon area.
We can’t guarantee a specific payment, but a properly documented flood claim is far harder for a carrier to underpay a second time.
What Documentation Should I Gather Before Disputing My Property Claim In Elon?
Strong disputes are built on paper, so start collecting immediately. First, secure a complete certified copy of your policy — not just the declarations page. Your carrier must provide it on request, and the endorsements often contain the language the whole dispute turns on.
Second, preserve the damage itself. Photograph and video every affected room, the roof, the exterior, and damaged contents before any repairs. Date-stamp everything. Keep damaged materials when practical, even samples of flooring, drywall, or shingles, because adjusters and courts respond to physical evidence.
Third, keep a claim diary. Log every phone call with the insurer, the adjuster’s name, what was said, and every email. Save the carrier’s estimate, the denial or underpayment letter, and any engineer or contractor reports they relied on. In hurricane and tornado losses across Alamance County, disputes often come down to whether damage was caused by the storm or pre-existing wear — your timeline and photos answer that question.
Finally, gather independent repair estimates from local contractors and receipts for emergency mitigation like tarping or water extraction. Policies require you to prevent further damage, and those receipts are typically reimbursable.
When you bring this file to our team, we can evaluate the gap between what was paid and what the loss actually costs to repair, then pursue the difference through negotiation or the policy’s appraisal provision.

Are Insurance Dispute Lawyers Elon NC And Public Adjusters Licensed, And Are There Claims You Won’t Handle?
Both professions are regulated in North Carolina, and you should verify credentials before hiring anyone. Attorneys are licensed through the North Carolina State Bar. Public adjusters like our firm are licensed and bonded through the North Carolina Department of Insurance, which you can confirm on the Department’s website in minutes.
For The Public Adjusters, Inc. handles disputes involving damage to homes, commercial buildings, and their contents — fire and smoke, water and pipe bursts, hurricane and tornado damage, hail, lightning, theft, and vandalism. If your Elon or Alamance County property suffered structural or contents loss and the carrier denied, delayed, or underpaid, that is squarely what we do.
There are claims we do not take. We don’t handle disputes involving motor vehicles, cell phones or other personal electronics claims outside a covered property loss, health insurance, or life insurance. Those fall under entirely different regulatory frameworks and require different specialists.
On the property side, North Carolina law gives policyholders real leverage. In Gray v. North Carolina Insurance Underwriting Association, the state’s highest court permitted homeowners to pursue their insurer for bad faith after a Hurricane Fran dwelling loss — proof that carriers answer to the courts when they mishandle building claims.
We never guarantee a particular recovery, but we can tell you honestly whether your dispute is one we’re licensed and equipped to fight.
What Happens If My Insurer Acted In Bad Faith — Can Insurance Dispute Lawyers Elon NC Pursue Extra Damages?
North Carolina law does allow policyholders to recover more than the policy amount when an insurer handles a claim in bad faith, and the courts have backed that up in real cases. In Gray v. North Carolina Insurance Underwriting Association, homeowners whose coastal house was damaged during Hurricane Fran sued after the carrier lowballed and delayed their claim. The North Carolina Supreme Court sided with the insureds, and the case stands as a warning to carriers that unfair claim handling carries real consequences.
Bad faith can look like unexplained delays, ignoring your documentation, misrepresenting what your policy covers, or making a settlement offer far below documented repair costs on your Elon home or commercial building.
Our role at For The Public Adjusters, Inc. is often the first line of defense. As licensed and bonded public adjusters, we document the loss, re-scope the damage, and negotiate directly with the carrier. Many disputes resolve at that stage. When they don’t — or when the carrier’s conduct crosses into unfair claim practices under N.C. Gen. Stat. § 75-1.1 or § 58-63-15 — we can refer you to attorneys who litigate these cases in Alamance County.
We never guarantee a specific outcome, because every policy and every loss is different. What we can promise is a thorough, professionally documented claim file, which is exactly what makes bad-faith conduct visible and provable if the dispute escalates.
My Claim Was Already Settled And Paid — Can Your Elon Team Reopen It If The Payment Was Too Low?
In many situations, yes. Accepting a claim payment in North Carolina does not automatically close the door. If you cashed a check for fire, hail, hurricane, or water damage to your Elon home and later discovered hidden damage — or realized the carrier’s estimate missed entire trades like roofing underlayment, insulation, or code-required upgrades — you can typically file a supplemental claim.
The key question is whether your policy conditions and deadlines still allow it. Most property policies in NC give you a window to submit additional documentation, and the statute of limitations for breach of an insurance contract is generally three years, though many policies shorten the suit deadline. That’s why timing matters, and why we review the policy language first.
When we reopen an underpaid claim, we re-inspect the property, prepare a line-item estimate, photograph everything the original adjuster missed, and present the supplement with supporting evidence. Common finds in Alamance County properties include hail-bruised shingles the carrier called cosmetic, hidden moisture behind drywall, and smoke residue in HVAC systems after a kitchen fire.
A local dispute team — whether that means an Elon public adjuster, an appraiser, or eventually an attorney — starts with the file the carrier already built and shows where it falls short. We can’t promise a specific dollar recovery, but a properly documented supplement gives the carrier a factual record it has to answer to, rather than a phone call it can brush off.
How Does The Appraisal Clause Work In North Carolina, And Is It Faster Than Suing My Insurer?
Most homeowner and commercial property policies issued in North Carolina contain an appraisal clause, and for many Elon policyholders it’s the fastest route to resolving a pricing dispute. Either side can invoke it in writing when you and the carrier agree the damage is covered but disagree on the amount of the loss.
Here’s the process: you select your appraiser, the insurance company selects theirs, and the two appraisers choose a neutral umpire. Any two of the three signing an award makes it binding on the amount. Appraisals often conclude in weeks or a few months, while litigation in Alamance County can stretch well past a year.
Appraisal is best suited to valuation fights — the carrier says your hurricane-damaged roof costs $12,000 to repair and your contractor says $34,000. It is not the right tool when the insurer denies coverage outright; those disputes usually require legal counsel.
As licensed and bonded public adjusters, we prepare the detailed estimate and damage documentation that an appraisal award gets built on, and we can serve in the appraisal process on covered building and contents losses. North Carolina courts routinely enforce these awards. In Harleysville Mutual Insurance Co. v. Narron, the North Carolina Court of Appeals upheld an appraisal award in the insureds’ favor after a dispute over damage to their property, confirming that carriers can’t simply walk away from the result.
We’ll tell you honestly whether appraisal, negotiation, or an attorney referral fits your specific situation — no guaranteed outcomes, just the right strategy.
Do You Handle Fire, Smoke, And Water Damage Disputes For Rental Properties And Businesses In Elon?
Yes. Alongside owner-occupied homes, we represent landlords, small businesses, and commercial building owners throughout Elon and Alamance County — rental houses near the university, retail spaces along Haggard Avenue, and light-industrial buildings across the county. Insurance Dispute Lawyers Elon NC searches often come from these owners because commercial and landlord claims get underpaid in ways residential policyholders never see, such as disputed business-interruption periods, depreciation applied too aggressively, or lost rental income calculated from the wrong lease terms.
Fire and smoke claims are a frequent battleground. Carriers may pay to repaint but refuse to address smoke penetration in insulation, ductwork, and contents. Water losses from burst pipes or failed water heaters bring fights over matching flooring, hidden mold, and whether the leak was ‘sudden and accidental.’ We document all of it with moisture readings, photos, and line-item estimates before the carrier’s number becomes the final word.
One note on flood: rising surface water is excluded from standard property policies and is covered instead through the National Flood Insurance Program. If your Elon rental took on floodwater, start with FEMA (fema.gov) and NFIP (floodsmart.gov) resources, and we can help you understand where an NFIP claim ends and your standard policy begins.
We do not handle claims involving motor vehicles, cell phones, health, or life insurance — our focus stays on buildings and their contents. That focus is exactly why local property owners bring us their toughest disputed claims. Results always depend on the policy and the facts, so we start every case with a straightforward, no-obligation policy review.
Can I Negotiate A Disputed Property Claim Myself, Or Should I Call Insurance Dispute Lawyers Elon NC First?
You can absolutely negotiate on your own, and some straightforward claims settle fairly without help. The problem is that most Elon homeowners are negotiating against trained adjusters who handle claims every day, and the playing field is rarely level.
Before you accept a low offer or a denial, it costs nothing to have our team review your policy and the insurer’s estimate. We frequently find covered items the carrier’s adjuster missed — code-upgrade costs, matching issues on roofing and siding, hidden water damage behind walls, and understated contents losses.
North Carolina courts have repeatedly sided with policyholders who pushed back. In Gaston County Dyeing Machine Co. v. Northfield Insurance Co., 351 N.C. 293 (2000), the North Carolina Supreme Court ruled in favor of the insured after carriers tried to deny coverage for property damage, confirming that the loss was covered under the policy language. Cases like that show why the insurer’s first answer isn’t always the final answer.
As licensed and bonded professionals, For The Public Adjusters, Inc. documents your loss, prepares a detailed independent estimate, and negotiates directly with the carrier. If the dispute requires litigation, we can coordinate with Insurance Dispute Lawyers Elon NC policyholders trust so nothing falls through the cracks. We never guarantee a specific dollar outcome — no honest professional can — but we make sure your claim is presented completely and accurately, which is often the difference between a lowball offer and a fair settlement.
How Long Does A Disputed Property Insurance Claim In Elon Typically Take To Resolve?
It depends on how the dispute is resolved. When we re-open negotiations with a detailed independent estimate, many underpaid claims in Elon and greater Alamance County resolve within 30 to 90 days. Carriers often move quickly once they see professional documentation — photographs, moisture readings, line-item repair pricing, and a properly valued contents inventory.
If negotiation stalls, invoking the appraisal clause in your policy typically adds another 60 to 120 days, since each side selects an appraiser and an umpire may need to rule on disputed items. Appraisal is still usually much faster than a lawsuit.
Litigation is the longest path. A court case in Alamance County can take a year or more, which is why we treat it as the last resort rather than the first move. That said, some denials — especially those involving misapplied exclusions or bad-faith conduct — leave no other option, and we help policyholders connect with a qualified insurance dispute lawyer in Elon when that time comes.
One thing that shortens every timeline: acting early. North Carolina policies contain proof-of-loss deadlines and cooperation requirements, and the state’s statute of limitations on contract claims can bar a lawsuit entirely if you wait too long. The sooner our team reviews your denial or underpayment letter, the more options remain open. We can’t promise a specific timeline or result for any claim, but we can promise your file will be complete, organized, and ready for whichever path gets you treated fairly.
Do You Handle Hurricane And Tornado Damage Disputes For Elon Homes And Buildings?
Yes. Storm systems moving through the Piedmont have produced tornado touchdowns and hurricane remnants that damaged roofs, chimneys, siding, and interiors across Alamance County, and these claims are among the most commonly underpaid we see.
Hurricane and tornado disputes often turn on causation. A carrier may attribute roof damage to “wear and tear” or pre-existing conditions rather than the storm, or pay for spot repairs when the entire roof slope needs replacement to achieve a reasonable match. Interior water damage that followed a storm-created opening is another frequent battleground. We document the storm date, weather data, and the physical evidence tying your damage to the event.
One important note: standard homeowners policies exclude rising water. If a hurricane brought flooding into your Elon home, that portion of the loss falls under a separate flood policy through the National Flood Insurance Program. You can learn more at fema.gov and floodsmart.gov, and we can help you understand where the wind claim ends and the flood claim begins — a line insurers sometimes draw in their own favor.
We handle disputes for houses, rental buildings, commercial structures, and damaged contents. We do not handle claims involving motor vehicles, cell phones, health, or life insurance. As a licensed and bonded firm, we prepare your storm claim thoroughly and negotiate for full policy benefits, though no one can guarantee what a carrier will ultimately pay on any specific loss.
Will Disputing My Claim Make My Insurer Drop Me — And Do Insurance Dispute Lawyers Elon NC Or Public Adjusters See Retaliation Happen?
This is one of the most common fears we hear from Elon policyholders, and the short answer is that exercising your rights under your own policy is not grounds for retaliation. Your insurance contract gives you the right to dispute an estimate, invoke appraisal, hire a public adjuster, or consult counsel. Using those rights is not fraud, and it is not a legitimate basis for cancellation.
North Carolina law regulates when and how a carrier can cancel or non-renew a property policy, and mid-term cancellation generally requires specific grounds such as nonpayment or material misrepresentation. Filing legitimate claims can affect renewal pricing over time — that’s true whether you dispute the payout or not — but a well-documented, honest dispute is a normal part of the claims process, not a red flag.
In our experience serving Elon and the surrounding Alamance County communities, policyholders who push back with solid documentation are treated more carefully by carriers, not worse. Insurers know that disputes handled by licensed and bonded professionals, or escalated by Insurance Dispute Lawyers Elon NC property owners retain, are the ones most likely to end up in appraisal or court if handled badly. North Carolina courts have shown they will hold carriers accountable, as the state Supreme Court did for the insured in Gaston County Dyeing Machine Co. v. Northfield Insurance Co. when coverage for property damage was wrongly contested.
If you’re hesitating to challenge a low offer out of fear, bring us the paperwork. We’ll give you a straight assessment of whether the dispute is worth pursuing — no pressure and no promises we can’t keep.
Local Relevance
Elon sits in the heart of the North Carolina Piedmont, where the claims we see follow the weather. Remnants of hurricanes push heavy rain and tornado risk inland to Alamance County, mature hardwoods drop limbs through roofs, summer thunderstorms drive water intrusion, and winter ice storms bring down trees onto older homes.
The local housing stock adds another layer. Elon blends historic homes near the university and old mill-town neighborhoods with newer subdivisions along the growth corridor toward Burlington and Mebane. Older homes give carriers room to argue wear-and-tear; newer ones raise fights over matching materials and builder-grade versus like-kind replacement.
We work these disputes across the county line as well — including cases like flood damage claim help in Mebane, where low-lying lots along Piedmont creeks flood after tropical remnants stall over the region. Flood losses run through a separate federal policy with its own rules, which is exactly why local, policy-specific guidance matters before you accept any number.
Because so many disputes in Elon involve older Piedmont homes, carriers often lean on the wear-and-tear or pre-existing-damage argument to cut payouts on roof and water losses; homeowners who photograph their roof, plumbing, and interiors while everything is in good condition tend to have far stronger footing when a storm claim gets challenged.
Disputing A Property Claim In Elon? Talk To Us Before You Settle
Whether your claim was denied outright or the check simply does not cover the repairs, get a second opinion from a licensed and bonded public adjusting firm that answers only to you. The review costs nothing, and you will finally know what your claim is really worth.
Call us: (336) 331-8300
Helpful Resources
- NCDOI Public Adjusters Guide
- National Association of Insurance Commissioners (NAIC)
- North Carolina Department of Insurance — State regulator overseeing insurers and public adjuster licensing
- National Association of Insurance Commissioners — Consumer resources on insurance disputes and licensing verification
Last updated: September 22, 2026