

If you need help with a Vandalism Homeowners Claim Elon NC, For The Public Adjusters, Inc. represents you — not the insurance company — from the police report through the final settlement check. Vandalism to your home is typically covered under a standard homeowners policy, but insurers often question whether damage is truly vandalism or pre-existing wear. We document every broken window, kicked-in door, and spray-painted surface so your claim reflects the real cost to restore your home. We are licensed and bonded, and we only get paid when you do.
What This Service Is
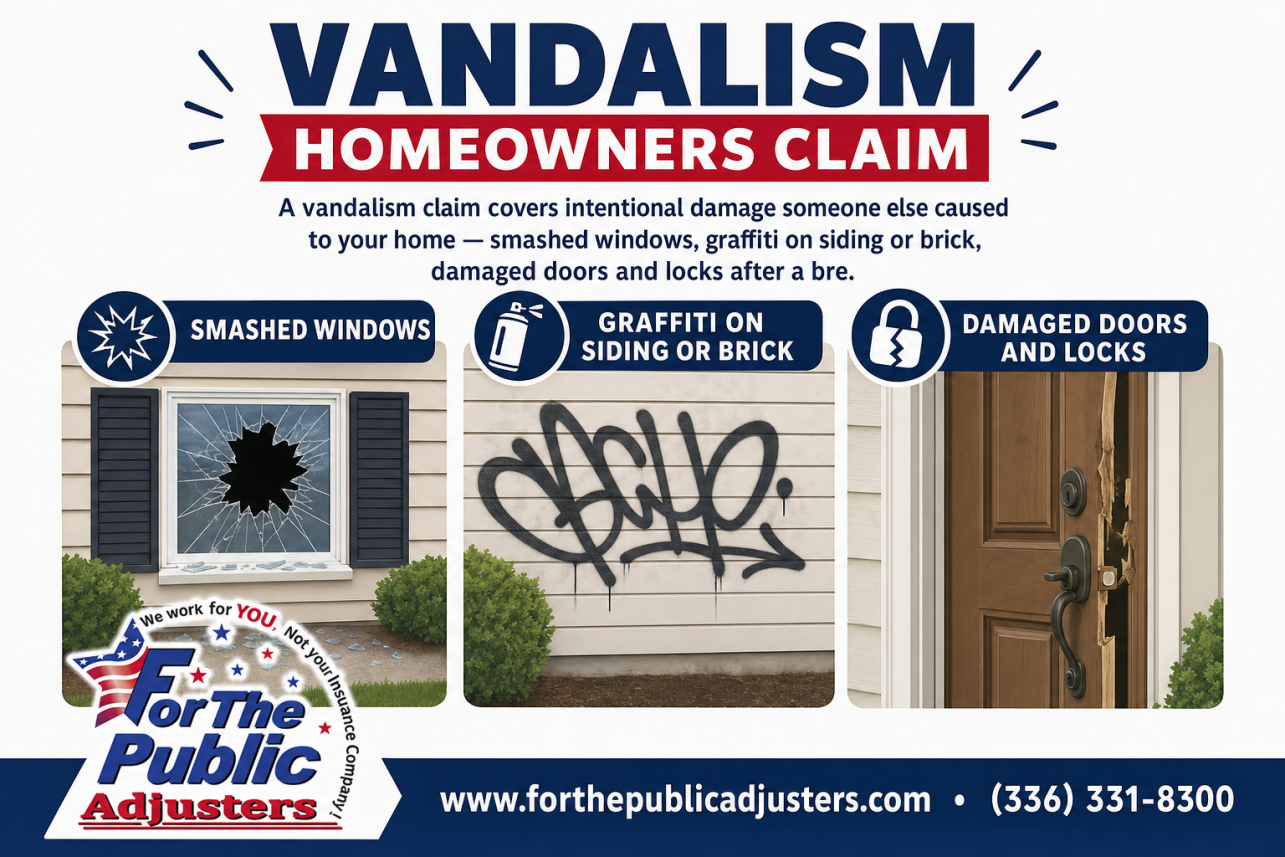
A vandalism claim covers intentional damage someone else caused to your home — smashed windows, graffiti on siding or brick, damaged doors and locks after a break-in, destroyed landscaping fixtures, or interior damage left behind by intruders. Most homeowners policies cover this, yet the payout often comes down to how well the loss is documented and valued.
As public adjusters, we work only for policyholders. We read your policy line by line, identify what applies to your loss, prepare the repair scope and cost estimate, and negotiate directly with the insurance company’s adjuster. That includes the details homeowners rarely see coming: the difference between actual cash value and replacement cost, depreciation deductions, your deductible, and the proof of loss paperwork the insurer requires.
Vandalism claims have a few unique wrinkles. Almost every policy requires a police report, and coverage can be excluded if a home has sat vacant beyond a set number of days — a real issue for rental properties and homes between owners. We handle those requirements correctly the first time, the same way our team handles a Homeowners Vandalism Insurance Claim in Durham and similar losses across the Triad and Triangle. When a loss involves deliberate fire-setting rather than property destruction, that becomes an arson matter — like the Arson Homeowners Claim in Clayton work we also handle — and we manage those separately with the added scrutiny they bring.
Common Problems
What Is My Vandalism Damage Actually Worth — And Why Is The Insurer’s Number So Low?
The first offer on a vandalism loss is often built on a quick walk-through and generic pricing. It may miss hidden damage behind a kicked-in door frame, undercount graffiti removal costs on brick or painted siding, or price a broken window as a pane of glass rather than a full unit replacement.
Depreciation is another quiet reducer. If your policy pays actual cash value first, the insurer subtracts for age and condition, and many homeowners never recover the held-back replacement cost portion because no one told them how to claim it. We build an independent repair estimate, itemize what the carrier missed, and make sure depreciation and your deductible are applied correctly — not conveniently. We never guarantee a specific outcome, but we make sure the number on the table reflects the actual damage.
My Vandalism Homeowners Claim Elon NC Was Denied Or Is Dragging On. What Now?
Vandalism claims get denied for a handful of predictable reasons: no police report on file, the insurer arguing the damage is old wear and tear rather than a deliberate act, or a vacancy exclusion because the home was empty when it happened. Others simply stall — weeks pass with requests for one more document and no payment.
A denial or delay is not the end of the claim. Policyholders have the right to dispute the insurer’s position, submit additional evidence, and demand a written explanation of any denial. Courts have repeatedly sided with property owners when insurers cut corners — in Windridge of Naperville Condominium Association v. Philadelphia Indemnity Insurance Co., the insured building owner won when the insurer tried to pay for only a fraction of damaged siding, and the court required the carrier to pay for a proper, matching repair. We reopen and appeal underpaid and denied claims regularly, and when a dispute genuinely needs litigation, we work alongside insurance dispute lawyers.
Should I Just Handle The Claim Myself, Or Is A Public Adjuster Worth It?
For a single broken pane with an obvious cost below your deductible, you may not need anyone. But once a claim involves a break-in, multiple damaged surfaces, graffiti on masonry, or an insurer questioning what happened, the gap between a self-filed claim and a professionally documented one can be substantial.
A good public adjuster does three things you can verify before hiring: shows you a North Carolina license, explains their fee as a percentage of the recovery with nothing owed up front, and walks you through your specific policy language before promising anything. The NCDOI Public Adjusters Guide is worth reading before you sign with anyone — it explains exactly what public adjusters may and may not do in this state. We encourage every homeowner in Elon to check credentials first, including ours.
Our Process
Secure The Scene, File The Police Report, And Make Temporary Repairs
Call the police and get a report number — nearly every policy requires it for vandalism. Then make reasonable temporary repairs like boarding a broken window to prevent further damage, and keep every receipt. Those out-of-pocket costs are typically reimbursable. Do not make permanent repairs before the damage is documented.
We Document The Loss And Build The Real Repair Estimate
We photograph and inventory every damaged item and surface, from shattered glass and door hardware to graffiti removal and repainting. Then we prepare a detailed, line-item repair estimate and the proof of loss statement your policy requires, so nothing is left to the insurance company’s interpretation.
We Negotiate The Settlement On Your Behalf
We present the claim, respond to the carrier’s adjuster, and push back on lowball figures, improper depreciation, and misapplied exclusions. You approve any settlement before it is final. Our fee is a percentage of what you recover — if you recover nothing, you owe us nothing.
| Claim Stage | Filing On Your Own | With Our Elon Public Adjusters |
|---|---|---|
| Documenting the damage | Cell-phone photos of obvious damage; hidden losses like cut pipes, contaminated insulation, or paint-soaked subfloors often missed | Room-by-room photo log, moisture mapping, contents inventory, and specialist reports for masonry, plumbing, and flooring |
| Interpreting the policy | Carrier’s reading of vacancy clauses, intentional-acts exclusions, and sublimits usually goes unchallenged | Every exclusion tested against the policy’s exact definitions and North Carolina case law favoring policyholders |
| Estimating repairs | You rely on the insurer’s estimate, which frequently prices graffiti as a repaint and skips code-required upgrades | Independent line-item estimate at current Alamance County contractor pricing, including ordinance and law coverage where it applies |
| Negotiating the settlement | One homeowner versus a trained company adjuster with no obligation to point out what was left off the offer | A licensed, bonded advocate who negotiates solely for you and documents every disputed line |
| Handling a denial | Most homeowners accept the denial letter as final | Formal rebuttal with evidence, policy language, and precedent — as in N.C. Farm Bureau v. Sadler, where the insured prevailed |
Commonly Overlooked In The Public Adjusting Industry
- Water damage flowing from cut or stolen plumbing — Carriers and homeowners both tend to file it mentally under ‘plumbing problem’ instead of treating it as part of the vandalism loss, which changes what gets paid.
- The policy’s exact vacancy definition — Adjusters sometimes invoke vacancy after any extended absence, but most policies require 60 consecutive days without contents sufficient for occupancy — a standard many denials don’t actually meet.
- Graffiti penetration into porous surfaces — A quick estimate prices one coat of paint, when spray paint absorbed into brick mortar, cedar siding, or unsealed drywall often requires sealing, replacement, or professional restoration.
- Board-up, security, and emergency mitigation costs — Homeowners pay out of pocket to secure the property after a break-in and forget these are typically reimbursable duties-after-loss expenses under the policy.
- Ordinance and law coverage triggered by repairs — Reopening walls after vandalism can require electrical or plumbing brought up to current Alamance County code, and that upgrade cost is missed unless the coverage is specifically claimed.
- The innocent co-insured doctrine — Blanket denials citing the intentional-acts exclusion often ignore that North Carolina’s Supreme Court sided with the policyholder in N.C. Farm Bureau v. Sadler when one insured destroyed the home and the other
Case Studies
Case Study #1
Situation: A retired couple on Westbrook Avenue in Elon returned from a six-week stay with family in Raleigh to find their brick ranch broken into. Interior walls were spray-painted, kitchen cabinets were pried off the studs, and copper supply lines had been cut out of the crawlspace, flooding the subfloor.
Problem: Their carrier’s adjuster inspected once, then issued a reservation-of-rights letter arguing the home was ‘vacant’ and that the vacancy provision suspended vandalism coverage. The initial offer covered only the broken rear door — about $2,100 on damage that clearly ran into six figures.
Investigation: Our team pulled the exact policy language, which defined vacancy as a dwelling without contents sufficient for normal occupancy for 60 consecutive days. We photographed the fully furnished home, obtained Duke Energy and City of Burlington water records showing continuous utility usage, and gathered mail-hold documentation proving the absence was 42 days — a temporary trip, not vacancy.
Findings: The home never met the policy’s own definition of vacant. We also found the carrier’s estimate omitted the crawlspace water damage entirely, missed mold beginning on floor joists, and priced graffiti remediation as a single coat of paint over porous drywall that actually required sealing or replacement.
Solution: We prepared a line-by-line rebuttal estimate, a contents inventory of destroyed and stolen items, a moisture-mapping report from an independent hygienist, and a formal coverage position letter dismantling the vacancy argument with the utility and postal records attached.
Outcome: The carrier withdrew the vacancy defense and reopened the claim. The final settlement covered structural repairs, full copper repipe, subfloor and joist remediation, contents, and additional living expenses while the couple stayed elsewhere — many times the original offer.
Lesson: Vacancy is a defined term, not a feeling. Insurers sometimes apply it loosely to vandalism losses in Alamance County, and documented proof of occupancy can turn a near-denial into a fully paid claim.
Case Study #2
Situation: A homeowner near downtown Elon was going through a difficult separation. Her estranged spouse, still a named insured on the homeowners policy, entered the house and destroyed it — smashed fixtures, slashed furniture, poured paint across hardwood floors, and punched holes through nearly every interior door.
Problem: The insurance company denied the entire claim, reasoning that because the damage was an intentional act ‘by an insured,’ no one on the policy could recover — including the innocent wife who had nothing to do with it.
Investigation: We reviewed the denial against North Carolina law, obtained the Elon Police Department incident report identifying the spouse as the sole actor, and documented the wife’s separate interest in the property. We then researched how North Carolina courts treat innocent co-insureds.
Findings: North Carolina’s own Supreme Court has ruled for the policyholder on exactly this issue. In North Carolina Farm Bureau Mutual Insurance Co. v. Sadler, 365 N.C. 178 (2011), the court held that an innocent co-insured spouse could recover for home damage under the state’s standard policy provisions even though the other insured intentionally caused the loss. The carrier’s blanket denial ignored controlling North Carolina precedent.
Solution: We submitted a coverage demand citing Sadler, paired with a complete room-by-room repair estimate, a contents schedule with replacement pricing, and the police documentation establishing the wife’s innocence in the loss.
Outcome: Facing its own state’s Supreme Court authority, the insurer reversed the denial and paid the innocent co-insured’s claim for the structure and contents, allowing her to restore the home and move forward.
Lesson: A denial letter is a starting position, not a verdict. When the damage is to a home or its contents and the policyholder’s hands are clean, North Carolina case law can be a powerful tool on the insured’s side.
| Scenario | Key Coverage Question | First Steps to Protect Your Claim | What the Outcome Often Depends On |
|---|---|---|---|
| Graffiti on brick, siding, or fencing | Cosmetic repaint vs. full restoration of porous or matching materials | Photograph before any cleaning; get a masonry or siding specialist’s opinion | Whether paint penetrated the surface and whether matching materials are still available |
| Break-in with interior destruction | Vandalism coverage plus theft coverage for anything taken | File an Elon Police report immediately; do not discard damaged contents before they’re documented | How thoroughly contents are inventoried and whether stolen items are claimed under the correct coverage |
| Copper pipe theft with water damage | Whether the resulting water damage is covered as part of the vandalism loss | Shut off water, report promptly, and get moisture readings before drying hides the evidence | Speed of mitigation and proof the water release stemmed from the vandalism event |
| Damage to a home that sat unoccupied | Does the policy’s vacancy or unoccupancy clause suspend vandalism coverage? | Gather utility bills, mail records, and photos showing furnishings and use | The policy’s exact vacancy definition and how many consecutive days the home was truly empty |
| Vandalism by an estranged spouse or co-insured | Can the innocent co-insured still recover under the intentional-acts exclusion? | Obtain the police report naming the responsible party; document your separate ownership interest | North Carolina precedent — the insured won on this issue in N.C. Farm Bureau v. Sadler, 365 N.C. 178 (2011) |
| Home left uninhabitable by the damage | Additional living expense (ALE) coverage for temporary housing | Keep every receipt for lodging, meals, and mileage above your normal costs | Whether the damage genuinely prevents occupancy and how expenses are documented |
| Detached garage, shed, or fence damage | Other-structures coverage limits, typically 10% of the dwelling limit | Document each structure separately with its own photos and repair estimate | Whether the combined structure damage exceeds the other-structures sublimit |


Reviews
Our rental-turned-primary home off Haggard Avenue was trashed by an evicted occupant’s friends — graffiti, kicked-in doors, and every appliance ruined. The insurance company offered less than $5,000. For The Public Adjusters re-documented everything, caught water damage under the kitchen the first adjuster never crawled under to see, and the final payment covered the actual repairs. Night and day difference.
Marcus T., Elon NC
Thieves cut the copper lines out of my late mother’s house in Elon while it sat in probate, and the carrier tried to call it vacant and deny the vandalism. This team proved the home still met the occupancy terms of the policy and fought the water damage estimate line by line. They were licensed, bonded, and completely transparent about every step. I couldn’t have navigated that denial alone.
Deborah W., Alamance County
After a break-in near campus, we had spray paint on brick, two shattered windows, and slashed furniture. The insurer wanted to power-wash the brick and repaint one wall. For The Public Adjusters brought in a masonry specialist who showed the paint had penetrated the mortar, and the settlement ended up covering proper restoration instead of a cosmetic patch. Worth every bit of the fee.
Jason & Emily R., Elon NC
Frequently Asked Questions
What Should I Do First After Discovering Vandalism To My Home In Elon, NC?
Your first call should be to the Elon Police Department or the Alamance County Sheriff’s Office, depending on where your property sits. Nearly every homeowners policy requires a police report for vandalism and malicious mischief losses, and adjusters will ask for the report number early in the process.
Next, document everything before you touch it. Photograph broken windows, spray paint, damaged doors, destroyed contents, and any point of entry from multiple angles. Keep a written list of damaged items with approximate purchase dates and values.
You should also make reasonable temporary repairs to prevent further damage — boarding a broken window or securing a kicked-in door, for example. Save every receipt, because those emergency costs are typically reimbursable. Do not make permanent repairs until the insurance company has had a chance to inspect, or you risk a dispute over the scope of the loss.
Finally, notify your insurer promptly, but be careful with recorded statements. Casual remarks about how long the home sat empty or when you last visited can be used to question coverage later. Many Elon homeowners bring in a licensed public adjuster at this stage so the claim is presented accurately from the start. For The Public Adjusters, Inc. is licensed and bonded in North Carolina, and we handle the documentation, valuation, and negotiation so you are not left interpreting policy language on your own after a break-in or malicious damage.
Does Homeowners Insurance Cover A Vandalism Homeowners Claim Elon NC, Including Damage To My Personal Belongings?
In most cases, yes. A standard homeowners policy covers vandalism and malicious mischief to both the dwelling and your personal property, which matters for a Vandalism Homeowners Claim Elon NC where intruders often destroy contents — electronics, furniture, clothing — in addition to breaking in.
There is one major exception every Elon homeowner should know: the vacancy clause. Most policies exclude vandalism losses if the home has been vacant for more than 30 or 60 consecutive days before the damage. This trips up families in Alamance County who inherit a property, list a house for sale, or own a rental between tenants. Insurers frequently deny on vacancy grounds, and the difference between “vacant” and merely “unoccupied” is a genuine legal distinction that can be argued.
Coverage typically includes structural damage like broken doors, shattered glass, graffiti, and destroyed fixtures, plus the cost to repair or replace damaged contents. If the home is uninhabitable, additional living expense coverage may pay for temporary housing while repairs are made.
What your policy actually pays depends on whether you carry replacement cost or actual cash value coverage on contents, your deductible, and any sub-limits. We review those provisions line by line before the claim is presented. While no adjuster can guarantee a specific outcome, a properly documented and properly framed claim gives you the strongest position under the terms of your own policy.
Why Would An Insurance Company Dispute Or Underpay A Vandalism Claim, And Has A Homeowner Ever Won In Court?
Insurers push back on vandalism losses for a few recurring reasons. They may argue the home was vacant beyond the policy’s time limit, claim the damage was wear and tear rather than malicious acts, question the contents inventory, or suggest the loss does not meet the policy’s definition of vandalism at all.
Policyholders have successfully fought these arguments. In Georgitsi Realty, LLC v. Penn-Star Insurance Co., 21 N.Y.3d 606 (2013), a building owner’s structure was badly damaged by reckless excavation next door, and the insurer denied the claim, arguing it wasn’t “vandalism.” New York’s highest court sided with the insured, holding that vandalism coverage can extend to reckless conduct causing property damage — not just spray paint and broken windows. The decision is a strong reminder that carriers sometimes read coverage more narrowly than courts do.
For an Elon homeowner, the lesson is practical: a denial letter is an insurance company’s opinion, not the final word. Policy definitions, North Carolina case law, and the specific facts of your loss all matter.
As your public adjuster in Elon, we build the file the way it should have been built from day one — police reports, photographs, contractor estimates, contents inventories, and a written analysis of the coverage language. We negotiate directly with the carrier’s adjuster on your behalf. We never promise a specific dollar figure, because no honest adjuster can, but we make sure your claim is measured and argued completely.
How Does For The Public Adjusters, Inc. Handle A Vandalism Claim In Elon, And What Does It Cost?
We start with a free review of your policy and your loss. An Elon public adjuster from our team inspects the property in person — whether it’s a home near the university, a rental off Haggard Avenue, or a house in the surrounding Alamance County countryside — and identifies every category of covered damage, including things homeowners often miss like damaged wiring, plumbing tampering, and code-upgrade costs.
From there, we prepare a complete claim package: a detailed structural repair estimate, a room-by-room contents inventory with replacement values, temporary repair receipts, and additional living expenses if you had to relocate. We then present the claim to your insurer and handle every inspection, phone call, and settlement negotiation.
Our fee is a percentage of the recovery, agreed to in writing before we begin. If there is no recovery, you owe us nothing, so our interests are aligned with yours. We are licensed and bonded in North Carolina.
Timelines vary with the severity of the damage and the carrier’s responsiveness, but most vandalism losses in this area resolve within a few weeks to a few months once properly documented. Whether you’re filing fresh or your Vandalism Homeowners Claim Elon NC has already been underpaid or denied, we can step in at any stage — including reopening a closed claim within the policy’s time limits. One note on scope: we handle property claims for homes, buildings, and contents only, not claims involving vehicles, health, or life insurance.
How Long Do I Have To File A Vandalism Homeowners Claim Elon NC After The Damage Happens?
You should report the loss to your insurance company as soon as reasonably possible — most homeowners policies require “prompt notice,” and waiting weeks can give the carrier an argument that delayed reporting prejudiced its investigation.
Beyond the notice requirement, North Carolina law generally allows three years to bring a lawsuit on a property insurance contract, though many policies attempt to shorten that window in their conditions. Read your policy’s “Suit Against Us” clause carefully, because those deadlines are enforced strictly.
There is also a practical clock running. Vandalism damage in Elon homes — broken windows, kicked-in doors, spray paint, plumbing torn out — often leads to secondary problems like water intrusion or unsecured openings. Your policy requires you to take reasonable steps to protect the property from further damage, so board-ups and emergency tarping should happen quickly, and those costs are typically reimbursable when documented.
Our recommendation for any Vandalism Homeowners Claim Elon NC is simple: file the police report the same day you discover the damage, notify the carrier within 24 to 48 hours, photograph everything before touching it, and keep every receipt for temporary repairs. If you bring us in early, we handle the notice, the proof of loss deadlines, and the documentation timeline for you, so nothing lapses while you deal with the stress of a violated home.
My Elon Property Was Vacant Or Unoccupied When It Was Vandalized. Will The Insurance Company Deny The Claim?
Not automatically — but this is one of the most contested issues in vandalism losses, and carriers lean on it hard. Most homeowners policies exclude vandalism and malicious mischief if the dwelling has been vacant for a set period, commonly 60 consecutive days before the loss.
The key is that “vacant” and “unoccupied” are not the same thing. A home that still contains furniture and personal property, that you visit regularly, or that is between tenants may be unoccupied but not legally vacant. Insurers frequently blur that distinction to deny claims, and North Carolina courts have historically construed ambiguous policy language against the company that drafted it.
This matters in Elon and the surrounding Alamance County area, where rental houses near the university, estate properties, and homes listed for sale often sit empty for stretches. If your carrier denies coverage on a vacancy theory, do not accept the denial at face value.
We investigate the actual condition and use of the home — utility records, contents inventories, showing schedules, neighbor statements — to establish whether the vacancy provision truly applies. We have seen denials reversed once the facts were properly documented and presented. While no one can promise a specific outcome, a vacancy denial is often the beginning of the negotiation, not the end of it.
How Is Vandalism Damage To My Home And Contents Actually Valued In A Claim?
Most homeowners policies pay the dwelling on a replacement cost basis, meaning the cost to repair or replace damaged building components with materials of like kind and quality. Contents may be paid at replacement cost or at actual cash value (replacement cost minus depreciation), depending on your policy form and endorsements.
Where Elon homeowners get shortchanged is in the scope, not just the pricing. Vandalism rarely damages one clean surface. Spray paint on brick may require full masonry cleaning or sealing, not a spot treatment. A kicked-in door often means a damaged jamb, frame, and trim. Slashed carpet in one room can trigger matching considerations for continuous flooring. Carriers frequently write estimates for the smallest visible repair and skip the connected work.
North Carolina courts have long protected policyholders when insurers try to narrow what a homeowner is owed. In Bryant v. Nationwide Mutual Fire Insurance Co., 313 N.C. 362 (1985), the North Carolina Supreme Court ruled in favor of an innocent insured homeowner seeking payment for damage to the family dwelling after the carrier refused to pay, confirming that an insured who did nothing wrong could still recover under the policy. The case remains a cornerstone for policyholders fighting unfair denials on home damage claims in this state.
We prepare an independent, line-item estimate of the full scope — building and contents — and negotiate from documented evidence rather than accepting the carrier’s first number.
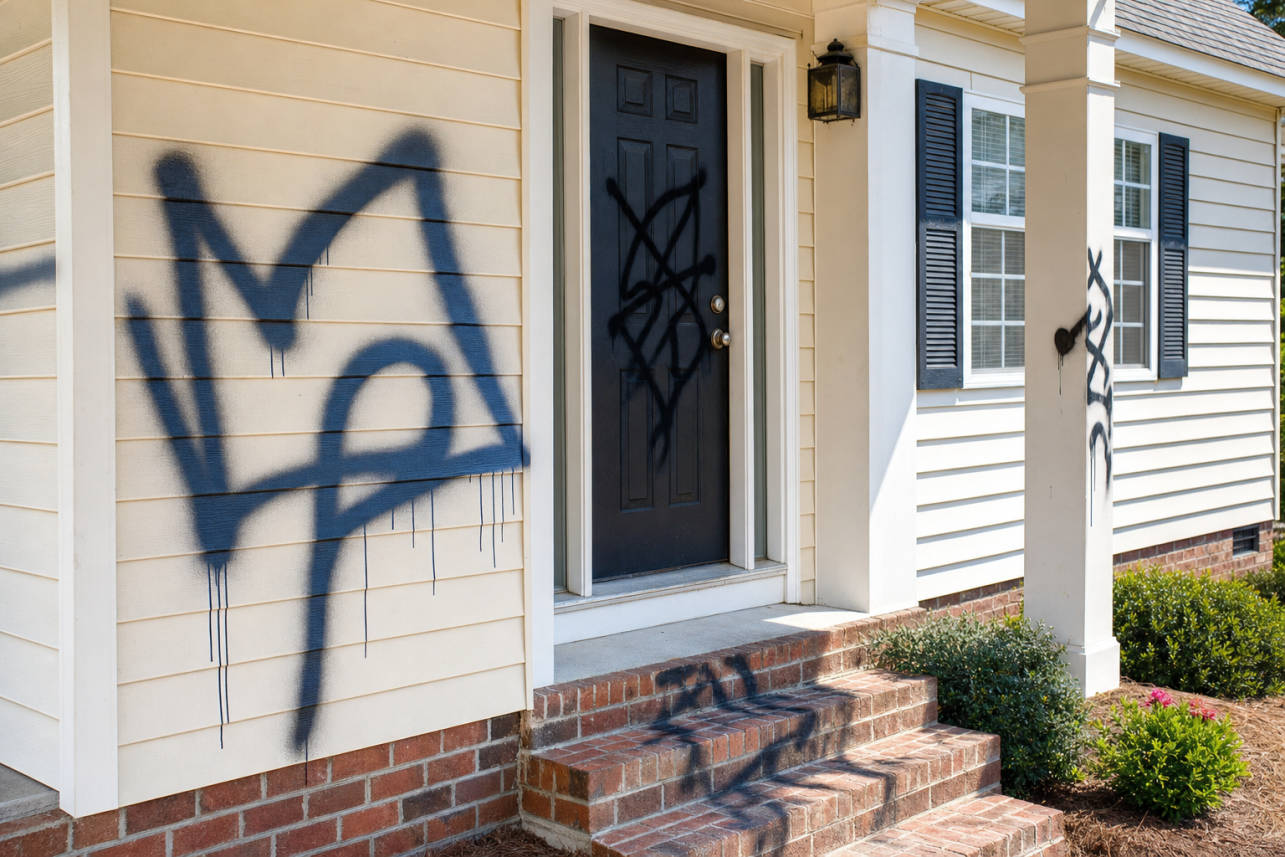
What Evidence Should I Gather In Elon Before The Insurance Adjuster Inspects The Vandalism?
Strong documentation is what separates a smooth vandalism claim in Elon from a disputed one. Start with the Elon Police Department or Alamance County Sheriff’s Office report — get the report number and the responding officer’s name, because virtually every policy requires notifying law enforcement for vandalism and theft losses.
Before cleaning anything, photograph and video every damaged area from multiple angles: wide shots showing location in the home, then close-ups of each broken item, graffiti tag, damaged wall, or torn fixture. Capture serial numbers and model information on damaged electronics and appliances where visible.
Build a written inventory of damaged contents with descriptions, approximate purchase dates, and original costs. Pull receipts, credit card statements, or even old photos of the rooms — holiday pictures often prove what you owned. Keep every damaged item until the carrier’s adjuster has seen it or given written permission to dispose of it.
Save receipts for emergency measures like board-up services, locksmiths, and temporary security, since reasonable protective costs are generally covered. If the home is unsafe to occupy, track hotel and meal costs for a possible additional living expense claim.
When For The Public Adjusters, Inc. handles the file, we manage this evidence process for you — as a licensed and bonded firm serving Alamance County, we know exactly what carriers look for and what they use to cut payments when documentation is thin.
Will Filing A Vandalism Claim In Elon Raise My Homeowners Insurance Premiums Or Get My Policy Dropped?
It can affect your rates, but usually less than homeowners fear. Vandalism is classified as a non-weather property loss, and a single claim of that type rarely triggers non-renewal on its own in North Carolina. Insurers weigh your overall claim history, the size of the payout, and how long you have been with the company.
What matters more is filing the claim correctly the first time. A claim that drags on, gets reopened, or turns into a dispute creates more red flags in an insurer’s file than a well-documented loss that settles cleanly. That is one reason many Elon and Alamance County homeowners bring in a public adjuster early rather than after things go wrong.
It is also worth doing the math before you file. If someone spray-painted a fence and the repair is a few hundred dollars over your deductible, filing may not make sense. But vandalism losses are often larger than they first appear — broken fixtures, damaged flooring, graffiti that requires full repainting or siding replacement, and destroyed contents add up quickly. Our team can review the damage and your policy before you commit to filing, so you make that decision with real numbers instead of guesses.
One thing we will never do is promise a specific outcome or dollar amount. What we can do is make sure every covered item is documented, valued properly, and presented so the insurer has no legitimate reason to shortchange the settlement.
The Person Who Vandalized My Elon Home Was A Tenant, Ex-Partner, Or Someone I Know. Does That Change My Coverage?
It can, and this is one of the most common trouble spots in vandalism losses across Alamance County. Most homeowners policies cover vandalism and malicious mischief committed by third parties. Problems arise when the person who caused the damage is an insured under the policy, a resident of the household, or in some policies, a tenant.
If an estranged spouse who is still named on the policy destroys the interior of the home, some carriers will deny the claim under the ‘intentional acts of an insured’ exclusion. However, courts in many states have pushed back when the innocent spouse had nothing to do with the damage, and North Carolina policy language varies from carrier to carrier. The exact wording of your exclusions matters enormously here.
Tenant damage is its own category. Landlord and dwelling policies treat malicious tenant damage differently than standard homeowners forms — some cover it as vandalism, some exclude it, and some carve out only certain types. If you own a rental near the university or elsewhere in Elon, do not accept a denial at face value.
Homeowners have prevailed against carriers that stretched exclusions too far. In State Farm Fire & Casualty Co. v. Simmons, 963 S.W.2d 42 (Tex. 1998), the insurer accused the policyholders of intentionally destroying their own home and denied the claim. The court sided with the Simmons family, finding the carrier’s investigation was outcome-driven, and the insureds recovered their policy benefits plus additional damages for the insurer’s bad faith. The lesson: exclusions must be proven by the insurer, not merely alleged.
Can A Public Adjuster Still Help If My Vandalism Homeowners Claim Elon NC Was Already Denied Or Underpaid?
Yes. Being brought in after a denial or a low offer is one of the most common ways homeowners find us. A denied Vandalism Homeowners Claim Elon NC is not necessarily the end of the road — it is the insurance company’s opening position, and it can often be challenged with better documentation and a correct reading of the policy.
The first thing we do is request the carrier’s denial letter and claim file, then compare their stated reasons against the actual policy language. Denials frequently rest on shaky ground: an exclusion applied too broadly, a vacancy clause invoked without proof, or damage mislabeled as wear and tear instead of malicious destruction.
If the claim was paid but underpaid, we prepare an independent damage estimate. Carrier estimates for vandalism routinely miss items — graffiti abatement that requires full-surface repainting rather than spot treatment, matching requirements for damaged siding or flooring, code-required upgrades during repair, and the full replacement cost of destroyed contents.
From there, we negotiate directly with the carrier on your behalf. Where the dispute is purely about the amount of the loss, most North Carolina policies include an appraisal provision that can resolve the disagreement without litigation. If bad faith is involved, we can coordinate with an attorney, though most reopened claims settle well before that point.
We are licensed and bonded in North Carolina, and we work on a contingency basis, so our interests are aligned with yours. While no one can guarantee a specific result, a professionally documented and re-presented claim gives you a far stronger position than accepting the first answer.
Vandals Broke Pipes And Flooded Part Of My House In Elon. Is The Water Damage Covered Under Vandalism?
In most cases, yes — and this distinction is critical. When intruders deliberately break plumbing, smash a water heater, or leave faucets running to destroy a home, the resulting water damage is generally covered as part of the vandalism loss, not as a separate water or flood event. The vandalism is the proximate cause, and the water is the mechanism of damage.
That matters because some carriers try to reclassify this damage to apply harsher limitations. Standing water from malicious plumbing destruction is not the same as natural flooding from rising surface water, which homeowners policies exclude and which requires separate coverage through the National Flood Insurance Program (floodsmart.gov) or guidance from FEMA (fema.gov). If an adjuster suggests your vandal-caused water loss is a ‘flood,’ that characterization deserves an immediate challenge.
Document the point of origin carefully before cleanup: the broken pipe, the smashed fixture, the pried-open supply line. Photograph everything, keep the damaged plumbing components, and note the police report number, since it establishes the malicious cause.
Speed also matters. Water from a claim like this can saturate subflooring, drywall, and insulation within hours, and Alamance County humidity accelerates mold growth. Policies require you to mitigate further damage, so emergency water extraction is both allowed and expected — keep every receipt, because reasonable mitigation costs are typically reimbursable.
Our team regularly handles losses where vandalism and water damage overlap in an Elon homeowners claim, and we make sure the carrier prices the full scope: drying, demolition, rebuild, contents, and any additional living expenses if the home is temporarily unlivable.
Do I Need A Police Report For A Vandalism Claim In Elon If The Vandals Were Never Caught?
Yes, you should always file a police report, even when there is little chance the person responsible will be identified. Most homeowners policies require you to notify law enforcement promptly after vandalism or malicious mischief, and skipping that step gives the insurance company an easy reason to question your claim.
In Elon, that usually means contacting the Town of Elon Police Department, or the Alamance County Sheriff’s Office if your property sits just outside town limits. Ask for the report number and a copy of the report itself. The document does not need to name a suspect to be useful — it establishes the date, the location, and an official record that the damage was reported as a crime.
Insurance companies do not require an arrest or conviction to pay a Vandalism Homeowners Claim Elon NC. Coverage turns on whether the damage was intentional and malicious, not on whether anyone was ever charged. Many vandalism cases in Alamance County are never solved, and homeowners are still entitled to have covered damage paid under their policies.
If the responding officer only issues an incident number without a full written report, keep that number and note the officer’s name and the date. Our team at For The Public Adjusters, Inc. can help you assemble the police documentation alongside photos, receipts, and a detailed damage inventory so the file the carrier receives is complete from the start.
Can I Clean Up The Mess Or Make Temporary Repairs Before The Insurance Company Inspects My Vandalized Home?
You can — and in some situations you must. Nearly every homeowners policy includes a duty to protect the property from further damage after a loss. If vandals broke windows or kicked in a door at your Elon home, boarding up openings, tarping exposed areas, and securing the house are reasonable emergency steps the insurer expects you to take.
The key is to document everything before you touch it. Photograph and video every damaged room, surface, and item from multiple angles, including wide shots that show the overall scene and close-ups that show the detail. Once that record exists, temporary repairs will not hurt your claim.
What you should avoid is permanent repair or disposal before the carrier’s adjuster has seen the damage or given written permission. Throwing out slashed furniture, repainting graffitied walls, or replacing a broken door removes the physical evidence the claim rests on. If something is a genuine safety hazard, photograph it thoroughly, then set it aside rather than discarding it if at all possible.
Keep every receipt for plywood, tarps, locksmith visits, and emergency labor. Those mitigation costs are typically reimbursable under the policy, but only if you can prove them. As a licensed and bonded public adjusting firm serving Elon and the rest of Alamance County, we routinely help homeowners separate what must be done immediately from what should wait, so nothing you do in the first stressful days weakens the claim later.
Is Graffiti Or Spray Paint Damage Covered Under A Vandalism Homeowners Claim Elon NC, And Will The Insurer Pay To Match My Siding Or Brick?
Graffiti and spray paint are classic examples of vandalism and malicious mischief, which standard homeowners policies in North Carolina cover. Paint on brick, vinyl siding, garage doors, and fences is physical damage to your property, and the cost to remove it — or to replace materials that cannot be cleaned — is generally a covered loss, subject to your deductible.
The real fight is usually over matching. Spray paint often cannot be fully removed from porous brick, and pressure-washing or chemical stripping can leave visible discoloration. On vinyl siding, replacement panels frequently fail to match sun-faded originals. Insurers sometimes offer to clean or replace only the tagged section, leaving your home with an obvious patchwork appearance.
A thorough claim pushes back with documentation: photos of the mismatch, manufacturer discontinuation evidence, and repair estimates that reflect what it actually takes to restore a uniform appearance. Whether an insurer must replace undamaged sections to achieve a reasonable match depends on your specific policy language, so having someone read it closely matters.
Courts have taken a broad view of what vandalism coverage protects. In Georgitsi Realty, LLC v. Penn-Star Insurance Co. (2013), the New York Court of Appeals sided with a building owner, holding that vandalism coverage can extend even to malicious property damage caused by conduct directed at a neighboring parcel. It is a reminder that policyholders who press their rights can prevail. We cannot promise any particular outcome, but we can make sure your Elon claim is documented and argued the way it deserves.
Does My Policy Cover Vandalism To Detached Structures, Fences, Landscaping, And Outdoor Items At My Elon Home?
In most cases, yes — but different parts of your policy apply, and the limits are not the same. A standard homeowners policy in North Carolina covers the dwelling under Coverage A, detached structures such as sheds, workshops, fences, and detached garages under Coverage B, and personal property like patio furniture, grills, and tools under Coverage C.
Coverage B is typically capped at ten percent of your dwelling limit, which surprises many homeowners after vandals destroy an expensive fence line or tear apart a workshop. Trees, shrubs, and landscaping usually carry their own sub-limit, often five percent of the dwelling coverage with a per-plant cap around five hundred dollars. If someone poisoned mature trees or ripped out established plantings on your Elon property, those sub-limits shape what the insurer will pay.
That makes an accurate, category-by-category damage inventory essential. Lumping everything together lets the carrier apply the lowest applicable limit, while a properly organized vandalism homeowners claim in Elon assigns each item to the correct coverage and maximizes what the policy actually provides.
Outdoor personal property also raises depreciation questions. A ten-year-old grill or weathered patio set will be valued far below replacement cost unless your policy includes replacement cost coverage and you follow the steps to recover the depreciation. For The Public Adjusters, Inc. reviews the full policy — declarations, endorsements, and sub-limits — before the claim is presented, so nothing covered gets left out and nothing gets miscategorized to your disadvantage.
Local Relevance
Elon is a college town at heart, and that shapes the vandalism losses we see in Alamance County. Homes near campus and along busy corridors deal with broken windows, damaged fences and mailboxes, and the occasional break-in — and many of those properties are rentals, where vacancy clauses and off-season empty months can complicate coverage.
The area’s housing mix matters too. Elon has everything from older homes with original wood windows and plaster walls to newer subdivisions, and repair costs vary widely between them. An insurer’s standard pricing rarely accounts for restoring older materials properly, which is where independent documentation earns its keep.
We work throughout Alamance County, including Vandalism Homeowners Claim Burlington losses just down the road, and our Public Adjuster Burlington team can typically inspect Elon properties quickly. The Insurance Information Institute notes that vandalism and malicious mischief are covered perils under standard homeowners policies — the fight is rarely about whether coverage exists, but about how much the insurer pays. That is the part we handle.
Because so many Elon-area homes are student rentals or investment properties that sit empty over summer and winter breaks, vacancy-related exclusions come up in local vandalism claims far more often than owners expect — documenting occupancy and reporting damage promptly tends to make or break these claims here.
Vandalism Damage In Elon? Get Your Claim Reviewed Before You Settle
Whether you just discovered the damage or you’re staring at a denial letter, a licensed and bonded public adjuster from For The Public Adjusters, Inc. will review your policy and your loss at no cost. You owe nothing unless we recover for you.
Call us: (336) 331-8300
Helpful Resources
- NCDOI Public Adjusters Guide
- Insurance Information Institute (III)
- North Carolina Department of Insurance consumer resources — State regulator’s guidance for policyholders
- Insurance Information Institute homeowners insurance basics — Plain-language explanation of what homeowners policies cover
Last updated: September 18, 2026