
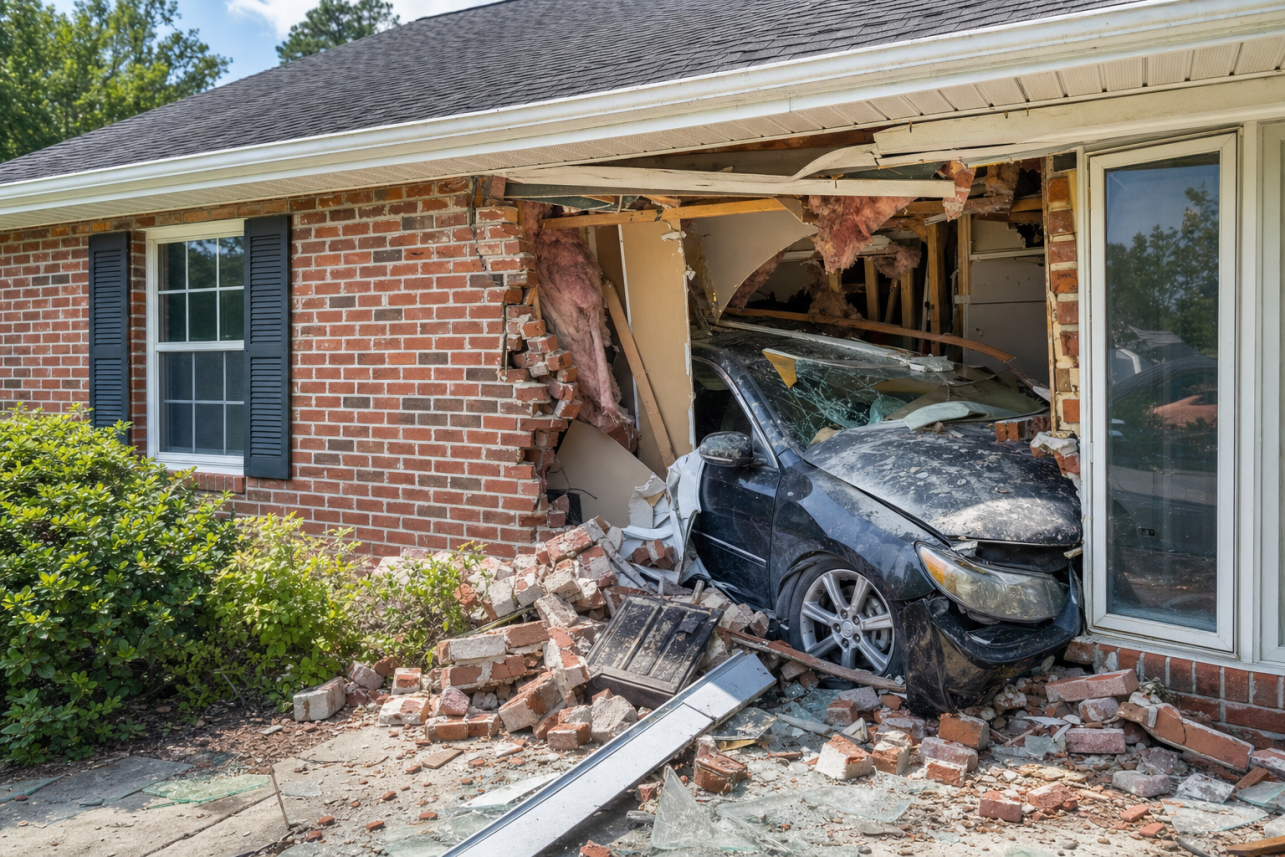
If you need help with a Car Hits Home Claim Elon NC, For The Public Adjusters, Inc. represents you — the homeowner — not the insurance companies, documenting the full structural damage and negotiating the settlement on your behalf. When a vehicle strikes a house, the driver’s auto policy and your homeowners policy often both come into play, and the two carriers can point at each other for weeks. We are licensed and bonded in North Carolina, and we manage that back-and-forth so the claim reflects what it actually costs to rebuild your home correctly.
What This Service Is
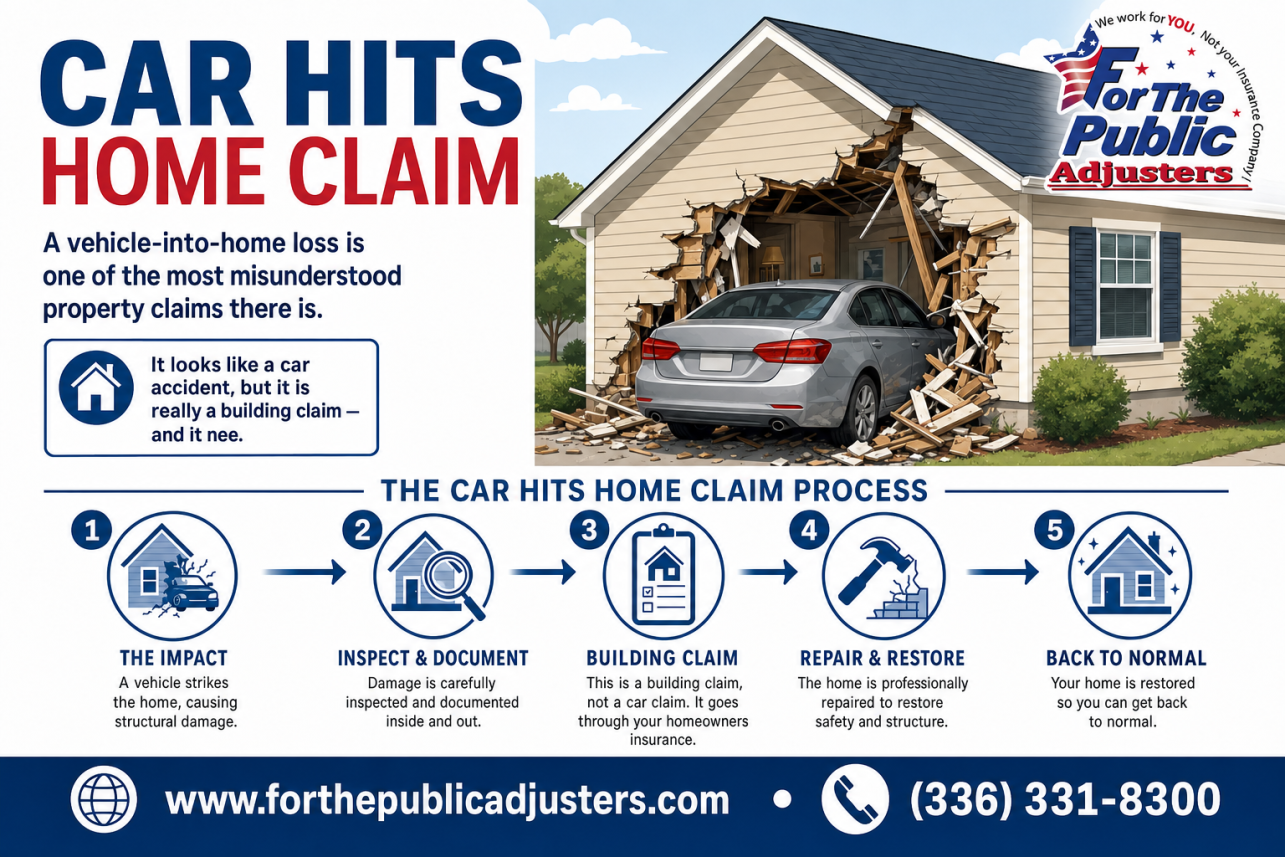
A vehicle-into-home loss is one of the most misunderstood property claims there is. It looks like a car accident, but it is really a building claim — and it needs to be handled that way. The impact rarely stops at the brick or siding you can see. Force travels through the wall into framing, headers, the foundation, plumbing, and wiring, and a repair estimate written from the driveway almost never captures that.
As public adjusters, we work only for policyholders. We inspect the structure, bring in the right specialists when a load-bearing wall or foundation may be compromised, prepare a detailed repair estimate, and present the claim to the insurance companies involved. That usually means your homeowners carrier first — because it pays fastest — while the at-fault driver’s auto insurer is pursued behind the scenes to reimburse your carrier and, importantly, your deductible.
We handle these losses across Alamance County. When a driver crashed into a home a few miles down the road, our Car Hit My House Insurance Claim Burlington work followed the same playbook: document everything, dispute nothing prematurely, and make sure hidden structural damage is priced in before anyone signs off. We also handle fire, water, smoke, and tree damage claims, so if the impact ruptured a water line or damaged a gas appliance, one team manages the whole loss.
Common Problems
Will The Settlement Actually Cover Rebuilding My Wall — Or Just Patching It?
This is where most vehicle-impact claims go wrong. The first estimate often prices a cosmetic fix: replace the damaged brick, patch the drywall, repaint. But if the impact shifted framing or cracked the foundation, a patch job leaves you with a structurally weakened home.
There is also the question of how you’re paid. Many policies initially pay actual cash value — the depreciated worth of old materials — and hold back the rest until repairs are done. If nobody explains that, homeowners accept the first check thinking it’s the whole settlement. Courts have pushed back on aggressive depreciation, too; in Sproull v. State Farm, the Illinois Supreme Court sided with the insured homeowner, ruling the carrier could not depreciate labor costs when paying a structural claim. We also flag code-upgrade costs — older Elon homes often must be rebuilt to current building code, and that added expense should be in the claim, not out of your pocket.
Two Insurance Companies Are Pointing At Each Other — What Do I Do While My House Sits Open?
The driver’s auto insurer will investigate fault before paying anything, and that can take weeks or months. Meanwhile you may have a hole in your house, emergency board-up costs, and possibly a home that isn’t safe to occupy. The practical answer is usually to file with your own homeowners carrier first; it owes you regardless of fault, and it later recovers its payout — a process called subrogation — from the at-fault driver’s insurer, including your deductible in most cases.
Problems come when your own carrier delays, lowballs the repair cost, or denies parts of the claim. If your home is declared unlivable, your loss of use coverage should pay temporary housing and the extra daily costs of being displaced — but only if those expenses are documented and claimed. We track every receipt, push both carriers on timelines, and handle disputes the same way our Car Hits Home Insurance Claim Durham clients have seen: with a documented, defensible file the carrier can’t easily brush aside.
Do I Really Need A Public Adjuster For A Car Hits Home Claim Elon NC?
If the damage is a dented gutter, probably not. But if a vehicle actually breached your wall, porch, or garage, the claim involves structural assessment, two insurance companies, depreciation math, and code requirements — and the insurance company’s adjuster works for the insurance company, not you. A public adjuster is the only type of adjuster licensed to represent the policyholder.
The NCDOI Public Adjusters Guide is worth reading before you hire anyone: North Carolina requires public adjusters to be licensed, and you can verify a license before signing anything. Ask any adjuster you interview how many vehicle-impact claims they’ve handled, whether they’ll coordinate structural engineers, and how they pursue the auto carrier. We’ve handled these losses across the Triangle and Triad, including a Car Hit My House Insurance Claim in Cary, and we never guarantee a specific dollar outcome — no honest adjuster can — but we do guarantee your claim will be fully documented and professionally presented.
Our Process
Emergency Documentation And Securing The Home
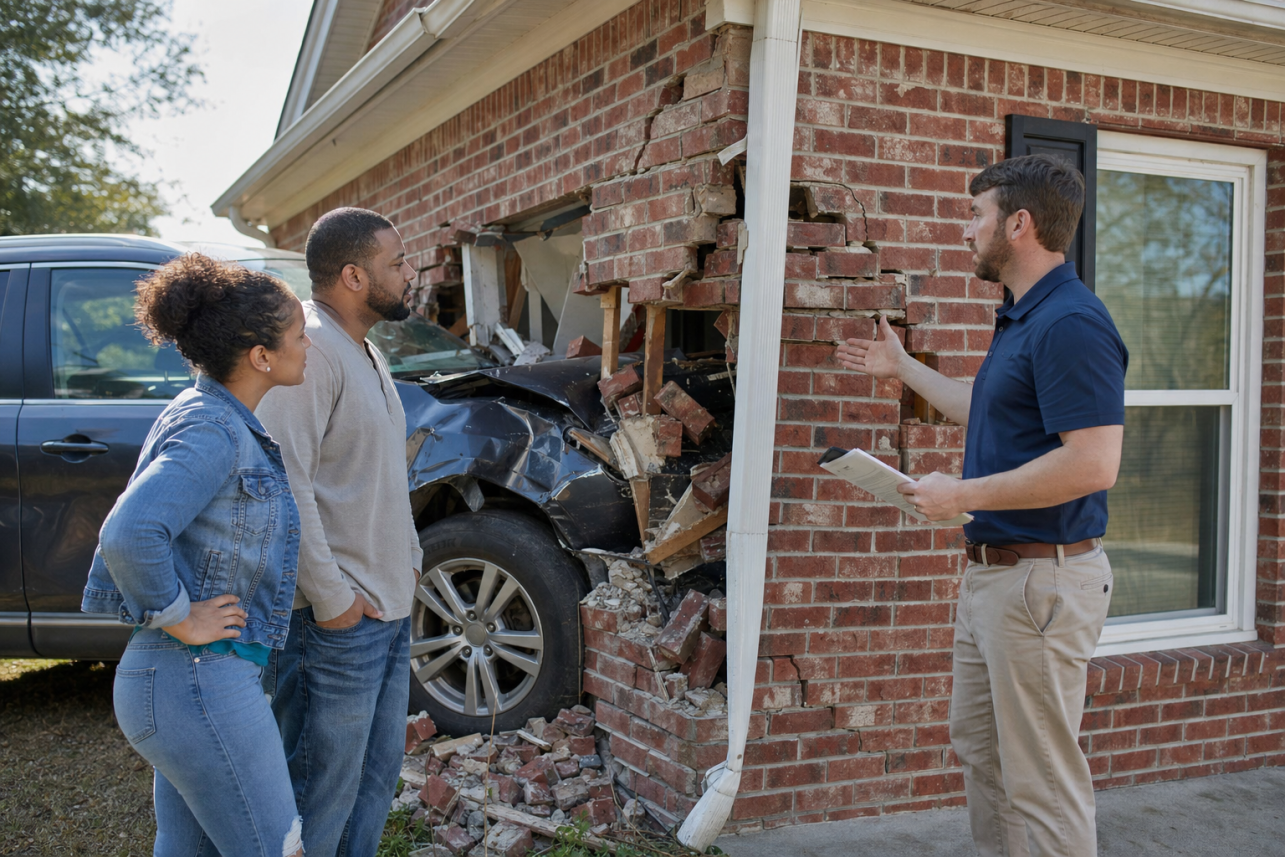
We photograph and document everything before cleanup disturbs the scene — the vehicle’s point of impact, debris field, interior cracking, and any shifted framing. We make sure emergency board-up and tarping costs are captured as part of the claim, and we help you get the police report, which establishes the at-fault driver and their insurance information.
Full Structural Damage Assessment
A vehicle impact transfers force well beyond the visible hole. We evaluate the foundation, load-bearing walls, roof connections, and any plumbing or electrical in the wall path, bringing in structural engineers when warranted. Then we build a line-by-line repair estimate that reflects what a real contractor would charge to restore the home — including required code upgrades — not what a quick drive-by estimate assumes.
Presenting The Claim And Coordinating Both Carriers
We file and negotiate with your homeowners carrier, respond to their adjuster’s pushback with documentation, and track the subrogation against the driver’s auto insurer so your deductible comes back when it should. If the carrier underpays or denies covered damage, we escalate the dispute — and if it reaches the point of litigation, we work alongside insurance dispute attorneys so nothing is lost in handoff.
| What Happens | Homeowner Alone | With For The Public Adjusters |
|---|---|---|
| Damage scope | Carrier estimates visible damage — brick, siding, drywall | Engineer-backed inspection of framing, foundation, roof load path, and utilities |
| Two-insurer coordination | Homeowners and auto liability carriers stall while pointing at each other | Homeowners policy pursued first, subrogation documented against the driver’s carrier |
| Matching materials | Patch repairs that leave mismatched brick or siding | Full-elevation matching argued from policy language and case law like Windridge v. Philadelphia Indemnity |
| Displacement costs | ALE or Fair Rental Value often underpaid or cut off early | Coverage documented through the real repair timeline |
| Code upgrades | Ordinance-or-law coverage frequently never mentioned | Code-required electrical, gas, and structural upgrades included in the scope |
| Who negotiates | You, against a trained company adjuster | A licensed and bonded public adjuster who works only for you |
Commonly Overlooked In The Public Adjusting Industry
- Racked wall framing beyond the point of impact — Impact force travels laterally through top plates and headers, so studs six feet from the hole can be cracked while the drywall over them looks fine.
- Foundation and sill plate displacement — Carrier adjusters rarely put a level on the floor system, and a half-inch shift at the sill hides until doors start sticking months later.
- Cracked or shifted roof trusses above the strike zone — Nobody thinks to look up after a car hits a wall, but the load path carries the blow straight into the roof structure.
- Ordinance-or-law coverage for code upgrades — Rebuilding the damaged wall in Elon triggers current Alamance County code requirements, and carriers seldom volunteer the coverage that pays for them.
- Signing the at-fault driver’s insurer release too early — A quick liability check feels like a win until hidden structural damage surfaces after the release has closed the door on further recovery.
- Matching brick, siding, or stone across the full elevation — Insurers price a patch, but a mismatched front wall is a real loss in value — and the insured prevailed on exactly this issue in Windridge v. Philadelphia Indemnity.
- Gas and electrical connections inside the damaged wall — A struck wall often contains wiring and gas piping that need inspection and re-permitting, which the first estimate almost never includes.
- Additional Living Expenses cut off before repairs finish — Adjusters approve a short displacement window up front, and homeowners don’t realize the coverage should run through the actual, documented repair timeline.
Case Studies
Case Study #1
Situation: A retired couple on Williamson Avenue in Elon woke at 2 a.m. to a pickup truck resting inside their living room. The driver had left the roadway, sheared a porch column, and pushed through the brick veneer and front wall framing.
Problem: Their homeowners carrier issued a quick estimate of $18,400 covering only the visible brick and drywall. It ignored the racked front wall, cracked sill plate, and shifted roof load path. The couple was also told to wait on the driver’s auto liability carrier, which stalled everything for weeks while the house sat open to weather.
Investigation: Our team brought in a structural engineer within days of being hired. We documented the impact path with photos, laser-level readings on the floor system, and moisture logs from the tarped opening. We also pulled the framing apart at the point of impact rather than accepting a surface-level scope.
Findings: The engineer confirmed the impact had transferred force through the header into the roof trusses, two of which were cracked. The foundation wall below the impact point was displaced nearly an inch. The carrier’s estimate had priced a cosmetic patch on a structural injury.
Solution: We rewrote the scope to include full front-wall reframing, foundation repair, truss replacement, matching brick across the elevation, code-required upgrades, and Additional Living Expenses for the months the home was unsafe. We pursued the homeowners policy first so repairs could move, then coordinated subrogation documentation against the at-fault driver’s insurer.
Outcome: The claim settled at more than four times the original estimate, funding a proper structural rebuild rather than a patch. The couple’s ALE covered a rental in Burlington through the reconstruction. As always, results depend on the policy and the facts — no two claims resolve the same way.
Lesson: When a vehicle strikes a house, the damage almost never stops where the paint scrapes stop. Courts have recognized how far these disputes can go: in Windridge of Naperville Condominium Association v. Philadelphia Indemnity Insurance Co. (7th Cir. 2019), the property owner won when the court held the insurer had to replace undamaged siding so the building matched — a principle that matters when a car destroys only part of a brick or siding elevation.
Case Study #2
Situation: A landlord who owns a rental duplex near the Elon University area had a sedan jump the curb and strike the corner of the building, cracking the gas meter connection and buckling the exterior wall of one unit.
Problem: The insurer accepted the claim but classified the tenants’ displacement as the tenants’ problem, lowballed the loss-of-rents coverage, and priced the wall repair with new siding that did not match the rest of the aging building. The gas line disruption and required inspections were left out of the estimate entirely.
Investigation: We reviewed the landlord’s dwelling policy line by line, including the Fair Rental Value provision and ordinance-or-law coverage. We obtained the police crash report, the gas utility’s shutoff documentation, and repair bids from two Alamance County general contractors instead of relying on the carrier’s preferred vendor.
Findings: The policy’s Fair Rental Value coverage applied for the full period the unit was uninhabitable, not the arbitrary 30 days the adjuster had allowed. Ordinance-or-law coverage triggered code upgrades to the electrical and gas connections in the damaged wall. The mismatched-siding issue was a legitimate scope dispute, not a take-it-or-leave-it item.
Solution: We presented a documented demand covering the full reconstruction scope, code upgrades, gas system inspection and re-piping, matching siding across the affected elevation, and lost rent through the actual repair timeline. Every line item was tied to a policy provision or a contractor bid.
Outcome: The carrier reissued payment at roughly triple its first figure and extended Fair Rental Value through completion. The landlord kept both tenants by crediting rent during displacement. Outcomes vary with each policy and loss, and we never promise a specific result.
Lesson: Landlord policies hide real money in Fair Rental Value and ordinance-or-law coverage, and insurers rarely volunteer it. The insured’s win in Salesin v. State Farm Fire & Casualty Co. (Mich. Ct. App. 1998) is a useful reminder that courts will hold carriers to the actual language of a property policy when a building owner pushes back with documentation.
| Situation | What To Do | Why It Matters |
|---|---|---|
| Wall or foundation was hit | Do not re-enter or repair until an engineer clears the structure | Impact force travels into framing and footings far beyond the visible hole |
| Gas, electric, or water lines near the impact | Call the utility for shutoff and inspection before any cleanup | A cracked gas fitting behind a wall can leak for weeks unnoticed |
| Driver’s insurer offers a fast check | Do not sign a release before the full structural scope is known | A release can bar you from recovering for hidden damage found later |
| Your carrier says wait on the auto insurer | File under your own homeowners policy immediately | Your policy owes you now; the carriers sort out subrogation afterward |
| Home is unsafe to occupy | Keep every receipt for lodging, meals, and mileage | Additional Living Expenses coverage pays documented costs, not estimates |
| Police responded to the crash | Request the crash report from Elon PD or Alamance County Sheriff | The report establishes fault and the driver’s insurance information |
| Only part of the brick or siding is damaged | Photograph the full elevation before any repairs begin | Matching disputes are common, and courts have sided with owners who documented mismatch |
| Carrier’s estimate feels thin | Get an independent review before accepting | First estimates on vehicle-impact losses routinely price cosmetic fixes for structural injuries |

Reviews
A drunk driver put his SUV through my garage wall on a Saturday night. My insurance company offered enough to fix the brick and nothing else. For The Public Adjusters found cracked studs, a bent garage door track, and foundation damage their adjuster never looked at. The final settlement covered a real rebuild, not a cover-up. They also handled every call with the driver’s insurance so I didn’t have to.
Marcus T., Elon NC
After a car hit the corner of our house off NC-100, we had two insurance companies pointing at each other for a month. This team took over, got our homeowners policy moving first, and documented everything for the claim against the driver. They caught that our floor had shifted, which the first estimate completely missed. Worth every penny of their fee.
Denise W., Alamance County
The vehicle that hit our home also knocked the porch off level and cracked the chimney, but the carrier’s estimate only mentioned siding. Our public adjuster in Elon brought in an engineer, rewrote the whole scope, and got us temporary housing money while the front of the house was open. Four stars only because the process still took a few months — but that was the insurance company dragging, not them.
James and Carol P., Elon
Frequently Asked Questions
What Does A Car Hits Home Claim Elon NC Actually Cover Under My Homeowners Policy?
When a vehicle strikes your house, your homeowners policy typically covers the resulting structural damage — cracked brick veneer, shifted foundation walls, broken framing, damaged porches, garage doors, plumbing lines inside the wall, and any personal property destroyed in the impact. Vehicle impact is a named peril on nearly every HO-2 and HO-3 policy sold in North Carolina, so coverage for the dwelling itself is rarely the dispute.
The dispute is almost always about scope and price. Insurers frequently write estimates for surface repairs — patch the brick, replace a few studs — while ignoring hidden damage like racked wall plates, compromised footings, or torn sill plates that only show up when a contractor opens the wall.
A Car Hits Home Claim Elon NC also raises the question of who pays: your carrier, or the driver’s liability insurer. Often your homeowners carrier pays first and then pursues subrogation against the at-fault driver. That can work in your favor, because your deductible may be reimbursed later.
One important note about our role: For The Public Adjusters, Inc. handles the damage to your home, other structures, and contents only. We do not handle claims for the vehicle itself, or any auto, health, or life coverage — those stay with the respective carriers. Our licensed and bonded team focuses entirely on documenting and negotiating the building and contents portion so the settlement reflects what it actually costs to restore your Elon home.
The Insurance Company’s Estimate Seems Too Low To Repair My Elon Home. Can I Push Back?
Yes, and homeowners push back successfully all the time. Carriers often estimate vehicle-impact damage as cosmetic — a brick patch and some paint — when the force of a car hitting a load-bearing wall can shift framing, crack foundations, and disturb utilities behind the wall. In older Alamance County homes with brick veneer and crawlspace foundations, hidden structural movement is common.
Matching materials is another frequent fight. If your 1990s brick or siding is discontinued, the carrier may offer to replace only the damaged section, leaving a visible mismatch on the front of your house. Courts have sided with policyholders on this issue. In Windridge of Naperville Condominium Association v. Philadelphia Indemnity Insurance Co. (7th Cir. 2019), the court ruled the insurer had to replace siding on all elevations of the damaged buildings — not just the struck portions — because a patchwork repair would not restore the property to its pre-loss condition. That reasoning is a powerful reference point when a carrier tries to leave you with mismatched masonry.
As your public adjuster in Elon, we prepare an independent line-item estimate, bring in structural documentation where needed, and negotiate directly with the carrier’s adjuster. We cannot guarantee any specific outcome or dollar amount — no one legitimately can — but we can make sure every element of the loss is documented, priced at local Alamance County repair costs, and formally presented before you accept a settlement.
Whose Insurance Pays When A Driver Crashes Into My House — Mine Or Theirs?
Both policies can come into play, and the order matters. You can file against the at-fault driver’s auto liability coverage, file under your own homeowners policy, or do both. Most Elon homeowners are better served filing with their own carrier first, because homeowners claims usually move faster than waiting on a liability investigation, fault determination, and the driver’s insurer agreeing to pay.
North Carolina’s minimum property damage liability limit is often too low to cover serious structural damage. If a car takes out a corner of your foundation or destroys a garage, repair costs can easily exceed the driver’s limits. Your homeowners policy fills that gap, and your carrier can then subrogate — pursue the driver’s insurer for reimbursement — which may return your deductible to you.
What you should not do is let the driver’s insurance company control the repair scope. Their adjuster works for the driver’s carrier, and their goal is to close the file inexpensively. You are under no obligation to accept their first offer or use their preferred contractor.
Our team represents you, the property owner, on the building and contents damage. We document the full loss, coordinate the homeowners claim, and make sure the file supports subrogation so cost-shifting between insurers does not shortchange your repairs. To be clear on scope: we handle the home and contents portion only, never the vehicle or any auto coverage questions, and we never guarantee a specific recovery — we work to present the strongest, most complete claim possible.
How Does A Car Hits Home Claim Elon NC Work With For The Public Adjusters, And When Should I Call?
Call as early as you can — ideally before the carrier’s adjuster inspects. The first inspection sets the tone for the entire claim, and vehicle-impact losses are notorious for damage that is missed on a quick walkthrough: cracked footings, shifted framing above the impact point, damaged wiring or plumbing inside walls, and contents crushed or knocked over deep inside the home.
Here is how the process works. We start with a free review of your policy and the damage. Then we perform our own detailed inspection, photographing and measuring everything from the point of impact through the load path of the structure. We build an independent, line-item estimate using current Alamance County labor and material pricing, inventory your damaged contents, and calculate any additional living expense coverage if the home is unsafe to occupy.
From there, we handle the negotiation. We meet the carrier’s adjuster on site, walk them through the documentation, and respond to every lowball position in writing. If matching brick or siding becomes an issue, we lean on established policyholder-friendly case law, such as the Windridge decision requiring insurers to restore a uniform appearance rather than a visible patch.
For The Public Adjusters, Inc. is licensed and bonded in North Carolina, and we work on the building and contents claim only — never the vehicle. We make no promises about specific settlement figures, because ethical adjusters never do. What we commit to is a thoroughly documented Car Hits Home Claim Elon NC homeowners can stand behind, presented by a team that knows how these losses get underpaid.
How Long Does A Car Hits Home Claim Elon NC Typically Take To Resolve?
A Car Hits Home Claim Elon NC can settle in as little as 30 to 60 days when the damage is limited to a porch column or a section of brick veneer, but structural impacts often take three to six months or longer. The biggest variable is whether the vehicle compromised load-bearing elements, which usually requires a structural engineer’s report before the insurer will approve a full scope of repairs.
Under North Carolina law, insurers must acknowledge your claim promptly and act in good faith, but there is no strict statutory deadline forcing a payout on a set date. Delays commonly happen when the carrier waits on subrogation against the driver’s auto liability policy, or when the first estimate misses hidden damage behind drywall and framing.
In our experience with Elon and greater Alamance County homes, older houses near downtown and the university area often have brick or trim that is hard to match, and that alone can add weeks of back-and-forth over whether the insurer owes for matching materials. Getting a complete, well-documented scope in front of the adjuster early is the single best way to shorten the timeline.
We cannot promise a specific settlement amount or date — no one honestly can — but a properly built claim file with engineering support, itemized estimates, and code-upgrade documentation typically moves through review faster than a homeowner-submitted claim with gaps the carrier has to question.
The Driver Who Hit My Elon House Was Uninsured Or Fled The Scene. What Happens To My Claim?
You are not out of luck. Your own homeowners policy covers vehicle impact damage to your dwelling regardless of whether the driver is identified, insured, or cooperative. You would file under your own coverage, pay your deductible, and let your insurer pursue the driver later if one is ever found.
In a hit-and-run, document everything immediately: call the Elon Police Department or the Alamance County Sheriff’s Office to get an official report, photograph tire marks, paint transfer, and debris, and note any doorbell or security camera footage before it’s overwritten. That report number matters — insurers scrutinize claims without one.
If your insurer later recovers money from the at-fault driver through subrogation, you may be reimbursed for some or all of your deductible. That recovery is never certain, especially with an uninsured driver, so build your claim on your own policy’s dwelling and other-structures coverage from day one.
One important note: as public adjusters, we handle the damage to your home, detached garage, fencing, landscaping structures, and personal contents inside the house. We do not handle motor vehicle claims of any kind, so damage to your own parked car in the driveway would go through your auto carrier separately. For The Public Adjusters, Inc. is licensed and bonded in North Carolina, and we work exclusively on the property side — making sure the structural, cosmetic, and contents damage to your Elon home is fully scoped and fairly presented.
Will My Insurer Pay For Building Code Upgrades And Matching Brick Or Siding After A Vehicle Impact In Elon?
Often yes, but rarely without a fight. Many Elon homes — particularly older properties in established neighborhoods off Haggard Avenue and around the university — were built under earlier codes. When a car destroys a wall section, Alamance County and Town of Elon inspections may require the rebuilt portion to meet current code: updated framing connections, electrical work, or insulation. If your policy includes Ordinance or Law coverage, those upgrade costs should be part of your claim, and adjusters frequently omit them from first estimates.
Matching is the other battleground. If your 1990s brick or discontinued vinyl siding can’t be matched, a patch repair leaves a visible mismatch. Courts have sided with policyholders on this issue. In Windridge of Naperville Condominium Association v. Philadelphia Indemnity Insurance Co. (7th Cir. 2019), the insurer wanted to replace only storm-damaged siding on some building elevations; the court ruled the policyholder was entitled to replacement of all the siding so the buildings would match, because a two-tone repair was not a true restoration.
That reasoning applies directly to vehicle-impact damage: if the insurer can’t reasonably match your brick, stone, or siding, the argument exists that a larger replacement area is owed. Whether your specific policy supports it depends on its wording, and we never guarantee an outcome — but these are exactly the coverage questions a public adjuster is trained to identify, document, and negotiate rather than letting them quietly disappear from the estimate.
What Should I Document Before Repairs Begin On A Car Hits Home Claim Elon NC?
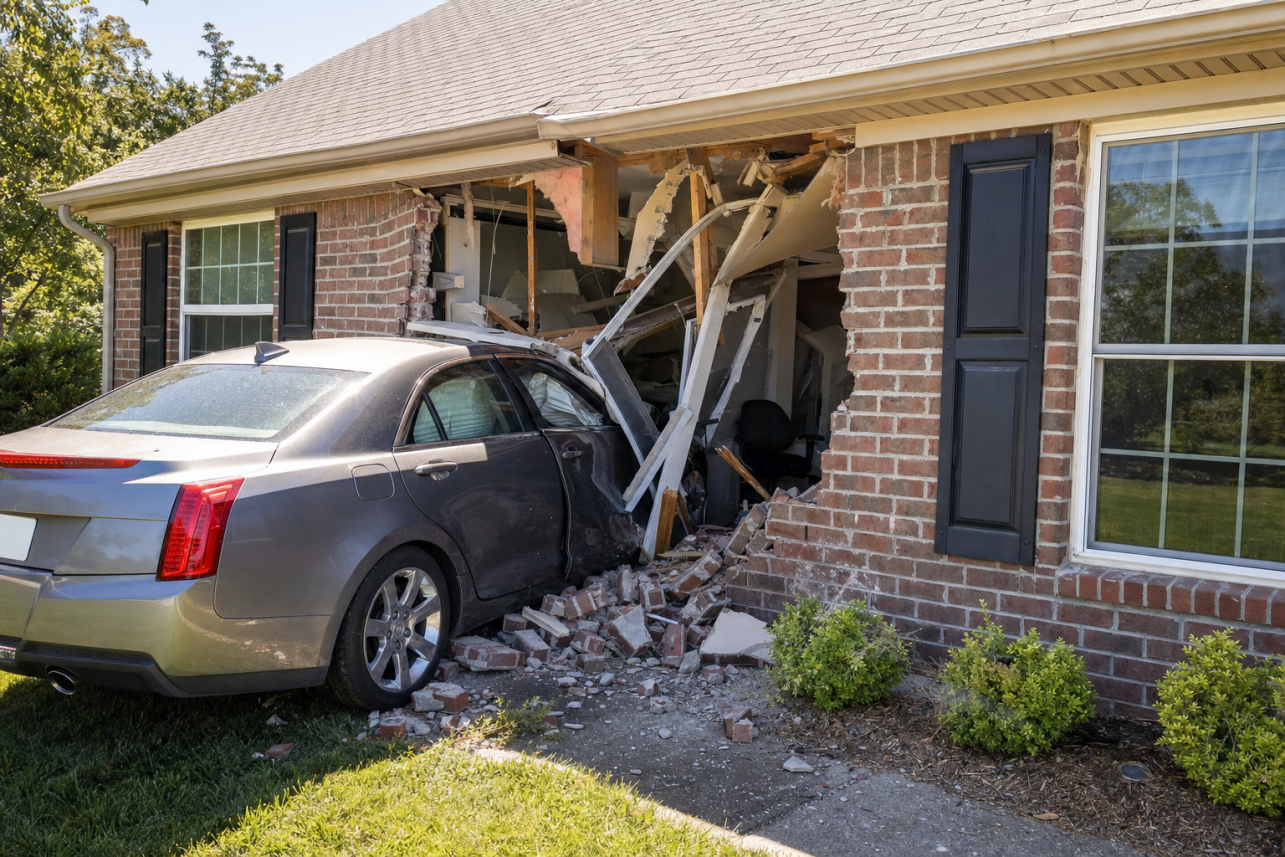
For a Car Hits Home Claim Elon NC, documentation gathered in the first 48 hours often determines how the entire claim goes. Before anything is moved or boarded up, photograph the vehicle’s position (if still there), the point of impact, cracked foundation or brick, shifted framing, broken windows, and every damaged item inside — furniture, electronics, flooring, and anything crushed or knocked over.
Get the police report number, the driver’s name and auto insurance information if available, and contact details for any witnesses. Then take wider shots showing the whole elevation of the house, because insurers sometimes argue that pre-existing cracks or settling caused damage the car actually inflicted.
Emergency stabilization is fine — in fact, your policy requires you to prevent further damage, so temporary shoring, tarping, and board-up are appropriate and reimbursable. Keep every receipt. What you should not do is authorize permanent repairs before the full scope is agreed on, because rebuilt walls hide the very evidence that supports your claim.
Insureds who document well and stand firm tend to fare better, even in court. In Mosley v. Pacific Specialty Insurance Co. (9th Cir. 2020), homeowners whose house was severely damaged fought their insurer’s denial all the way up on appeal, and the court ruled the carrier could not escape coverage on the facts presented — the policyholders’ persistence and record kept the claim alive. We help Elon homeowners build that same kind of thorough, defensible file from day one, before the insurer’s adjuster ever writes the first estimate.
How Much Does It Cost To Hire A Public Adjuster For A Car Hits Home Claim Elon NC?
For The Public Adjusters, Inc. works on a contingency-fee basis, which means our fee is a percentage of the insurance settlement rather than an upfront charge. If the claim doesn’t pay, you don’t owe us an adjusting fee. That structure keeps our interests aligned with yours from the first inspection to the final check.
North Carolina regulates public adjusters, and we are fully licensed and bonded to represent policyholders in Elon and throughout Alamance County. Before any work begins, you’ll receive a written agreement that spells out the fee percentage and the scope of what we handle, so there are no surprises.
Homeowners sometimes worry the fee will leave them short on repair money. In practice, vehicle-impact claims are frequently underscoped — carriers may miss cracked foundation footings, racked framing behind the point of impact, or damaged plumbing and electrical runs inside the wall cavity. When those items are properly documented and included, the adjusted settlement often reflects the true cost of repairs far more accurately than the initial estimate did.
We can’t promise a specific dollar outcome — no honest adjuster can — but we can promise a thorough, professionally documented claim presented under the actual terms of your policy. For most Elon homeowners dealing with a car through the wall of their house, that thoroughness is exactly what was missing from the carrier’s first offer.
Can I Choose My Own Contractor To Repair Vehicle-Impact Damage To My Elon Home, Or Must I Use The Insurer’s Preferred Vendor?
In North Carolina, you have the right to choose your own contractor. Your homeowners policy obligates the carrier to pay for covered repairs; it does not give the carrier authority to dictate who performs them. Insurers often steer policyholders toward preferred vendor programs, and while some of those contractors do fine work, they answer to the insurance company’s pricing agreements — not to you.
For a car-into-house loss, contractor selection matters more than most people realize. These repairs frequently involve structural engineering, foundation work, load-bearing wall reconstruction, and matching existing brick or siding on older Elon homes. A general handyman working from the carrier’s line-item estimate may not catch shifted framing or compromised headers that a structural repair specialist would flag immediately.
Our role as your public adjuster is to make sure the insurance estimate matches the real scope your chosen contractor identifies. When there’s a gap between the carrier’s numbers and legitimate repair costs, we document the difference with photos, measurements, engineering reports, and current local pricing, then negotiate the supplement.
Courts have backed policyholders on scope disputes. In Sproull v. State Farm Fire & Casualty Co. (Illinois Supreme Court, 2021), the insured won a ruling that the carrier could not depreciate labor costs when calculating a property payout — a decision that put real money back in homeowners’ pockets. It’s a good reminder that the carrier’s first calculation isn’t the final word.
Will My Homeowners Policy Pay For A Hotel Or Rental If The Crash Makes My Elon House Unsafe To Live In?
Most standard homeowners policies include Additional Living Expenses coverage, often called ALE or Loss of Use. If a vehicle strikes your home and the damage makes it uninhabitable — a breached exterior wall, compromised structural support, severed gas or electrical service — ALE pays the reasonable increase in your living costs while repairs are underway.
That typically includes a hotel or short-term rental in the Elon or Burlington area, extra mileage if you’re displaced farther from work or Elon University, restaurant meals above your normal grocery spending, pet boarding, and sometimes storage for furniture moved out during reconstruction. The key phrase is “increase”: the carrier pays the difference between your normal expenses and your displaced expenses.
Two things trip homeowners up. First, carriers sometimes declare a house “habitable” too quickly, even with plywood over a hole in the living room and no functioning HVAC in January. Second, families fail to keep receipts, and undocumented expenses are hard to recover later. Save everything from day one, including gas and food receipts.
We review the habitability question independently, document conditions like exposed wall cavities, temporary shoring posts, or construction dust affecting air quality, and present ALE claims with the same rigor as the structural claim itself. If your family is displaced longer than the carrier initially projected — which happens often when hidden foundation or framing damage is discovered — we pursue the extension of those benefits under your policy’s terms.
The Claim Was Already Paid, But My Contractor Found More Damage. Can A Car Hits Home Claim Elon NC Be Reopened?
Yes — in most cases a Car Hits Home Claim Elon NC can be supplemented after the initial payment when repairs uncover damage the original estimate missed. This is extremely common with vehicle impacts. Once a contractor opens the wall, they often find cracked sill plates, shifted piers, sheared anchor bolts, crushed ductwork, or plumbing damage that no adjuster could see from the outside.
The mechanism is called a supplemental claim. You are not asking the carrier for a favor; you are asking it to pay for covered damage under the policy it sold you. The insurer will typically send an adjuster back out, and the quality of your documentation determines how that reinspection goes. Photograph everything before it’s covered back up, keep the contractor’s written findings, and get the discovery in front of the carrier promptly.
Watch your deadlines. North Carolina policies contain time limits for submitting proof of loss and filing suit, so hidden damage found months into a rebuild still needs to be reported without delay.
Policyholders who push back on incomplete payments have prevailed in court. In Sproull v. State Farm (2021), the insured challenged how the carrier calculated actual cash value on a home damaged by hail, and the state’s highest court ruled the insurer could not withhold labor depreciation from the payment. We bring that same principle to supplemental negotiations for Elon homeowners: the policy language controls, and we hold the carrier to it — thoroughly documented, professionally presented, with no shortcuts.
Will Filing A Car Hits Home Claim Elon NC Raise My Homeowners Premium Even Though I Wasn’t At Fault?
It’s a fair worry, and the honest answer is: it depends on your carrier, but a not-at-fault vehicle-impact loss is treated very differently from a claim you caused. Most insurers in North Carolina distinguish between claims where you had no control — like a driver leaving South Church Avenue and striking your porch — and losses tied to maintenance or negligence.
What matters most is subrogation. When your homeowners carrier pays for the repairs and then recovers that money from the at-fault driver’s auto liability insurer, many companies will not count the loss against you the same way, because they were made whole. Part of our job on a Car Hits Home Claim Elon NC is making sure the file clearly documents that the loss was caused by a third party, which supports that recovery.
We also see Elon and Alamance County homeowners avoid filing at all out of fear, then accept a lowball offer directly from the driver’s insurer. That’s usually the more expensive mistake. Courts have repeatedly sided with policyholders who held insurers to the full scope of structural damage — in Windridge of Naperville Condominium Association v. Philadelphia Indemnity Insurance Co., 932 F.3d 1035 (7th Cir. 2019), the building owner won when the court ruled the insurer had to replace undamaged siding so the repaired building would actually match.
We’re licensed and bonded, and while no one can promise a specific outcome, we can make sure fear of a premium hike never pressures you into settling for less than your policy allows.
The Car Damaged My Fence, Garage, And Landscaping Too — Is All Of That Part Of The Claim?
In most cases, yes. A standard North Carolina homeowners policy covers more than the dwelling itself. Coverage B, often called “Other Structures,” typically applies to detached garages, fences, sheds, retaining walls, and similar structures on your Elon property, usually at 10% of your dwelling limit.
Landscaping is trickier but often covered. Many policies include a specific allowance for trees, shrubs, and plants damaged by a vehicle not owned or operated by a resident of your household — commonly around 5% of the dwelling limit, with a per-item cap. If a driver plowed through your azaleas and split-rail fence before hitting the garage, those items belong in the estimate.
The problem we see on vehicle-impact losses in Alamance County is that adjusters focus on the obvious hole in the structure and skim past everything else. Cracked concrete driveways, bent gutters, shifted fence posts three sections away from the impact point, damaged irrigation lines — these get missed or lumped into a token allowance.
When we handle a claim after a car hits a home in Elon, we scope the entire path of the vehicle, from where it left the road to where it stopped. Everything it touched gets photographed, measured, and priced. One note on what we don’t do: damage to the vehicle itself is an auto claim, which is outside our practice. Our work is your home, your other structures, and your contents — and making sure every damaged item on your property is actually in the paperwork.
How Do I Know If A Car Hits Home Claim Elon NC Includes Hidden Structural Damage Behind The Wall?
Vehicle impacts are deceptive. A pickup that clips a brick corner at 30 mph can transfer force through the wall into the framing, sill plate, and even the foundation — damage you’ll never see from the curb. On a Car Hits Home Claim Elon NC, insisting on a look behind the finishes is often the difference between a real settlement and a cosmetic patch.
Warning signs include doors and windows near the impact that suddenly stick, new drywall cracks radiating from corners, gaps at baseboards, or floors that feel slightly out of level. Many of the homes around Elon — older brick ranches and pier-and-beam houses near downtown and the university area — are especially vulnerable to hidden load-path damage because the masonry hides what happened to the structure behind it.
We routinely bring in structural engineers on impact losses, and the cost of that inspection is frequently a covered claim expense. An engineer’s report carries weight the insurer can’t easily dismiss. Courts back this up: in Windridge of Naperville v. Philadelphia Indemnity, 932 F.3d 1035 (7th Cir. 2019), the policyholder won because the court held the insurer couldn’t limit repairs to a narrow patch when a proper repair required more.
If the carrier’s adjuster spent twenty minutes at your house and never opened a wall, the estimate is almost certainly incomplete. We can’t guarantee any particular result, but we can guarantee the damage gets properly investigated before you sign anything.

Do I Have To Give A Recorded Statement To The Insurance Company After A Vehicle Crashes Into My Elon House?
It depends on whose insurer is asking. If it’s the at-fault driver’s auto liability carrier, you have no contractual obligation to give them a recorded statement at all. They represent the driver, not you, and their questions are often designed to minimize what they’ll pay for your home.
If it’s your own homeowners insurer, your policy’s “duties after loss” section likely requires reasonable cooperation, which can include a statement or an examination under oath. Refusing outright can jeopardize coverage — but you’re entitled to prepare, to have representation, and to answer accurately without speculating about things like the home’s pre-loss condition or repair costs you haven’t verified.
This is one of the most valuable moments to have an Elon public adjuster already involved. Innocent guesses — “the porch was probably a little worn anyway” — get quoted back later to justify depreciation or partial denials. We help Alamance County policyholders understand what a question is really asking before they answer it.
Policyholders who push back on carrier tactics do win. In Salesin v. State Farm Fire & Casualty Co., 229 Mich. App. 346 (1998), the homeowner prevailed against the insurer over how the claim was handled and valued, and the court refused to let the carrier use its own process to shortchange the insured.
For The Public Adjusters, Inc. is licensed and bonded, and we sit beside you through statements, inspections, and negotiations so nothing you say gets twisted into a smaller check.
Local Relevance
Elon has grown fast, and that growth means more traffic moving through what were once quiet residential corridors. Many homes in and around the university area sit close to the road — older brick ranches and mill-era houses with shallow setbacks — which puts front walls, porches, and garages directly in the path of a driver who loses control, especially on wet winter mornings when black ice catches drivers off guard in the Piedmont.
Older Alamance County construction adds a wrinkle: homes built decades ago often can’t legally be repaired back to their original condition. Current building code may require upgraded framing, electrical, or foundation work, and those costs belong in the claim. The National Association of Insurance Commissioners encourages policyholders to review exactly this kind of coverage — often called ordinance or law coverage — because it’s the difference between a complete rebuild and a large out-of-pocket bill.
We serve all of Alamance County from Elon and Gibsonville to Graham, and our Public Adjuster Mebane NC team covers the eastern end of the county. Whether the loss is a vehicle impact, a kitchen fire, or a fallen oak — like the Tree Damage Home Insurance Claim in Mebane losses we see after Piedmont storms — the goal is the same: a settlement that pays for the repair your home actually needs.
Many homes in Elon’s older neighborhoods were built with unreinforced brick veneer over wood framing and sit unusually close to the street, so a vehicle strike that looks like a masonry repair often turns out to involve cracked studs and shifted sill plates behind the brick — damage that only shows up when someone opens the wall before the estimate is finalized.
A Car Crashed Into Your Elon Home? Talk To Us Before You Accept Any Estimate
The first offer is rarely based on a full structural inspection, and once you cash the check, reopening the claim gets harder. For The Public Adjusters, Inc. is licensed and bonded in North Carolina, and the consultation costs you nothing. Let us look at the damage and both policies before anyone tells you what your home is worth.
Call us: (336) 331-8300
Helpful Resources
- NCDOI Public Adjusters Guide
- National Association of Insurance Commissioners (NAIC)
- North Carolina Department of Insurance consumer resources — State regulator’s guidance for policyholders and adjuster license verification
- Insurance Information Institute on homeowners claims — Nonprofit consumer education on the homeowners claim process
Last updated: September 20, 2026