
If your fire loss has turned into an Arson Homeowners Claim Haw River NC situation — the insurance company suspects the fire was intentionally set — you still have the right to be paid for a covered loss, and you do not have to face that investigation alone. For The Public Adjusters, Inc. represents Haw River homeowners, not the insurance company, throughout the cause-and-origin investigation, documentation, and settlement negotiation. We are licensed and bonded in North Carolina, and we work only for policyholders.
What This Service Is
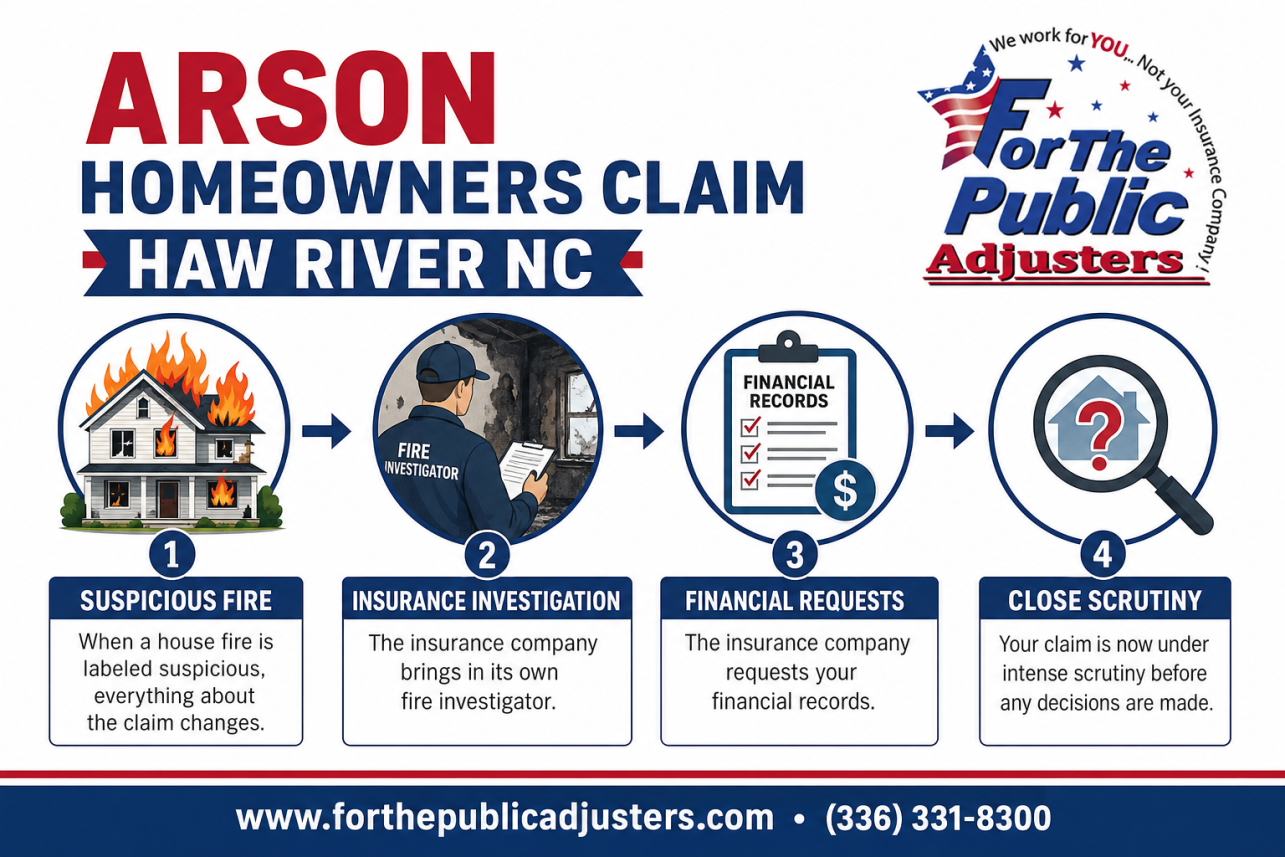
When a house fire is labeled suspicious, everything about the claim changes. The insurance company brings in its own fire investigator, requests your financial records, and may pause payment entirely while it looks for a reason to deny. Many homeowners are shocked to learn they are effectively being treated as suspects in their own loss.
Our job as your public adjuster is to level that playing field. We document the full scope of the fire, smoke, and water damage, prepare your personal property inventory room by room, file the proof of loss correctly and on time, and push back when the carrier’s investigation stalls your payment without cause. If you were the victim of arson — a vacant-home fire, a fire set by a vandal, or a fire tied to a dispute you had nothing to do with — the loss is generally covered, and the burden is on the insurer to prove otherwise, not on you.
We handle these cases across Alamance County and the surrounding Piedmont. A recent Arson Homeowners Claim in Elon followed the same pattern most Haw River families experience: a legitimate loss, a slow investigation, and a settlement offer that only moved once every dollar of damage was properly documented and disputed.
Courts have repeatedly backed policyholders in these fights. In Zoppo v. Homestead Insurance Co., the insurer denied a fire loss by alleging the insured set the blaze; the Ohio Supreme Court upheld a verdict for the policyholder, finding the company lacked a reasonable basis for the arson denial and had acted in bad faith. It is a useful reminder that an accusation is not proof, and an insurer that denies without solid evidence can be held accountable.
Common Problems
Will My Policy Actually Pay If The Fire Was Set On Purpose?
Yes — if you didn’t set it. Standard homeowners policies exclude fires intentionally set by the insured, but arson committed by a stranger, a vandal, or even an estranged party you can prove acted alone is a covered peril, the same as a vandalism claim.
What’s at stake is significant: the structure, your contents, debris removal, and loss of use benefits that pay for temporary housing while you can’t live in the home. If the home is a total loss, the numbers get large fast, and your mortgage lender will be named on the check and involved in how funds are released.
The most common problem we see is not outright denial but quiet underpayment — smoke contamination in rooms the fire never touched, wiring and framing damage behind walls, and contents priced at garage-sale values instead of what replacement actually costs in Alamance County. A careful, independent damage assessment is how you keep those dollars in the claim.
My Arson Homeowners Claim Haw River NC Payment Is Suspended — What Now?
When a fire is flagged as suspicious, carriers routinely suspend the claim pending investigation. You may be asked to sit for an examination under oath, hand over bank statements and tax returns, and answer questions about your finances — because financial motive is exactly what they’re probing.
That process is legal, but it is not unlimited. North Carolina law requires insurers to handle claims promptly and in good faith, and the NCDOI Public Adjusters Guide makes clear that policyholders are entitled to independent representation during the claim. A criminal fire investigation and your civil insurance claim are separate tracks — being questioned by investigators is not a finding of guilt, and it does not erase your coverage.
We keep the pressure on: meeting deadlines for the proof of loss, responding to document requests strategically, and creating a paper trail so that if the delay crosses into bad faith, you’re positioned to act. When a case does need litigation, we work alongside Insurance Dispute Lawyers in Raleigh so nothing falls through the cracks.
Should I Handle This Myself Or Hire Someone — And Who?
A routine kitchen fire claim can sometimes be managed alone. A fire the insurer suspects was arson is different — every statement you make can be used to narrow or deny the claim, and the carrier’s investigator does not work for you.
A good public adjuster does three things a homeowner rarely can: builds a defensible, line-item estimate of the structure and contents loss; manages communication so you don’t accidentally hand the carrier a denial argument; and negotiates from documentation rather than hope. Ask any adjuster you consider whether they are licensed in North Carolina, bonded, and experienced specifically with suspected-arson fires — not just storm claims.
We never guarantee an outcome; no honest adjuster can. What we can promise is that your side of the file will be as thorough as the insurer’s, whether the loss is in Haw River or an Arson Insurance Claim in Durham.
Our Process
Free Claim Review And Policy Analysis
We start by reading your actual policy — coverage limits, exclusions, loss of use provisions, and the deadlines that matter, including the statute of limitations on filing suit. Then we review what the carrier has said and done so far, so you know exactly where the claim stands before anything else is submitted.
Independent Documentation Of The Loss
We inspect and document the fire scene ourselves: structural damage, smoke and soot migration, water damage from firefighting, and a complete personal property inventory with replacement values. Where cause and origin are disputed, we can bring in an independent fire investigator whose findings answer the carrier’s, rather than letting their report stand unchallenged. Our Fire Damage Public Adjuster Burlington caseload right next door means this documentation reflects real Alamance County repair costs.
Negotiation, Proof Of Loss, And Settlement
We prepare and file the sworn proof of loss, present the full documented claim to the carrier, and negotiate each disputed line item. If the insurer delays without justification or denies without evidence, we escalate — including complaints to state regulators and referral to counsel when bad faith is on the table. You stay informed at every step, and you make the final call on any settlement.
| Claim Stage | Policyholder Alone | With For The Public Adjusters, Inc. |
|---|---|---|
| Reservation-of-rights letter | Often ignored or misunderstood until the claim stalls | Responded to in writing with documentation that addresses each cited concern |
| Examination under oath | Answering the carrier’s attorney unprepared, risking harmful statements | Thorough preparation on the facts, timeline, and financial records beforehand |
| Cause-and-origin evidence | Relying solely on the carrier’s hired investigator | Independent certified fire investigator and lab testing of alert samples |
| Burden of proof | Assuming you must prove your innocence | Holding the carrier to its burden under Chavis v. State Farm, 317 N.C. 683 (1986) |
| Scope and estimate | Accepting the carrier’s preliminary figure | Line-item estimate covering smoke, structural charring, code upgrades, contents, and ALE |
| Additional living expenses | Payments frozen during the investigation | Documented, pursued, and pressed for retroactive reinstatement where owed |
Commonly Overlooked In The Public Adjusting Industry
- Requesting the lab confirmation behind a canine accelerant alert — Many policyholders and even some adjusters treat a dog alert as proof of arson, when unconfirmed alerts frequently come back negative in laboratory testing.
- The insurer’s burden of proof on an arson defense — Homeowners assume they must prove innocence, but North Carolina’s Supreme Court held in Chavis v. State Farm (1986) that the carrier must prove its arson defense — and the insured won.
- Char-depth measurement in concealed framing — Carrier estimates often price visible burn damage while structurally compromised rafters and studs behind drywall go unmeasured and unpaid.
- Vacancy and occupancy clause documentation — In third-party arson claims on rentals or homes in transition, utility records and lease dates decide coverage, and few owners think to gather them before the carrier raises the clause.
- Retroactive additional living expenses during an arson investigation — Families rarely realize that ALE frozen during a reservation-of-rights period can be pursued back to day one once the arson theory collapses.
- Ordinance-and-law coverage for code-required upgrades — Alamance County permits often trigger updated wiring and smoke detection in fire rebuilds, costs the carrier quietly leaves out of the first estimate.
- Preserving the scene before debris removal — Once the origin area is hauled away, the chance for an independent investigator to rebut the carrier’s incendiary theory is gone for good.
- Smoke and soot contamination in rooms the fire never touched — Acidic soot migrates through HVAC systems and settles in closets and attics, and untested contents in those areas are routinely excluded from the payout.
Case Studies
Case Study #1
Situation: A family on Roxboro Street in Haw River lost most of their home to a fire that started in a detached-side carport while they were out of town visiting relatives in Burlington. The fire marshal’s initial report noted an accelerant-detection dog alerted near the point of origin.
Problem: Within three weeks the insurance carrier sent a reservation-of-rights letter and demanded examinations under oath from both spouses. The claim was effectively frozen — no additional living expense checks, no contents advance — while the family paid rent on a temporary apartment in Graham out of pocket.
Investigation: Our team retained an independent, certified fire investigator to re-examine the origin area before the debris was hauled away. We pulled the family’s cell records, gas station receipts, and toll data confirming they were 90 minutes away when the fire started, and we documented an aging extension cord feeding a chest freezer in the carport.
Findings: Laboratory testing of the dog-alert samples came back negative for ignitable liquids — a common outcome, since canine alerts alone are not confirmation. The independent investigator identified the failed extension cord and freezer compressor connection as a competent accidental ignition source. The carrier’s file contained no evidence of motive, opportunity, or an incendiary origin.
Solution: We prepared the homeowners for their examinations under oath, submitted the negative lab results and the electrical-failure analysis, and put the carrier on notice of North Carolina law: under Chavis v. State Farm Fire & Casualty Co., 317 N.C. 683 (1986), the insurer — not the policyholder — bears the burden of proving an arson defense, and the insured in that case prevailed at the state’s highest court.
Outcome: The carrier withdrew its reservation of rights, reinstated additional living expenses retroactively, and paid the dwelling, contents, and ALE claim in full based on our detailed estimate rather than its initial preliminary figure.
Lesson: A canine alert or an ‘undetermined’ cause is not proof of arson. Preserving the scene, getting independent lab confirmation, and knowing who carries the burden of proof under North Carolina law can be the difference between a denial and a full recovery.
Case Study #2
Situation: A landlord who owns a 1940s mill-village rental near the Haw River textile district had the vacant unit set on fire by a recently evicted tenant. Local law enforcement charged the former tenant with arson, so the owner assumed the claim would be straightforward.
Problem: The carrier accepted that the fire was intentionally set — by someone else — but then attacked the claim from a different angle. It argued the property was ‘vacant’ beyond the policy’s vacancy clause and lowballed the structure estimate, omitting smoke remediation, code-required electrical upgrades, and structural charring in the roof framing.
Investigation: We documented the owner’s utility records, showing power and water had remained on, and gathered the eviction paperwork proving the unit had been occupied within the policy’s vacancy window. We then brought in a licensed contractor to open ceilings and measure char depth on rafters the carrier’s adjuster never accessed.
Findings: The unit did not meet the policy’s definition of vacant at the time of loss. Char depth measurements showed three rafters and a section of roof decking had lost structural capacity, and Alamance County code required updated wiring and smoke detection as part of any permitted repair — costs the carrier’s estimate had excluded entirely.
Solution: We submitted a line-item rebuttal estimate with photographs, char-depth readings, code citations, and the occupancy documentation, and reminded the carrier that innocent-owner arson by a third party is a covered peril under the policy’s fire coverage.
Outcome: The revised settlement came in at roughly two and a half times the carrier’s original structure figure and included ordinance-and-law coverage for the code upgrades plus lost rental income during repairs.
Lesson: Even when arson by a third party is undisputed, carriers can shift the fight to vacancy clauses and scope of repair. Documenting occupancy and opening up hidden structural damage protects the payout.
| Your Situation | Biggest Risk | Smart Next Step |
|---|---|---|
| Fire report lists cause as ‘undetermined’ | Carrier uses ambiguity to stall or build an arson defense | Preserve the scene, get an independent cause-and-origin review before debris removal |
| You received a reservation-of-rights letter | Signals the carrier is investigating you, not just the fire | Get professional representation before giving any recorded statement |
| Carrier scheduled an examination under oath | Innocent misstatements about finances or timeline can sink the claim | Never attend unprepared; organize records and review the policy first |
| Accelerant-dog alert mentioned in the report | Alerts sound damning but frequently fail lab confirmation | Demand the lab results — a negative test undercuts the arson theory |
| Fire was set by a third party (ex-tenant, vandal, break-in) | Carrier pivots to vacancy clauses or scope cuts | Document occupancy, utilities, and full structural damage including hidden charring |
| ALE payments stopped mid-investigation | Families pay rent out of pocket for months | Submit receipts and press the carrier in writing for reinstatement |
| Financial hardship before the fire | Carrier frames it as motive | Address it head-on with documentation rather than hoping it goes unnoticed |
| Claim already denied for arson | Deadlines to contest keep running | Have the denial reviewed — the insurer must actually prove incendiary origin, motive, and opportunity |

Reviews
After our house fire, the insurance company started treating my wife and me like suspects instead of victims. They demanded sworn statements and stopped paying for our temporary housing. For The Public Adjusters brought in their own fire investigator, prepped us for the examination under oath, and pushed back with actual evidence. The company finally dropped the arson accusation and paid the claim. I honestly don’t know what we would have done alone.
Marcus T., Haw River
My rental near the old mill district was torched by an ex-tenant. The carrier admitted it was arson by someone else but then tried to deny me over a vacancy clause and cut the estimate to the bone. This team proved the unit wasn’t legally vacant and found roof damage the company adjuster never even looked at. The final settlement was far beyond the first offer.
Deborah S., Alamance County
The fire report on our home came back ‘undetermined’ and the insurer used that to stall for months. For The Public Adjusters explained that in North Carolina the burden is on the insurance company to prove arson, not on us to prove innocence. They documented everything, handled every call, and got the dwelling and contents paid. Took a little longer than I hoped, but worth every bit of their fee.
James R., Haw River
Frequently Asked Questions
How Does A Public Adjuster Help With An Arson Homeowners Claim Haw River NC?
When a fire at your Haw River home is investigated as arson, the insurance company treats the claim very differently than an accidental fire. The insurer will typically bring in a Special Investigation Unit (SIU), request an Examination Under Oath, and demand extensive financial and personal records before paying anything.
A public adjuster works only for you, the policyholder, never the insurance company. For an Arson Homeowners Claim Haw River NC, our role is to document every element of your loss: the structure, smoke and heat damage in areas the fire never touched, water damage from suppression efforts, and a complete room-by-room contents inventory.
We also help you understand what the policy actually requires of you and what it does not. Arson investigations often drag on for months, and homeowners who go it alone frequently accept lowball settlements just to end the ordeal. Innocent policyholders have real rights, and North Carolina courts have upheld them. In Lovell v. Rowan Mutual Fire Insurance Co., 302 N.C. 150 (1981), the North Carolina Supreme Court ruled that an innocent spouse could recover under a fire policy even though the other spouse intentionally burned the home.
For The Public Adjusters, Inc. is licensed and bonded, and we prepare, present, and negotiate the claim on your behalf. We cannot promise a specific outcome, but we can make certain your loss is fully documented and your side of the story is professionally presented.
My Homeowners Insurance Company Suspects Arson And Won’t Pay My Fire Claim In Haw River. What Are My Rights?
Suspicion is not proof. In North Carolina, if an insurer wants to deny a fire claim based on arson, it generally must establish that the fire was intentionally set, that the insured had a motive, and that evidence links the insured to the fire. An open investigation by the Alamance County Fire Marshal or the SBI does not, by itself, give the carrier the right to deny your claim.
You also have important protections if someone else set the fire. North Carolina case law strongly favors innocent policyholders. In Lovell v. Rowan Mutual Fire Insurance Co., the state’s highest court held that a wife who had no part in her husband’s intentional burning of their home was still entitled to recover her interest under the fire policy. That principle matters in Haw River, where many homes are jointly owned.
While the investigation continues, keep meeting your policy duties: mitigate further damage, provide reasonable documentation, and comply with legitimate requests. But be careful — statements made during an Examination Under Oath can be used to deny the claim, so preparation matters.
As your public adjuster, we help you organize records, build a defensible contents inventory, and document the full scope of structural, smoke, and water damage. We are licensed and bonded, and while no one can guarantee a particular settlement, a properly presented claim is far harder for a carrier to underpay or delay.
What Kinds Of Damage Should Be Included In An Arson Fire Claim On A Haw River Home?
Far more than the burned rooms. One of the most common mistakes we see on fire claims in Alamance County is homeowners accepting an estimate that covers only the visible burn area.
A complete claim on a Haw River house should account for structural damage to framing, roofing, and load-bearing members; smoke and soot contamination that travels through HVAC ductwork into rooms far from the fire’s origin; heat damage to wiring, plumbing, windows, and vinyl siding; and water damage from fire-department suppression, which often ruins flooring, drywall, and insulation on lower levels.
Contents are frequently the most undervalued portion. Clothing, furniture, electronics, and kitchenware that absorb smoke odor may need professional cleaning or full replacement, and your policy’s personal property coverage exists for exactly that purpose. Additional Living Expenses (ALE) coverage should pay for temporary housing, extra mileage, and increased food costs while your home is uninhabitable — an important protection when suitable rentals near Haw River and Graham are limited.
Many older homes in this area also trigger code-upgrade issues during rebuilding, and ordinance-or-law coverage may apply. Courts have repeatedly required insurers to honor the full scope of fire policies; in Lovell v. Rowan Mutual, the North Carolina Supreme Court refused to let a carrier escape paying an innocent insured’s interest in a burned dwelling.
We inspect, measure, photograph, and inventory everything, then present a documented claim. We never guarantee a dollar figure, but we make sure nothing covered is left off the table.
How Long Does An Arson Homeowners Claim Haw River NC Take, And Can I Speed It Up?
An Arson Homeowners Claim Haw River NC almost always takes longer than an ordinary fire loss. When the cause is listed as incendiary or undetermined, the carrier will usually wait on the fire marshal’s report, retain its own cause-and-origin expert, and may schedule an Examination Under Oath. Realistically, these claims can run several months to a year or more, depending on the investigation.
You can shorten that timeline by being organized. Cooperate promptly with reasonable requests, but keep copies of everything you send. Secure the property to prevent further damage, since failure to mitigate gives the insurer a reason to reduce payment. Start your contents inventory immediately while memories are fresh — photographs, receipts, bank statements, and credit card records all help establish ownership and value.
A public adjuster keeps the claim moving by submitting a complete, well-documented proof of loss rather than letting the carrier control the pace with piecemeal requests. When an insurer stalls or denies without solid evidence, North Carolina policyholders have recourse: in Lovell v. Rowan Mutual Fire Insurance Co., an innocent co-insured took her fire claim all the way to the North Carolina Supreme Court and won her recovery under the policy.
For The Public Adjusters, Inc. handles homeowners fire and arson-related property claims throughout Haw River and the rest of Alamance County. We are licensed and bonded. We cannot promise a specific timeline or amount — no honest adjuster can — but thorough documentation from day one is the single best way to avoid unnecessary delays.
What Evidence Should I Gather For An Arson Homeowners Claim Haw River NC?
Start with documentation you can secure quickly, because fire scenes degrade fast in Alamance County humidity. Photograph every room, the exterior, and the roofline before anything is moved. Save the fire marshal’s incident number from the Haw River Fire Department, and request a copy of the official cause-and-origin report as soon as it’s released.
Next, pull together your policy declarations page, any endorsements, and proof of ownership for damaged contents. Receipts, credit card statements, photos from holidays or family gatherings, and even smartphone videos taken inside the home over the years all help establish what you owned and its condition.
Keep a written log of every conversation with the insurance company, including dates, names, and what was said. If the insurer sends its own cause-and-origin investigator, note who they are and what they examined. You have the right to have your own representative present.
Finally, do not throw anything away. Burned contents are evidence, and discarding them can hurt your claim. Courts have held insurers accountable when they mishandle property claims — in DENC, LLC v. Philadelphia Indemnity Insurance Co. (4th Cir. 2020), a North Carolina property owner won against its insurer over a denied building-damage claim, and the court upheld a bad-faith finding. Strong documentation is what makes outcomes like that possible. As licensed and bonded public adjusters, we help homeowners assemble this evidence properly from day one, though no one can promise a specific dollar result.
Will The Insurance Company Deny My Fire Claim If Someone Else Set The Fire At My Haw River Home?
Not if the claim is handled correctly. Third-party arson — a fire set by a vandal, an angry ex, a burglar, or an unknown person — is a covered peril under virtually every North Carolina homeowners policy. The arson exclusion insurers rely on applies to intentional acts by the insured, not crimes committed against you.
The practical problem is that once a fire is ruled incendiary, some carriers treat every policyholder as a suspect. They may demand an examination under oath, extensive financial records, and long delays while a special investigations unit reviews the file. That scrutiny is legal, but it does not erase your right to payment when you did nothing wrong.
Under North Carolina law, the burden sits on the insurer. To deny based on arson, the company generally must show the fire was intentionally set, that you had the opportunity to set it, and that you had a motive. If they cannot prove your involvement, a fire set by someone else is simply a fire loss that must be paid.
Our team represents Haw River and Alamance County homeowners through that process — attending inspections, responding to document demands, and preparing the full estimate of structure, smoke, and contents damage while the investigation runs its course. Cooperate fully, document everything, and don’t give recorded statements alone. We’re licensed and bonded, and while we can’t guarantee any particular outcome, we can make sure the insurer evaluates your loss on the evidence rather than on suspicion.
How Much Does It Cost To Hire A Public Adjuster For An Arson-Related Fire Claim In Alamance County?
Public adjusters in North Carolina work on a contingency fee — a percentage of what the insurance company actually pays on your claim. There is no upfront cost and no hourly billing. If the insurer pays nothing, you owe nothing for the adjusting work, which matters when your family is already covering hotel bills and replacement clothing after a fire.
The percentage is spelled out in a written contract before any work begins, and North Carolina regulates public adjuster contracts to protect policyholders. For The Public Adjusters, Inc. is licensed and bonded, which the state requires and which you should verify with any adjuster you consider hiring.
For an arson-suspected fire loss in Haw River, the fee typically covers a lot of labor: a room-by-room structural estimate, a complete contents inventory with pricing, smoke and soot testing where warranted, coordination of additional living expense reimbursement, preparation for any examination under oath, and negotiation with the carrier’s adjusters and investigators.
Homeowners often ask whether the fee is worth it. Every claim is different and no result can be promised, but a professionally documented claim is much harder for a carrier to underpay or stall. Courts have repeatedly sided with policyholders who pushed back with solid documentation — the property owner in DENC, LLC v. Philadelphia Indemnity Insurance Co. prevailed against its insurer over denied building damage precisely because the record was strong. Before you sign anything, we’ll walk you through the contract, the fee, and exactly what we’ll do on your file.

Can My Claim Be Denied Just Because The Fire Marshal Ruled The Fire At My House Incendiary?
No. An incendiary ruling means investigators believe the fire was intentionally set — it does not mean you set it, and it is not by itself a legal basis to deny an Arson Homeowners Claim Haw River NC. The insurance company must connect you personally to the fire before an arson defense can stand up.
In North Carolina, an insurer raising arson generally has to prove three things: the fire was incendiary in origin, you had the opportunity to set it, and you had a motive, such as financial distress. Missing any leg of that test, the defense collapses. Many denials are issued on suspicion and pressure, not proof, and policyholders who challenge them with organized evidence often see very different results.
The insurer’s investigation also cuts both ways. If the carrier delays unreasonably, refuses to explain its position, or denies without adequate grounds, North Carolina law allows claims for bad faith and unfair claim practices. In DENC, LLC v. Philadelphia Indemnity Insurance Co. (4th Cir. 2020), the insured building owner won its case after the insurer wrongly denied structural damage coverage, and the appellate court upheld the judgment against the carrier.
If your Haw River claim has been flagged, denied, or stuck in a special investigation, get representation before your examination under oath, not after. We prepare the damage documentation, alibi timeline, and financial records that answer the insurer’s three-part test head-on. We can’t guarantee any specific payment, but we can make sure a suspicion never gets treated as proof.
Should I Give A Recorded Statement Before Getting Help With An Arson Homeowners Claim Haw River NC?
You should be very careful. While your policy requires cooperation with the insurance company, you are not obligated to give a recorded statement on the spot, and rushing into one is a common mistake after a suspicious fire in Haw River.
When arson is on the table, the adjuster’s questions are rarely casual. They often probe your finances, your whereabouts the night of the fire, recent listing history on the home, and past claims. Innocent inconsistencies — misremembering a time, guessing at a mortgage balance — can later be framed as material misrepresentations and used to deny the claim.
A better approach is to schedule the statement after you have reviewed your policy, gathered documents, and understand what the insurer already knows about the fire investigation. As licensed and bonded public adjusters, For The Public Adjusters, Inc. helps Haw River homeowners prepare before they speak, so the record reflects accurate facts rather than nervous guesses.
Courts have repeatedly held that insurers, not homeowners, carry the burden of proving an arson defense. In McGory v. Allstate Insurance Co., 527 So. 2d 632 (1988), the court ruled in favor of the insured on a denied house-fire claim, holding that the insurer must prove an incendiary fire, motive, and opportunity with clear evidence — suspicion alone is not enough. Preparing carefully for your statement helps keep the burden where the law places it: on the insurance company.
What Is An Examination Under Oath, And Will I Face One After A Suspicious House Fire In Haw River?
An Examination Under Oath, or EUO, is a formal, transcribed interview conducted by the insurance company’s attorney, and it is very common when a fire at an Alamance County home has been labeled incendiary. Unlike a recorded statement, an EUO is a contractual duty under most homeowners policies — refusing to appear can void your coverage entirely.
Expect detailed questions about your income, debts, bank records, the home’s condition before the fire, and a room-by-room accounting of your contents. The insurer’s attorney is looking for contradictions between your EUO testimony, your proof of loss, and the fire marshal’s file.
The good news: you are allowed to prepare, to have representation involved in the claim, and to review documents beforehand. A well-prepared Haw River policyholder who answers truthfully and consistently often strengthens the claim, because the transcript becomes evidence that supports payment rather than denial.
Homeowners who stand firm through this process have prevailed in court. In McGory v. Allstate Insurance Co., the insured’s fire claim was denied on arson allegations, yet the court found the insurer failed to carry its burden of proof and the homeowner recovered. Our team helps clients organize financial records, contents inventories, and timelines before the EUO, so the testimony is accurate, complete, and consistent with every other document in the file. We never guarantee an outcome, but thorough preparation consistently puts policyholders in a far stronger position.
Have Homeowners Actually Won In Court After Being Accused Of Setting Fire To Their Own House?
Yes, and it happens more often than insurers would like homeowners to believe. To win an arson defense, an insurance company generally must prove three things: that the fire was intentionally set, that the insured had a motive, and that the insured had the opportunity to set it or arrange it. If any leg of that stool fails, the defense fails.
In McGory v. Allstate Insurance Co., 527 So. 2d 632 (1988), Allstate denied a homeowner’s fire claim alleging arson. The court sided with the insured, holding that the insurer’s circumstantial evidence was not strong enough to establish the arson defense, and the policyholder recovered for the destroyed home. That decision is still cited for the principle that suspicion, financial stress, or an unexplained fire cause is not proof that the homeowner did it.
For anyone pursuing an Arson Homeowners Claim Haw River NC, that case matters because it defines the fight. The homeowner does not have to prove innocence; the insurer has to prove guilt by the applicable evidentiary standard, in civil court, with real evidence.
Our role at For The Public Adjusters, Inc. is on the claim side rather than the courtroom: documenting the structure and contents loss, meeting policy deadlines, and building a file so complete that the carrier’s leverage shrinks. When a claim is properly documented and the insurer still refuses to pay, that same file becomes powerful material if the dispute ever moves to litigation with an attorney.
Am I Still Owed Temporary Housing Money While The Arson Investigation Drags On In Haw River?
In most cases, yes. Standard homeowners policies include Additional Living Expense coverage, often called ALE or Coverage D, which pays the reasonable increase in living costs while your home is uninhabitable. A pending fire-cause investigation does not automatically suspend that duty, and many Alamance County families are wrongly told to wait with nothing.
ALE typically covers rent for comparable housing, hotel stays, the added cost of meals over your normal grocery bill, pet boarding, extra mileage if your temporary home lengthens the drive to work or Haw River schools, and even laundry costs if you lose access to your machines. Keep every receipt from day one, because insurers pay documented expenses, not estimates.
Some carriers will advance ALE under a reservation of rights while they investigate, which lets them pay now and preserve their defenses. If your adjuster refuses to discuss ALE at all, ask for that refusal in writing, along with the specific policy language they rely on. Unreasonable delay on undisputed living expenses can expose an insurer to bad-faith arguments later.
As part of handling an Arson Homeowners Claim Haw River NC, we track ALE as its own ledger — separate from the structure and contents claims — so nothing gets absorbed or forgotten in the larger negotiation. Rental comparables around Haw River, Graham, and Burlington help establish what a fair monthly housing figure looks like, and monthly ALE submissions keep money flowing to your family while the cause-and-origin fight plays out.
Can I Still File An Arson Homeowners Claim Haw River NC If The Fire Happened While My House Was Vacant Or Listed For Sale?
Yes, you can still file, but expect the insurer to look at the loss closely. Vacant homes and homes on the market are two situations where carriers frequently raise questions about motive, so how the claim is documented from day one matters a great deal.
Most homeowners policies contain a vacancy provision, and some restrict coverage if the property sat empty for 30 or 60 consecutive days before the fire. Whether your Haw River house was truly “vacant” under the policy language is often arguable — a home with furniture, utilities on, or regular visits may be considered unoccupied rather than vacant, and that distinction can decide the claim.
A listing on the market is not evidence of wrongdoing. Plenty of Alamance County homeowners sell because of job changes, family needs, or downsizing. The insurer still bears the burden of proving an intentional act by the insured if it wants to deny on arson grounds; suspicion about your circumstances is not proof.
Our licensed and bonded team reviews the vacancy clause in your specific policy, gathers records showing the home’s actual condition and use, and presents the loss so the facts — not assumptions — drive the outcome. We cannot promise a particular result, but we can make sure the carrier evaluates the claim on complete, accurate information rather than a hurried file review.
The Adjuster Says I Had A Financial Motive. Can The Insurer Deny My Fire Claim Over Money Problems Alone?
No. Financial pressure by itself is not proof of arson, and North Carolina law places the burden squarely on the insurance company. To deny a fire loss as intentional, the carrier generally must show the fire was incendiary, that you had motive, and that evidence connects you to setting it. A tight budget or a past-due bill checks only one of those boxes.
Haw River homeowners should also know that carriers who mishandle these accusations can face real consequences. In Bryant v. Nationwide Mutual Fire Insurance Co., 313 N.C. 362 (1985), Nationwide refused to pay after a home fire and pointed to suspected arson. The homeowners fought back, and the North Carolina Supreme Court sided with the policyholders, holding that unfair claim-handling conduct could support claims under the state’s unfair and deceptive trade practices law — exposure that can multiply an insurer’s liability. That decision still shapes how fire claims are litigated in this state today.
In practice, we push back on motive theories with documentation: bank records showing you were current or managing debt, evidence of equity in the home, and proof of where you were when the fire started. We also make sure your losses are fully measured while the coverage fight plays out.
If a carrier is leaning on your finances instead of fire science, get experienced help before you answer more questions. We are licensed and bonded, and while no one can guarantee an outcome, the Bryant case shows homeowners are not powerless.
Who Gets The Insurance Money After An Arson Fire When There’s A Mortgage On My Haw River Home?
If you have a mortgage, your lender is almost certainly listed on the policy under a mortgagee clause, and checks for structural damage will typically be made out to both you and the lender. The lender then either releases funds in stages as repairs progress or applies money toward the loan balance, depending on your mortgage terms and the size of the loss.
Here is a detail that matters in arson disputes: the standard mortgagee clause gives the lender rights independent of yours. Even if the insurer accuses the named insured of setting the fire, the carrier may still owe the lender its interest. That does not pay you directly, but it affects negotiations and how the file gets resolved.
Contents coverage works differently. Payments for your furniture, clothing, and personal belongings usually go to you alone, without the lender’s name on the check. The same is generally true of additional living expense payments that cover temporary housing in the Haw River or Burlington area while your home is unlivable.
We help homeowners coordinate all three of these payment streams so repairs are not stalled by a lender sitting on funds. That means submitting contractor estimates and repair timelines the mortgage servicer will accept, and keeping the dwelling, contents, and living-expense portions of the claim moving on their own tracks. Note that we handle property claims only — homes, buildings, and contents — not vehicle, health, or life insurance matters.

What Is A Sworn Proof Of Loss, And How Does It Affect An Arson Homeowners Claim Haw River NC?
A sworn proof of loss is a formal, notarized document in which you state the amount of your damages, how the fire occurred to your knowledge, your interest in the property, and other facts about the loss. In an Arson Homeowners Claim Haw River NC, this document carries extra weight because the insurer will scrutinize every line of it — and errors can be twisted into accusations of misrepresentation.
North Carolina’s standard fire policy language typically requires the proof of loss within 60 days after the insurer demands it, though deadlines can vary and carriers sometimes extend them in writing. Missing the deadline, or submitting figures you cannot support, gives the company an opening to delay or deny. That is why guessing at values is dangerous.
Before the form is signed, the numbers behind it should be built properly: a room-by-room contents inventory with replacement costs, a detailed structural repair estimate reflecting Alamance County labor and material pricing, smoke and soot remediation, and additional living expenses. Every figure should trace back to documentation.
As public adjusters, preparing accurate proofs of loss is central to what we do. We assemble the supporting estimates, reconcile them against your policy limits and coverages, and make sure what you swear to is defensible if the carrier later takes an Examination Under Oath or the matter ends up in litigation. In a suspected-arson file, a clean, well-supported proof of loss is one of the strongest tools a homeowner has.
Local Relevance
Haw River is a small, historic mill town, and much of its housing stock reflects that heritage — older frame homes with original wiring, balloon framing, and dense wood construction that burns fast and hides smoke damage deep in wall cavities. When a fire here is labeled suspicious, insurers often lean on the age and condition of the home to shrink the payout, arguing depreciation on materials that can’t actually be matched or repaired cheaply anymore.
Vacant and rental properties in and around town face particular scrutiny, because vacancy is one of the first things a carrier’s investigator flags in a suspected arson file. If you inherited a family home, were between tenants, or had the house listed for sale when the fire happened, expect hard questions — and know that none of those facts void your coverage by themselves.
The National Fire Protection Association has long noted that intentionally set fires tend to cause disproportionately severe damage, in part because they often start in vacant or unoccupied structures and burn longer before discovery. That reality cuts in your favor as a policyholder: a severe, fast-moving fire is consistent with victimhood, not guilt, and the claim should be built accordingly.
Many Haw River homes date to the town’s textile-mill era, and in older frame construction smoke and heat travel through open wall and floor cavities far beyond the visible burn area — so a fire claim scoped only from what’s charred often misses a large share of the true damage. Insisting on cavity-level inspection before accepting any estimate tends to change the numbers considerably.
Under Investigation For A Fire You Didn’t Set? Talk To Us First.
For The Public Adjusters, Inc. represents Haw River and Alamance County homeowners through suspicious-fire investigations, suspended payments, and lowball settlements. We’re licensed and bonded in North Carolina, we work only for policyholders, and the initial claim review is free. The sooner we’re involved, the more of the record we can shape.
Call us: (336) 331-8300
Helpful Resources
- NCDOI Public Adjusters Guide
- National Fire Protection Association (NFPA)
- U.S. Fire Administration — Federal fire data, safety, and post-fire recovery resources
- North Carolina Department of Insurance — State regulator overseeing insurers and public adjuster licensing
Last updated: September 26, 2026