
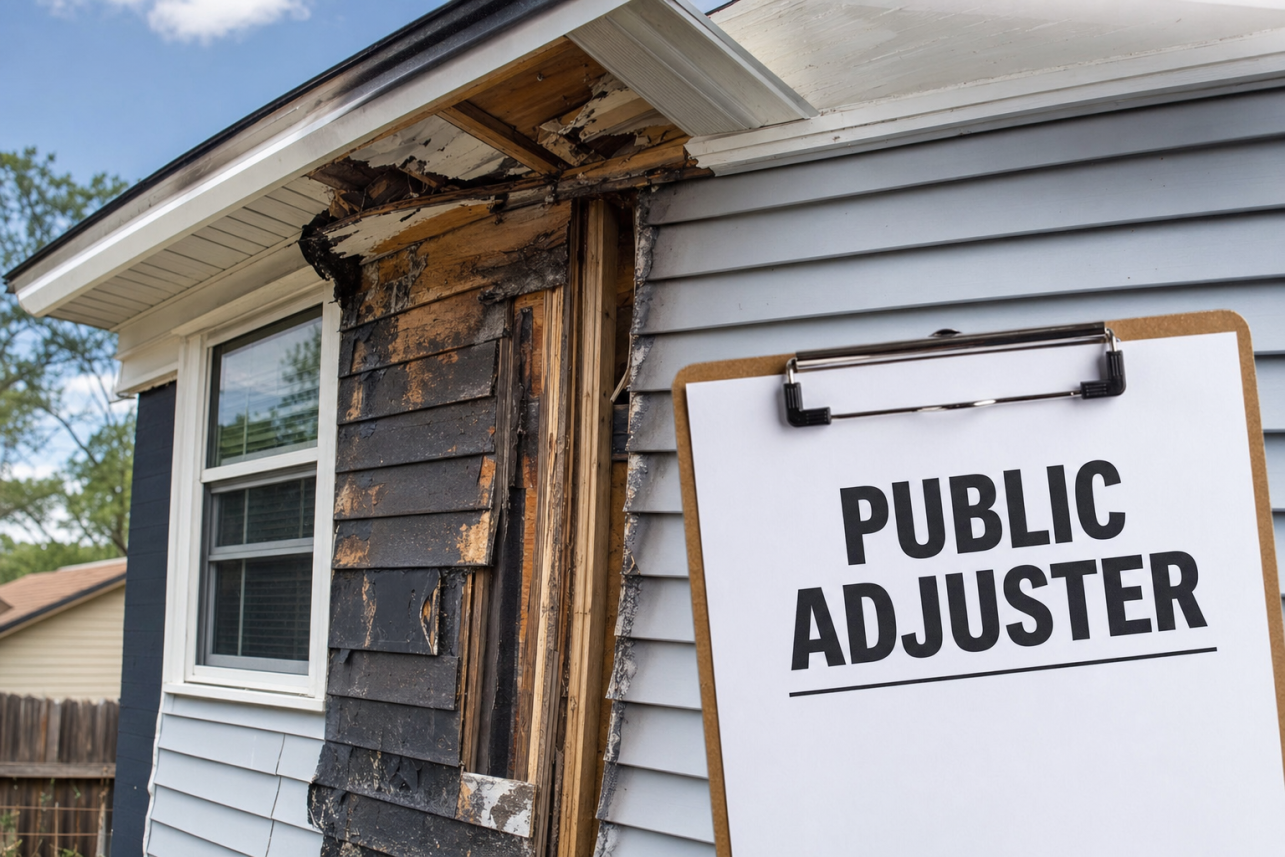
A public adjuster Clayton NC policyholders hire works exclusively for you — not the insurance company — to document, value, and negotiate your property damage claim. For The Public Adjusters, Inc. is licensed and bonded, handling residential and commercial losses across Clayton and Johnston County, from fire and smoke to water, tree damage, and NFIP flood claims. Instead of accepting the carrier's first number, you get an independent professional building the claim from your side of the table.
What This Service Is
When your home or business suffers a covered loss, the insurance company sends its own adjuster to assess the damage. That adjuster is paid by the carrier. A public adjuster is the licensed professional who represents the policyholder instead — reading the policy line by line, inventorying damaged structures and contents, preparing detailed estimates, and negotiating the settlement directly with the insurer.
In North Carolina, public adjusters must be licensed, and the NCDOI Public Adjusters Guide explains exactly what we can and cannot do on your behalf — including caps on fees and the requirement of a written contract before work begins. That regulatory framework exists to protect you, and we operate squarely within it.
For The Public Adjusters, Inc. handles fire, smoke, and arson claims, water and flood damage, tree and hurricane-related wind losses, vandalism, car-hits-home incidents, and commercial business claims. We do not handle auto, health, life, or cell phone claims — property losses to homes, buildings, and their contents are our entire practice.
Common Problems
What Does A Public Adjuster Clayton NC Homeowner Hires Actually Cost — And Is It Worth It?
Public adjusters in North Carolina work on a contingency fee, a percentage of the settlement that state regulators cap and require in writing before any work starts. There is no hourly bill and no upfront retainer.
The real question is what the claim is worth without one. Carrier estimates frequently miss code-upgrade costs, hidden moisture behind walls, smoke residue in HVAC systems, and full contents inventories. We cannot guarantee any specific outcome — no honest adjuster can — but a properly documented claim is negotiated from a far stronger position than a homeowner's phone-photo estimate.
My Claim Was Underpaid, Delayed, Or Denied. What Now?
A denial or lowball offer is rarely the end of the road. Courts have repeatedly sided with policyholders whose losses were wrongly minimized. In Corban v. United Services Automobile Association, the Mississippi Supreme Court ruled for homeowners after Hurricane Katrina, holding that the insurer could not use its anti-concurrent-cause language to escape paying for wind damage that occurred before floodwater arrived — a decision that reshaped how mixed wind-and-flood losses are evaluated.
You don't need a lawsuit to benefit from that principle. Most disputes resolve when the loss is re-documented professionally: causation established, damage scoped room by room, and the policy's own language put back on the table. That is the core of what we do.
How Do I Know I'm Hiring The Right Claim Representative?
Start with the basics: verify the license, confirm bonding, and insist on a written contract that spells out the fee. Anyone who pressures you to sign on the spot, promises a specific dollar figure, or shows up uninvited right after a fire deserves skepticism.
Then ask about the loss type. A flood claim under the National Flood Insurance Program follows different rules and deadlines than a homeowners fire claim, and an adjuster who has worked NFIP files knows the proof-of-loss requirements cold. For The Public Adjusters, Inc. is licensed and bonded, and we will walk you through our contract before you commit to anything.

Our Process
Free Policy And Damage Review
We start by reading your actual policy — declarations, endorsements, exclusions — and walking the loss. Many Clayton homeowners are surprised by what their coverage actually includes, from debris removal to additional living expenses while repairs are underway. You get a straight answer about whether professional representation makes sense before you sign anything.
Documentation And Valuation
We photograph and scope every affected area, test for hidden moisture or smoke migration, and build a room-by-room contents inventory with replacement values. For structural damage, we prepare line-item repair estimates using the same estimating standards carriers use. This file becomes the foundation of the entire negotiation.
Negotiation And Settlement
We present the claim to your insurer, attend inspections alongside the company adjuster, respond to every request for information, and negotiate each disputed line item. You are kept informed at every stage, and nothing settles without your approval. Our fee comes from the recovery, so our interests stay aligned with yours from the first meeting to the final check.
| What Happens | Filing the Claim Yourself | With For The Public Adjusters, Inc. |
|---|---|---|
| Who documents the damage | The carrier's adjuster, who works for the insurance company | An independent licensed adjuster working only for you |
| Hidden damage (moisture, mat fractures, smoke residue) | Rarely investigated beyond what's visible | Moisture mapping, test squares, and full-scope inspections |
| Estimate detail | Carrier's scope, often missing code upgrades and matching costs | Line-item estimate built in the same software carriers use |
| Negotiation | You argue your own claim with no leverage | Documented supplements and direct negotiation with the carrier |
| Typical result | First offer often accepted, underpayment absorbed by you | Settlements frequently multiples of the initial offer |
| Cost to you | Free, but you keep any shortfall | A percentage of the recovery — no recovery, no fee |
Commonly Overlooked In The Public Adjusting Industry
- Matching coverage for discontinued shingles and flooring — Carrier adjusters scope a patch repair without checking whether the material is still manufactured, leaving homeowners with a mismatched roof or floor.
- Hidden moisture inside wall cavities and under continuous flooring — Initial inspections rely on what's visible, and water that has wicked into framing or under hardwood shows up as mold and rot months later.
- Ordinance and law (code upgrade) coverage — Older Clayton homes often need updated wiring, venting, or fasteners during repairs, and that coverage sits unused because nobody itemizes it.
- Additional living expenses beyond the first hotel stay — Policyholders don't realize ALE can cover months of comparable housing, mileage, and meal differentials while their home is unlivable.
- Recoverable depreciation left unclaimed — Carriers hold back depreciation until repairs are complete, and homeowners who don't submit final invoices simply forfeit that money.
- Contractor overhead and profit on multi-trade losses — When a loss involves three or more trades, general contractor O&P belongs in the estimate, but carriers routinely leave it out unless someone demands it.
- Smoke and soot migration into rooms far from a fire — Residue travels through HVAC ducts and settles in closets and attics that look clean, so contents and cleaning costs get dramatically undercounted.
- Functional versus cosmetic hail damage on metal and vinyl — Cracked locking legs and fractured shingle mats compromise weather resistance, but they're written off as dents unless documented up close.
Case Studies
Case Study #1
Situation: A family in the Flowers Plantation area of Clayton came home from a weekend at the coast to find their upstairs bathroom supply line had failed, sending water through the ceiling into the kitchen and living room below.
Problem: Their carrier's initial estimate came in at $11,400 and treated the loss as surface-level: dry the structure, replace some drywall, paint. It ignored hardwood flooring that had cupped throughout the first floor and cabinets that had wicked water up their bases.
Investigation: We brought in moisture mapping equipment and documented elevated readings inside wall cavities the carrier's adjuster never opened. We also pulled the kitchen toe-kicks and photographed swollen particleboard cabinet boxes, then obtained a flooring vendor letter confirming the discontinued hardwood could not be patched to match.
Findings: The loss involved hidden moisture in three wall assemblies, unsalvageable cabinetry along two runs, and continuous hardwood that under NC matching considerations required replacement through connected rooms — none of which appeared in the original scope.
Solution: We prepared a line-item estimate using the same pricing software the carrier used, submitted the moisture logs and vendor documentation, and walked the property with the carrier's field adjuster to justify every added line.
Outcome: The claim settled at $58,700 — more than five times the original offer — covering full flooring replacement, cabinet runs, wall cavity remediation, and additional living expenses while the family stayed elsewhere during the work.
Lesson: The first estimate after a water loss almost always reflects what's visible on day one, not what a proper moisture investigation reveals. Homeowners in Johnston County who accept that first number often pay the difference out of pocket.
Case Study #2
Situation: A retired couple off Amelia Church Road in Clayton had their roof and siding hammered in a spring hailstorm that also produced straight-line winds across Johnston County.
Problem: The insurance company's adjuster approved slope-by-slope repairs — a handful of shingles on two elevations — and denied the siding entirely, calling the dents 'cosmetic.' The couple was left with a checkerboard roof repair on a discontinued shingle and no siding payment.
Investigation: We conducted a full roof inspection with chalk-marked test squares on all slopes, photographed fractured shingle mats consistent with hail impact, and documented that the shingle line had been discontinued by the manufacturer. On the siding, we showed cracked panels and broken locking legs, not just cosmetic denting.
Findings: Hail strikes exceeded the functional damage threshold on every slope, replacement shingles could not be reasonably matched, and the vinyl siding damage was structural to the panels themselves — compromising their weather resistance, not just their appearance.
Solution: We filed a supplemental claim with the photo documentation, manufacturer discontinuation notice, and a revised estimate for full roof replacement plus siding on the two affected elevations, then negotiated directly with the carrier's desk adjuster.
Outcome: The carrier reversed its position and paid for a complete roof replacement and both damaged siding elevations — a final settlement of $41,200 versus the original $6,800 repair approval.
Lesson: 'Cosmetic damage' denials and slope-by-slope repairs are two of the most common ways hail claims get underpaid around Clayton. Discontinued materials and functional damage arguments change the outcome, but only if someone documents them properly.
| Your Situation | Handle It Yourself? | What It Depends On |
|---|---|---|
| Small, visible loss under your deductible or barely above it | Usually yes | Whether a professional inspection would reveal hidden damage that changes the math |
| Water loss with any ceiling, flooring, or cabinet involvement | Rarely | Hidden moisture in wall cavities and continuous flooring almost always expand the true scope |
| Hail or wind claim denied as 'cosmetic' or approved for spot repairs | No | Functional damage documentation and matching rules for discontinued materials |
| Fire or smoke loss with contents damage | No | Room-by-room inventory, smoke residue testing, and depreciation pushback require expertise |
| Carrier's offer feels low but you can't say why | Get a free claim review first | A line-item comparison usually reveals missing trades, code items, or overhead and profit |
| Claim already denied in writing | No | NC allows supplemental and re-opened claims when new documentation supports them |
| Loss happened more than two years ago | Ask before assuming it's too late | Policy conditions and NC's limitations period — some older claims can still be reopened |


Reviews
After the pipe burst in our laundry room, State's estimate barely covered drying out the walls. For The Public Adjusters found moisture in places their guy never even looked and got our whole floor replaced instead of patched. The final settlement was almost four times the first offer. Worth every penny of their fee.
Melissa T., Clayton
Our hail claim got denied as 'cosmetic' twice before I called them. They did test squares on every slope of the roof, documented cracked shingle mats, and proved the shingles were discontinued. Carrier ended up paying for a full replacement. I wish I'd hired a public adjuster in Clayton the day the storm hit instead of fighting it alone for three months.
Darnell W., Flowers Plantation
We had a kitchen fire and honestly had no idea contents and smoke damage were even claimable the way they handled it. They inventoried everything room by room, pushed back on the depreciation the carrier took, and kept us updated the entire time. Only reason for four stars is the process still took a couple months — but that was the insurance company, not them.
Renee C., Johnston County
Frequently Asked Questions
What Does A Public Adjuster Clayton NC Homeowners Hire Actually Do For My Insurance Claim?
A public adjuster works exclusively for you, the policyholder, never the insurance company. When you hire For The Public Adjusters, Inc., we review your policy in detail, document every bit of damage to your Clayton home or business, prepare a complete and itemized estimate, and negotiate directly with your insurer's adjuster until the claim is settled fairly.
That matters because the adjuster your insurance company sends is paid by the carrier. Their estimate often misses hidden damage, such as moisture trapped behind drywall after a burst pipe, wind-lifted shingles that are not visible from the ground, or smoke residue in HVAC ductwork after a kitchen fire.
We handle the entire process: photographing and measuring damage, pulling comparable local repair pricing for Johnston County contractors, filing supplemental claims when new damage is discovered during repairs, and pushing back on lowball offers with documented evidence.
In practical terms, hiring a Clayton public adjuster means you are not left interpreting policy language like 'matching,' 'ordinance and law coverage,' or 'actual cash value versus replacement cost' on your own. We are licensed by the North Carolina Department of Insurance and know how carriers operating in Wake and Johnston counties evaluate claims.
Most of our local clients come to us after a storm, fire, or water loss when the first settlement offer feels too low. Others call us the day the damage happens so the claim is built correctly from the start, which is usually the better approach.
How Much Does It Cost To Hire A Public Adjuster In Clayton, And How Are Fees Structured?
For The Public Adjusters, Inc. works on a contingency fee, which means you pay nothing upfront and nothing out of pocket. Our fee is a percentage of the settlement we recover for you, and North Carolina law caps and regulates those percentages, so the structure is transparent before you sign anything.
If we do not recover money for you, you do not owe us a fee. That aligns our interests with yours: we only do well when your settlement does well.
Homeowners in Clayton often ask whether the fee eats up the extra money we recover. In our experience, it rarely does. Independent industry studies and our own local case files consistently show that professionally adjusted claims settle for significantly more than claims policyholders handle alone, often several times more on large losses like fire or major water damage.
Here is a realistic local example. A hail-damaged roof in the Flowers Plantation area might get an initial carrier estimate that covers a partial repair. A properly documented claim that accounts for full slope replacement, code-required upgrades under Johnston County building requirements, and interior water staining can change that number substantially.
Before you commit, we offer a free claim review. We will look at your policy, your damage, and any offer you have already received, then tell you honestly whether hiring us makes financial sense. If the claim is small or the carrier's offer is already fair, we will say so.
When Should I Call A Claims Adjuster Who Works For Me Instead Of Handling The Insurance Company Myself?
The best time to call is before you file, or as soon as possible after the loss. When For The Public Adjusters, Inc. is involved from day one, we control how the damage is documented, which prevents the most common problem we see in Clayton: a rushed carrier inspection that misses damage and locks in a low estimate.
That said, it is never too late until the claim is closed and the time limits in your policy have run out. Many of our Johnston County clients call us after receiving a settlement offer that will not come close to covering actual repair costs. We can reopen negotiations, file supplements, and dispute denials.
Situations where professional representation makes the biggest difference include: fire and smoke losses, where contents inventories and smoke remediation are routinely undervalued; water and pipe-burst claims, where carriers dispute whether damage was sudden or long-term; hurricane and wind damage, common here given how storms track up from the coast through the Triangle; and any claim over roughly ten thousand dollars.
You should also call if your claim has been denied, delayed for weeks without explanation, or if the carrier is asking for a recorded statement or an examination under oath. Those are signals the insurer is building a case to minimize or deny payment.
For straightforward small claims, say a few hundred dollars of fence damage, you may not need us. A quick free consultation will tell you which situation you are in.
Is A Public Adjuster Clayton NC Residents Use Licensed, And What Should I Look For Before Hiring One?
Yes. Anyone working as a public adjuster in North Carolina must be licensed by the North Carolina Department of Insurance, pass a state examination, carry a surety bond, and complete continuing education. Before hiring any public adjuster Clayton NC property owners should verify the license number directly on the Department of Insurance website, which takes about two minutes.
For The Public Adjusters, Inc. is fully licensed and bonded in North Carolina, and we are happy to provide our license information before you sign anything. Be cautious of anyone who avoids that question or pressures you to sign a contract on the spot, especially door-knockers who show up after a storm rolls through Johnston County.
Beyond the license, ask a few practical questions. How many claims like yours have they handled locally? A firm familiar with Clayton construction, from older homes near downtown to newer builds in Riverwood and Glen Laurel, will produce more accurate repair estimates. Ask who will actually work your claim, since some firms hand files to out-of-state processors. Ask for references from recent North Carolina clients with a similar type of loss.
Finally, read the contract. Under state rules you should see the fee percentage clearly stated, and you have the right to cancel within a set window after signing. A legitimate firm will walk you through every line.
If you would like, we will review your situation at no cost and explain exactly what representation would look like for your specific claim, with no obligation to move forward.
What Types Of Property Damage Claims Does A Public Adjuster Clayton NC Property Owners Rely On Typically Handle?
For The Public Adjusters, Inc. handles the full range of property claims that hit Johnston County homes and businesses. Wind and hail damage top the list — Clayton sits right in the path of the severe thunderstorm corridor that rolls through the Triangle every spring and summer, and hail-bruised shingles or wind-lifted flashing often cause damage insurers undervalue or miss entirely.
We also work water damage claims from burst pipes, water heater failures, and roof leaks, along with fire and smoke losses, lightning strikes, tree impacts, and hurricane damage when tropical systems push inland from the coast. Remnants of storms like Fred and Matthew reached well into this part of NC, and many homeowners were surprised how far inland the damage extended.
Commercial losses are part of our practice too. If you own a shop off Highway 42 or a restaurant near downtown Clayton, we can document business interruption alongside the physical damage — a piece of the claim owners frequently leave on the table.
One thing worth knowing: a claim doesn't have to be catastrophic to justify professional help. A moderate water loss with hidden moisture in wall cavities or a roof claim the carrier wants to settle as a 'repair' rather than replacement can involve tens of thousands of dollars in dispute. If your damage is real and your carrier's number feels low, it's worth having us review the file — the initial consultation costs you nothing.
How Long Does The Insurance Claim Process Take With A Clayton Public Adjuster Involved?
Most residential claims we handle in the Clayton area resolve within 30 to 90 days from the date we take over, though the timeline depends on the size of the loss, how far apart the numbers are, and how responsive your carrier is.
Here's the typical rhythm. In the first week, we inspect the property, photograph and document everything, and pull your policy apart to identify every coverage that applies — dwelling, other structures, contents, additional living expenses, and code-upgrade coverage that Johnston County's permitting requirements can trigger. We then build a line-item estimate using the same software carriers use, so there's no arguing over format.
Once our estimate is submitted, North Carolina's claims-handling rules require insurers to respond within set timeframes, and we hold them to those deadlines. Straightforward wind or water claims often settle within a month or two. Large fire losses, disputed roof replacements, or claims where the carrier initially lowballed can run longer, especially if we invoke the appraisal clause in your policy to break a deadlock.
One important reality: handling a contested claim yourself often takes longer, not shorter. Homeowners who go back and forth with a desk adjuster for months usually end up further from resolution than when they started. Our involvement typically compresses that timeline because we present a complete, properly documented claim the first time — which removes the carrier's most common reason for delay: 'we need more information.'
My Claim Was Denied Or Underpaid — Can A Public Adjuster Clayton NC Homeowners Trust Still Help After The Fact?
Yes, and this is actually one of the most common situations that brings people to For The Public Adjusters, Inc. A denial or a low settlement is not the end of your claim. In North Carolina, you generally have three years from the date of loss to pursue a property claim, and most policies allow supplemental claims when additional damage or costs are discovered.
When we take on an underpaid claim, we start by comparing the carrier's estimate against what's actually on your property. It's routine to find missing line items — no allowance for matching shingles across roof slopes, no drywall behind wet insulation, no overhead and profit for jobs requiring multiple trades. Those gaps add up fast on a Clayton home.
Denials get a different approach. We review the denial letter against your actual policy language, because carriers sometimes cite exclusions that don't apply to the facts. A roof leak denied as 'wear and tear' may in fact trace back to a documented hail event, and weather records for the Clayton and Johnston County area can prove it.
From there, we reopen or supplement the claim with proper documentation, negotiate directly with the carrier, and if needed invoke appraisal — a policy provision that lets an independent umpire resolve the pricing dispute without a lawsuit. Bring us your denial letter, the carrier's estimate, and your policy, and we'll tell you honestly whether the claim is worth pursuing before you commit to anything.

Does For The Public Adjusters, Inc. Know The Local Market Well Enough To Price Repairs Accurately In Clayton And Johnston County?
Local pricing knowledge is exactly where many claims are won or lost, and it's a core part of what we bring to the table. Insurance carriers often price estimates using regional averages that don't reflect what contractors in Clayton, Smithfield, Garner, and the surrounding Johnston County market actually charge — especially after a widespread hail or wind event when demand spikes and labor rates climb.
We track real repair costs in this market: what a full architectural-shingle roof replacement runs on the newer neighborhoods off Cleveland Road, what mitigation companies charge for water extraction and drying, and what local trades charge for drywall, paint, and flooring. When a carrier's estimate uses stale or out-of-market pricing, we document the difference line by line and back it up.
County-specific factors matter too. Johnston County building code and permitting requirements can mandate upgrades during repairs — updated decking, ice-and-water shield, or electrical work brought to current code. If your policy includes ordinance-or-law coverage, those costs are claimable, and we make sure they're in the settlement rather than coming out of your pocket.
We also know the damage patterns here. Clayton's mix of 1990s-era subdivisions and fast-built newer construction means we know where storms tend to expose weak points — ridge caps, vinyl siding on gable ends, aging pipe fittings in slab homes. That familiarity means our inspections catch damage a five-minute drive-by from an out-of-town adjuster never will.
What Should I Do Immediately After Storm Or Water Damage To My Clayton Home Before The Claim Gets Underway?
First, make sure everyone is safe and stop any ongoing damage if you can do so without risk. That might mean shutting off the water supply after a pipe burst or tarping a roof opening after a storm rolls through Johnston County. Insurers expect reasonable steps to prevent further loss, and documenting those steps protects you later.
Next, photograph and video everything before you move or discard anything. Capture wide shots of each room, close-ups of damaged materials, and serial numbers on ruined appliances or electronics. Keep receipts for tarps, fans, hotel stays, or any emergency repairs — those costs are often reimbursable under your policy.
Avoid signing contracts with restoration companies or contractors who show up unsolicited after a storm. Some agreements assign your insurance benefits away or lock you into pricing before the scope of damage is even established. It's wise to have your own claims representative review anything before you sign.
Finally, report the loss to your carrier promptly, but keep your initial statement factual and brief — the date, the cause as you understand it, and the general areas affected. Don't guess at causes or values. When you bring in a Clayton public adjuster early, we can handle the detailed documentation, meet the carrier's adjuster on site, and make sure the claim starts on the right footing rather than needing to be corrected later.
Will Hiring A Public Adjuster Clayton NC Policyholders Use Make My Insurance Company Treat Me Differently Or Raise My Rates?
Hiring your own representation will not raise your premiums. Rates are driven by the claim itself — the type of loss, the amount paid, and your claims history — not by who negotiates it. Whether you settle for $20,000 on your own or a properly documented $45,000 with professional help, the fact that a claim occurred is what appears in your record either way.
As for how the carrier treats you, the honest answer is that the process usually becomes more structured, not more hostile. Insurance companies handle claims involving public adjusters every day, and North Carolina law explicitly gives you the right to hire one. Once we send our letter of representation, communication runs through us, which actually reduces friction for most homeowners.
What does change is the level of scrutiny applied to the insurer's numbers. A lowball estimate that might slide past a busy homeowner in Clayton gets challenged line by line — roofing squares, drywall quantities, code-upgrade costs, matching requirements for siding or flooring. Carriers know this, and files with professional representation tend to be handled more carefully as a result.
Some policyholders worry about being labeled 'difficult.' In practice, insisting on what your policy actually owes is not difficult behavior — it's the entire point of paying premiums. Our team keeps every interaction professional and documented, which protects you and keeps the claim moving toward a fair resolution rather than a standoff.
How Is A Public Adjuster Different From The Insurance Company's Adjuster Or A Contractor's Estimate?
These three roles get confused constantly, and the differences matter to your bottom line. The adjuster your insurance company sends works for the carrier. They may be courteous and competent, but their employer pays the claim, and their scope of damage often reflects that. They also carry heavy caseloads after major storms, which means fast inspections and things get missed.
A contractor's estimate is useful, but it's a repair bid — not a claim. Contractors price the work they can see and intend to perform. They generally don't read your policy, argue coverage positions, calculate depreciation and recoverable depreciation, document code-upgrade entitlements, or handle contents and additional living expense claims. Many Clayton homeowners hand a contractor bid to their insurer and wonder why the settlement still falls short.
A licensed public adjuster is the only one of the three who works exclusively for you, the policyholder. We read the policy in full, build an independent scope of damage, price it using the same estimating platforms carriers use, and negotiate every disputed line item. We also manage deadlines, proof-of-loss requirements, and supplemental claims when hidden damage surfaces during repairs.
For a homeowner in Clayton or elsewhere in Johnston County, the practical difference shows up in the settlement. The carrier's adjuster defines what the insurer wants to pay, the contractor defines what a repair costs, and we make sure those two numbers actually meet — with your policy rights fully enforced along the way.
Are There Deadlines I Need To Worry About When Filing Or Disputing A Property Claim In North Carolina?
Yes, and missing them can cost you the entire claim. North Carolina generally allows three years from the date of loss to bring legal action on a property insurance claim, but your individual policy may impose shorter contractual deadlines — some as tight as one or two years. The suit-limitation clause buried in your policy language controls, so it needs to be read carefully.
Beyond the big deadline, there are smaller ones throughout the process. Most policies require 'prompt' notice of loss, submission of a signed, sworn proof of loss within a set window (often 60 days of the carrier's request), and cooperation with inspections and document requests. Recoverable depreciation typically must be claimed within a specific period after repairs are completed — commonly 180 days to a year — or you forfeit that money entirely.
Storm claims in Johnston County add another wrinkle. After hurricanes or major hail events, homeowners sometimes don't discover roof or water intrusion damage for months. The clock generally runs from the date of loss, not the date of discovery, so waiting to investigate can quietly burn through your window to file or reopen.
If a claim was underpaid or denied, you usually have time to challenge it — but less than people assume. A public adjuster Clayton NC property owners bring in early can map every deadline in your specific policy, get sworn documents filed correctly, and keep the carrier from running out the clock. When in doubt, have the policy reviewed now rather than after a deadline passes.
What Documents Should I Gather Before Meeting With A Public Adjuster Clayton NC Property Owners Call For Help?
Start with your full insurance policy — not just the declarations page. The declarations page shows your coverage limits, but the endorsements and exclusions buried deeper in the policy often decide what actually gets paid. If you can't find your copy, your carrier is required to provide one on request.
Next, pull together anything that documents the loss itself. Photos and videos of the damage, dated if possible, are the most valuable. If you have pre-loss photos of your home — even casual family pictures showing the roof, flooring, or kitchen — those help establish the condition of the property before the event.
Also gather any paperwork that's already changed hands: the claim number, letters or emails from the carrier, the insurance company adjuster's estimate if one was issued, and receipts for emergency repairs like tarping or water extraction. If you've had contractors out, bring their written estimates too.
Don't worry if you're missing pieces. When homeowners in Clayton bring us an incomplete file, we know how to request the rest and reconstruct the timeline. Part of what we do is organize the claim so nothing gets lost in the back-and-forth with the carrier.
One more tip: keep a simple log of every phone call with your insurance company — date, name, and what was said. That log becomes surprisingly useful if the claim is later disputed, and it takes only a minute to maintain.
Do You Serve Areas Beyond Clayton, Like Garner, Smithfield, And The Rest Of Johnston County?
Yes. While much of our work is concentrated in Clayton itself — including the fast-growing neighborhoods off Highway 42 and around Flowers Plantation — we handle claims throughout Johnston County and the surrounding area.
That includes Smithfield, Selma, Archer Lodge, Wilson's Mills, Four Oaks, and Benson, along with nearby Wake County communities like Garner and southeast Raleigh. The storm systems that hit this region don't respect town lines, and neither do we. A hailstorm that tears through Clayton typically damages roofs in Archer Lodge and Wilson's Mills on the same afternoon.
Working across the county actually strengthens the claims we build. When we've documented hail or wind damage on dozens of nearby properties from the same weather event, it's much harder for a carrier to argue your damage came from something else. We keep records of local storm dates and patterns for exactly that reason.
Local coverage also matters for repair pricing. Labor and material costs in Johnston County differ from what national estimating software assumes, and rural properties outside the Clayton town limits often carry additional costs for access and logistics. We adjust our estimates to reflect what contractors here actually charge.
If you're unsure whether your property falls within our service area, just call. We'll give you a straight answer, and if your situation is outside what we handle, we'll point you toward someone reputable rather than waste your time.
Can For The Public Adjusters, Inc. Handle Commercial And Rental Property Claims, Or Only Owner-Occupied Homes?
We handle both. Alongside residential claims, we represent owners of commercial buildings, rental houses, small apartment properties, churches, and retail spaces throughout Clayton and Johnston County.
Commercial and rental claims tend to be more complicated than homeowner claims, which is exactly why professional representation pays off. A business policy often includes business interruption coverage, loss of rents, code upgrade provisions, and equipment coverage — categories that carriers frequently underpay or overlook entirely if no one pushes back with documentation.
For landlords, the loss-of-rents calculation is a common sticking point. If a fire or storm makes your Clayton rental uninhabitable, you're entitled to recover the income you lose during repairs, but only if that loss is documented and claimed correctly. We build that portion of the claim alongside the physical damage estimate so nothing is left on the table.
For business owners, downtime is often the bigger financial hit than the damage itself. We work to document interruption losses with your financial records, and we push carriers to issue timely advance payments so your operation isn't strangled by a slow claims process.
The fee structure works the same way as our residential claims — contingency-based, so we're paid a percentage of what we recover for you. Whether it's a single rental house near downtown Clayton or a commercial building along Highway 70, the goal is identical: a settlement that reflects the true cost of putting your property and income back where they were before the loss.

What Happens During The First Inspection When I Hire A Public Adjuster Clayton NC Homeowners Recommend?
The first visit is a thorough, top-to-bottom inspection of your property — and it usually takes considerably longer than the insurance company adjuster's walkthrough did. Where a carrier adjuster might spend twenty minutes, we routinely spend two to three hours documenting a loss.
We start where the damage is obvious, then work outward to find what's easy to miss. After a hailstorm, that means checking not just shingles but gutters, window screens, HVAC fins, siding, and soft metals that reveal impact patterns. After water damage, we look for moisture that has migrated into wall cavities, subflooring, and insulation, because hidden saturation left unaddressed becomes a mold problem later.
Everything gets photographed and measured. We take hundreds of photos on a typical claim, along with moisture readings and detailed notes, because a public adjuster Clayton NC carriers take seriously is one who arrives with evidence, not opinions.
Before or during that visit, we also review your policy line by line. Coverage questions get answered up front: what's covered, what your deductible is, whether you have replacement cost or actual cash value coverage, and any endorsements that affect the payout.
By the end of the inspection, you'll have an honest assessment of whether your claim is worth pursuing. If the damage falls below your deductible or the policy genuinely excludes it, we'll tell you that plainly — it costs you nothing to find out, and we'd rather give you a straight answer than take on a claim that won't benefit you.
Local Relevance
Clayton sits inland, but Johnston County knows hurricanes. Remnants of Atlantic storms regularly push through this part of North Carolina, bringing the tree-on-roof losses, wind-driven rain, and Neuse River-area flooding that make up a large share of the claims we handle here. Older homes near downtown Clayton and the wave of newer construction in the surrounding subdivisions each fail differently — aging roofs and plumbing in one, builder-grade materials and grading issues in the other.
Summer heat and humidity add their own complications. A water loss that sits for even a few days in a Clayton summer can turn into a mold and contents claim far larger than the original leak, and carriers often scope only the visible damage. Flood losses along low-lying areas fall under NFIP rules rather than a standard homeowners policy, and the Federal Emergency Management Agency publishes the proof-of-loss requirements and deadlines those claims must meet — miss them and even a valid claim can be jeopardized.
We live with the same weather and the same housing stock our clients do, which is why the documentation we build reflects how losses actually unfold in this climate, not a generic checklist.
Because Clayton's rapid growth means many neighborhoods pair mature hardwoods with homes built in the last two decades, tree-strike and hurricane-remnant claims here often involve hidden structural damage — a trunk that punctures decking can shift trusses without obvious interior signs, so an independent scope before repairs begin tends to matter more than in older, tree-cleared areas.
Get An Independent Opinion Before You Settle
If your Clayton home or business has fire, water, storm, or flood damage, talk to us before you accept the carrier's number. The policy review costs nothing, and you'll know exactly where your claim stands. For The Public Adjusters, Inc. — licensed, bonded, and working only for policyholders across Johnston County.
Request Your Free Claim Review
Call us: (919) 400-6440
Helpful Resources
- NCDOI Public Adjusters Guide
- Federal Emergency Management Agency (FEMA)
- National Flood Insurance Program (NFIP)
- FEMA flood insurance and disaster assistance resources — Official federal guidance on flood coverage and NFIP claims
- North Carolina Department of Insurance consumer resources — State regulator's guidance for insurance policyholders
Our services in this city
- Arson Homeowners Claim Clayton: When The Insurance Company Investigates You Instead Of The Fire
- Fire Damage Insurance Claim Adjuster Clayton — When The Insurer's First Offer Won't Rebuild Your Home
- Water Damage Claim Dispute Clayton NC: When The Insurance Company's Adjuster Won't Budge
Last updated: August 11, 2026