
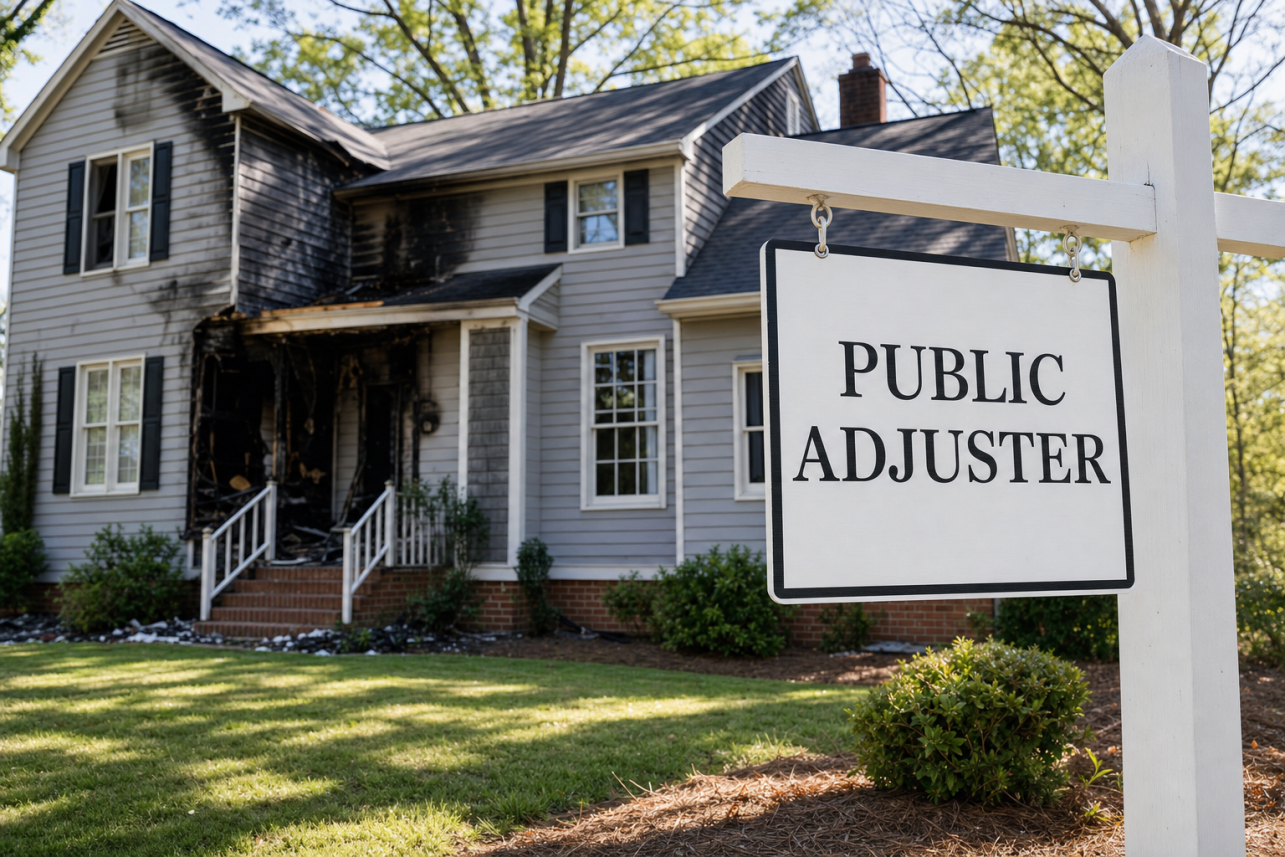
A public adjuster Rolesville NC homeowners can call is a licensed professional who works for you — not the insurance company — to document your property damage, prepare the estimate, and negotiate your settlement. For The Public Adjusters, Inc. handles fire, water, smoke, tree, flood, and hurricane-related claims for houses and businesses throughout Rolesville and Wake County. We are licensed and bonded, and we only get paid when your claim gets paid.
What This Service Is
When your home or business is damaged, the insurance company sends its own adjuster to assess the loss. That adjuster works for the insurer. A public adjuster is the licensed counterpart who works exclusively for the policyholder.
Our job starts with reading your policy the way a claims professional reads it — coverage grants, exclusions, deadlines, and the fine print on things like matching materials and code upgrades. Then we document the loss thoroughly: photographs, moisture readings after water damage, smoke residue testing, structural notes, and a room-by-room contents inventory.
From there we build a complete estimate and negotiate directly with the insurance company on your behalf. We handle residential homeowners claims and commercial business claims alike — fire, water, smoke, vandalism, arson defense of a legitimate claim, tree strikes, a car hitting your home, and hurricane or tornado damage. We do not handle claims involving cell phones, motor vehicles, health, or life insurance.
If a dispute hardens into a legal fight, we can also connect you with insurance dispute lawyers who focus on property claims, so you are never navigating a denial alone.
Common Problems
What Does Hiring A Rolesville Public Adjuster Cost — And Is It Worth The Fee?
We work on a contingency fee, meaning a percentage of what the insurance company pays. There is no hourly bill and no upfront cost, and if the claim pays nothing, you owe nothing.
The honest answer on value: policyholders who handle large losses alone often miss covered items — smoke contamination inside HVAC systems, hidden moisture behind drywall, code-required upgrades, and additional living expenses while you're displaced. A thorough claim file frequently changes what the carrier is willing to pay.
We never guarantee a specific outcome, and you should be wary of anyone who does. What we can promise is a professionally documented claim and an advocate who knows what your policy actually owes.
My Claim Was Delayed, Underpaid, Or Denied — How Does A Public Adjuster Rolesville NC Team Push Back?
Delays and lowball offers usually trace back to an incomplete file: missing documentation, a rushed carrier inspection, or a disputed cause of loss. We rebuild the file — independent estimates, photo evidence, expert reports where needed — and force the conversation back to the policy language.
Courts have repeatedly sided with policyholders when insurers cut corners on valuation. In Sproull v. State Farm Fire & Casualty Co. (2021), the Illinois Supreme Court ruled for a homeowner whose storm-damaged property payment had been reduced by depreciating labor costs, holding that labor cannot be depreciated when calculating actual cash value. Cases like that matter because they show underpayment tactics can be challenged and beaten.
If negotiation stalls, we escalate — appraisal provisions, formal disputes, and referrals to insurance dispute lawyers when litigation is the right move.
Should I Just Handle The Claim Myself, Or How Do I Pick The Right Adjuster?
For a small, straightforward loss, handling it yourself can be reasonable. For a fire, major water intrusion, a tree through the roof, or any commercial loss, the paperwork and valuation issues get complicated fast — and mistakes early in a claim are hard to undo.
When you're comparing help, verify licensing first. The NCDOI Public Adjusters Guide explains that public adjusters in North Carolina must be licensed, and it outlines what policyholders should expect from a legitimate contract, including fee disclosures. Anyone who dodges the licensing question is telling you something.
Beyond the license, ask about experience with your specific loss type. A firm that has worked smoke damage claims knows soot migrates far beyond the burn area; a firm that has worked flood claims knows flood and homeowners policies are entirely separate. That specificity is what you're hiring.

Our Process
Free Policy And Damage Review
We start with a no-cost consultation. We read your policy, inspect the damage in person, and tell you plainly whether professional representation makes sense for your loss. If your claim is better handled on your own, we'll say so.
Documentation And Claim Preparation
We photograph and measure everything, inventory damaged contents, and bring in specialists — moisture mapping after water losses, structural evaluation after a tree strike or vehicle impact. Then we prepare a line-item estimate that reflects the true scope of repair, not a drive-by number.
Negotiation And Settlement
We present the claim, meet the carrier's adjuster on site, and negotiate every disputed line. You approve any settlement before it's accepted. If the insurer won't move, we pursue appraisal or connect you with property-claim attorneys — you always know the next step.
| Claim Factor | Going It Alone | With For The Public Adjusters |
|---|---|---|
| Damage documentation | Phone photos and the carrier's own inspection notes | Moisture mapping, thermal imaging, photo logs, and licensed contractor input |
| Estimate accuracy | Whatever the insurance company's adjuster writes | Independent line-item Xactimate estimate built to actual local repair costs |
| Policy knowledge | Reading a 60-page policy under stress | Coverage review that surfaces code upgrades, matching, ALE, and business income provisions |
| Negotiation leverage | One homeowner vs. a trained claims department | Licensed NC adjuster who negotiates carrier tactics daily |
| Time commitment | Weeks of calls, emails, and re-inspections on your own | We manage every carrier communication and meeting for you |
| Typical result | Accepting the first or second offer | Documented supplements pursued until the settlement matches the real scope of loss |
Commonly Overlooked In The Public Adjusting Industry
- Ordinance or law (code upgrade) coverage — Carriers estimate repairs to pre-loss condition, but Wake County code often requires upgraded electrical, framing, or venting that this separate coverage pays for — if someone claims it.
- Matching of continuous materials — Insurers pay to patch one slope of shingles or one room of flooring, ignoring that discontinued or unmatched materials can trigger full replacement under North Carolina claim practices.
- Hidden damage behind finished surfaces — Field adjusters rarely open walls or enter crawlspaces, so saturated insulation, wet subfloor, and mold growth get scoped as zero until someone documents them.
- Additional living expenses beyond the hotel bill — ALE covers the difference in meals, mileage, pet boarding, and laundry costs during displacement, but homeowners only submit the hotel receipt because nobody explains the rest.
- Depreciation recovery (recoverable depreciation) — Thousands of dollars in withheld depreciation go unclaimed every year because policyholders don't realize they must submit completed-repair documentation to get the second check.
- Contents inventory at replacement cost — People list big-ticket items from memory and forget hundreds of smaller belongings, then accept depreciated values instead of the replacement-cost figures their policy actually owes.
- Detached structures and site improvements — Fences, sheds, mailboxes, irrigation lines, and landscaping damaged in the same storm fall under separate coverage limits that initial estimates routinely skip.
- Claim filing and supplement deadlines — North Carolina policies impose proof-of-loss and suit-limitation timelines that quietly expire while a homeowner waits on hold with the carrier.
Case Studies
Case Study #1
Situation: A family off Rogers Road in Rolesville came home from a weekend trip to find their upstairs laundry supply line had burst, sending water through the second floor, the kitchen ceiling below, and into the crawlspace.
Problem: The carrier's field adjuster wrote an estimate for $18,400 that covered drying and drywall patching but excluded the hardwood flooring, claiming only a small section was 'directly affected.' The homeowners were told the rest of the floor could be spot-repaired, which would have left a visibly mismatched patchwork through connected rooms.
Investigation: Our team performed moisture mapping with thermal imaging and pin meters, documented cupping across the continuous hardwood run, and pulled the flooring manufacturer's specs showing the product line had been discontinued. We also inspected the crawlspace, where the carrier's adjuster never went, and found saturated insulation and elevated wood moisture in the subfloor.
Findings: The moisture readings proved damage extended well beyond the carrier's marked area. Because the hardwood ran continuously from the hallway through the kitchen and living room with no transitions, North Carolina's matching considerations supported replacing the full continuous run. The crawlspace damage was completely absent from the carrier's scope.
Solution: We prepared a line-item Xactimate estimate with photo documentation tied to each room, submitted the manufacturer's discontinuation letter, and requested a re-inspection with the carrier's adjuster present while we walked the crawlspace together.
Outcome: The claim settled at $67,200 — more than three and a half times the original offer — covering full hardwood replacement, crawlspace remediation, code-required upgrades, and additional living expenses for the two weeks the kitchen was unusable.
Lesson: A carrier estimate is a starting position, not a final answer. Continuous flooring, hidden crawlspace damage, and discontinued materials are exactly the items that quietly disappear from an initial scope unless someone documents them properly.
Case Study #2
Situation: A small business owner operating a strip-center restaurant near Main Street in downtown Rolesville had significant roof and interior damage after a spring hailstorm swept through eastern Wake County.
Problem: The insurance company acknowledged the roof damage but denied the interior water staining and equipment losses, arguing the interior damage was 'pre-existing' and 'wear and tear.' They also ignored the business income portion of the policy entirely, and the owner was losing revenue every day the dining room stayed partially closed.
Investigation: We obtained the certified weather data for the storm date, put a licensed roofer on the roof with us to photograph fresh hail impacts and displaced membrane, and traced water intrusion paths from the breach points to the interior stains. We then reconstructed the restaurant's revenue using twelve months of POS reports and prior-year comparisons to build the business interruption claim.
Findings: The hail impact pattern and fresh granule displacement were consistent with the documented storm date, not gradual wear. The interior stains lined up directly beneath the compromised roof sections. The policy carried business income coverage with extended period of indemnity that the carrier had never once mentioned to the insured.
Solution: We filed a formal supplement with the weather certification, causation photos, and the business income worksheet, then invoked the policy's appraisal-adjacent negotiation steps to force a substantive response rather than a form-letter denial.
Outcome: The carrier reversed its interior denial, paid for full roof replacement rather than repair, and issued a business interruption settlement covering lost income during closure and the ramp-back period. Total recovery exceeded $214,000 against an initial position of roughly $41,000.
Lesson: Commercial policyholders often never learn what their own policy covers. Business income, extra expense, and extended indemnity provisions are frequently left unpaid simply because nobody presented the claim for them.
| Your Situation | Do You Likely Need Us? | What It Depends On |
|---|---|---|
| Small claim under your deductible or barely above it | Probably not | If repairs cost less than or near your deductible, filing may not be worth it — we'll tell you honestly in a free review |
| Carrier offer feels low but you have a contractor bid | Yes, before you sign anything | The gap between the carrier's estimate and a real local bid; gaps over 20% almost always justify representation |
| Claim denied as 'wear and tear' or 'pre-existing' | Yes, immediately | Whether causation evidence (weather data, plumber records, moisture readings) can be documented before it disappears |
| Water damage with possible hidden or mold issues | Yes, before demolition starts | Damage behind walls and under floors must be documented in place — once it's torn out, proof is gone |
| Large fire or storm loss with displacement | Yes, from day one | Fire claims involve contents inventories, ALE, and code upgrades that carriers rarely volunteer to pay |
| Business property damage with lost revenue | Yes | Business income and extra expense coverage requires financial reconstruction most owners can't build alone |
| Claim already settled but repairs cost more | Maybe — call us | NC allows supplemental claims within policy time limits; reopening depends on your policy language and how long ago you settled |
| Carrier is unresponsive or delaying for months | Yes | Documented delay patterns strengthen your position; a licensed adjuster forces deadlines the carrier must answer to |


Reviews
After the tornado-warned storm last April dropped a pine onto our roof in the Averette Ridge area, our insurer offered $9,000 for what turned out to be a $38,000 repair. For The Public Adjusters found structural damage to the trusses the first adjuster never even looked at. They handled every call and email with the carrier, and we ended up with our full roof replaced plus the ceiling repairs inside. I honestly didn't know hiring our own adjuster was an option until a neighbor mentioned it.
Denise M., Rolesville
We had a slow pipe leak behind the master bathroom wall that turned into a mold situation. The insurance company tried to deny it as 'long-term seepage.' These folks brought in moisture documentation and plumber records proving when the failure actually happened, and got the denial overturned. The settlement covered the remediation, the rebuild, and the hotel stays. Worth every penny of their fee.
Carlos R., Wake County
Hail totaled our roof and dinged up the siding, but the carrier only wanted to pay for one slope. For The Public Adjusters documented impacts on every elevation and pushed for a full replacement since the shingle color couldn't be matched. It took a re-inspection and about six weeks of back and forth, but they got it done. Only reason for four stars instead of five is I wished for more frequent status updates mid-claim, though the result was excellent.
Tammy W., Rolesville
Frequently Asked Questions
What Does A Public Adjuster Rolesville NC Homeowners Can Hire Actually Do For My Insurance Claim?
A public adjuster works exclusively for you, the policyholder — never for the insurance company. When you file a property damage claim, your insurer sends its own adjuster whose job is to settle the claim in the company's interest. We level that playing field.
For The Public Adjusters, Inc. handles the entire claim from start to finish. We inspect your property, document every item of damage with photos, measurements, and moisture readings, review your policy line by line to identify all applicable coverages, and prepare a detailed, itemized estimate using the same software carriers use.
Then we negotiate directly with the insurance company on your behalf. That means no confusing phone calls, no lowball offers you feel pressured to accept, and no missed deadlines that could jeopardize your claim.
In Rolesville, we most often see wind and hail damage from spring and summer storms rolling through Wake County, plus water damage from burst pipes, appliance failures, and roof leaks. Many of the homes in newer subdivisions off Rogers Road and Main Street have architectural shingle roofs that carriers frequently under-scope after hailstorms — approving a few shingles when the entire slope needs replacement.
We catch those gaps. Our job is to make sure the settlement reflects the true cost of restoring your home to its pre-loss condition, including code upgrades, matching materials, and hidden damage the carrier's adjuster may have overlooked or ignored.
How Much Does It Cost To Hire A Public Adjuster In Rolesville, And Is It Worth It?
We work on contingency, which means you pay nothing upfront and nothing out of pocket. Our fee is a percentage of the settlement we recover for you, agreed to in writing before we begin. If we don't recover money for your claim, you don't owe us a fee. North Carolina regulates these fees, and every agreement we sign complies with state law.
Is it worth it? Consider the math. Studies of claim outcomes consistently show that professionally represented policyholders recover significantly more than those who handle claims alone — often several times the carrier's initial offer on larger losses. Even after our fee, most clients net far more than they would have accepted on their own.
Here's a common Wake County example: a hailstorm damages your roof, gutters, window screens, and HVAC condenser fins. The carrier's adjuster writes an estimate for a partial roof repair and misses the rest entirely. We document all of it, invoke the matching and code-upgrade provisions in your policy, and the claim value often doubles or triples.
There's also the time factor. A properly documented claim in Rolesville can involve dozens of phone calls, inspections, supplement requests, and written responses over weeks or months. We handle all of it while you go on with your life.
For small claims near your deductible, we'll tell you honestly if hiring us doesn't make financial sense. Our initial claim review is free, so you lose nothing by asking.
My Insurance Company Already Sent Their Adjuster — Is It Too Late To Bring In A Rolesville Public Adjuster?
No, it's not too late. In fact, this is exactly when many of our Rolesville clients call us — after the carrier's adjuster has inspected, the estimate has arrived, and the number seems far too low to actually repair the damage.
We can step in at any stage of an open claim. If you've received an offer you haven't accepted, we can reinspect the property, prepare our own detailed estimate, and negotiate a revised settlement. If you've already received a partial payment, that doesn't close the door either — most policies allow supplemental claims when additional damage or costs are documented.
Even claims that were denied outright can often be reopened. North Carolina generally allows three years from the date of loss to pursue a property claim, though your specific policy may set shorter internal deadlines, which is one of the first things we check.
A typical scenario we see in Wake County: a homeowner near Granite Falls Boulevard gets a check for a few thousand dollars after storm damage, then their roofer says the real repair cost is triple that. We document the shortfall, submit a supplement with photo evidence and line-item pricing, and push the carrier to pay what the policy actually owes.
The one situation where our hands are tied is if you've already signed a full and final release. Before you sign anything or cash a check marked "final settlement," call us for a free review. It costs nothing and could preserve thousands of dollars in additional recovery.
What Types Of Property Damage Claims Do You Handle In Rolesville And The Surrounding Wake County Area?
For The Public Adjusters, Inc. handles residential and commercial property claims of nearly every kind across Rolesville, Wake Forest, Youngsville, Zebulon, and the greater Wake County area.
Storm damage tops the list. Rolesville sits in a corridor that regularly catches severe thunderstorms, straight-line winds, and hail moving across the Triangle. We handle roof damage, siding and gutter damage, fencing, tree impact, and the interior water damage that follows when a compromised roof lets rain in.
Water losses are our second-biggest category — burst supply lines, water heater failures, washing machine hose breaks, and slow leaks behind walls. These claims are frequently underpaid because carriers dispute the scope of drying, tear-out, and mold remediation. Proper moisture mapping and documentation make an enormous difference.
Fire and smoke claims are among the most complex we handle. Beyond structural repairs, these involve contents inventories, smoke and soot cleaning protocols, additional living expenses while you're displaced, and often code-required upgrades during rebuilding. Families dealing with a fire shouldn't also have to become claims experts overnight.
We also handle lightning strikes, hurricane and tropical storm remnants that push through central North Carolina, vandalism, theft, and vehicle-into-structure impacts.
Because every case starts with a free, no-obligation policy and damage review, you'll know before signing anything whether your claim has real recoverable value. As a public adjuster Rolesville NC property owners can reach quickly, we can typically inspect local losses within days — often before the carrier's adjuster ever arrives.
How Long Will My Claim Take Once I Hire A Public Adjuster Rolesville NC Property Owners Trust?
Most residential claims we handle in Rolesville resolve within 30 to 90 days of our involvement, though the timeline depends on the damage severity, the carrier, and how the claim was handled before we stepped in.
North Carolina law gives insurers specific deadlines. Once a proof of loss is submitted, carriers are expected to acknowledge, investigate, and respond promptly, and we hold them to those timelines in writing. A straightforward hail or wind claim on a roof in Carlton Pointe or Heritage might wrap up in about a month. A large fire loss or a disputed water damage claim with hidden structural issues can take longer because we document everything before settling.
Here's what actually saves time: we prepare a complete, itemized estimate up front using the same software carriers use, so there's less back-and-forth over scope. Missing documentation is the number one cause of delays, and it's the first thing we fix.
If your claim was already denied or lowballed before you called us, expect the process to run longer, sometimes several months, because we're essentially rebuilding the file and may need to invoke appraisal under your policy. We'll give you an honest timeline estimate during your free initial review, and we update you at every stage so you're never wondering where things stand. Our goal is a full and fair settlement, not just a fast one, but we push carriers hard to keep things moving.
What Should I Do Right After Storm Or Water Damage To My Rolesville Home, Before An Adjuster Arrives?
First, make sure everyone is safe and address any emergency hazards like active leaks, exposed wiring, or standing water near outlets. Then start documenting immediately, because the condition of your property in those first hours is your strongest evidence.
Take wide photos of every affected room, then close-ups of specific damage. Video walkthroughs help too. If a storm rolled through Rolesville or eastern Wake County, photograph the exterior, roof line, gutters, and any debris in the yard while it's still there.
Your policy requires you to mitigate further damage, so it's fine to tarp a roof, extract water, or board a window. Keep every receipt, since those emergency costs are typically reimbursable. What you should not do is start permanent repairs or throw away damaged belongings before the loss is fully documented. Discarded items are one of the most common reasons contents claims get shortchanged.
Be careful about signing anything early on, especially assignment-of-benefits paperwork from contractors who show up after a storm. Those documents can limit your options later.
Then call us. When For The Public Adjusters, Inc. gets involved early, we can be present for the insurance company's inspection, make sure nothing gets missed, and set the claim up correctly from day one. Early involvement almost always produces a smoother claim and a better outcome than trying to fix a mishandled file months later.
Can You Reopen A Claim That Was Denied Or Underpaid Before I Found You?
Yes, in most cases. A denial or a low settlement offer is rarely the end of the road, and reopening underpaid claims is a significant part of what we do for Rolesville homeowners.
In North Carolina, you generally have three years from the date of loss to pursue a property claim, though your specific policy may set its own suit-limitation period, so the sooner you call, the more options you have. Even if you already cashed a check, most policies allow supplemental claims when additional covered damage is documented.
Our process starts with a free review of your policy, the carrier's estimate, and the denial or settlement letter. Denials often rest on thin reasoning: a five-minute inspection, a misapplied exclusion, or an engineer report that never addressed the actual damage. We re-inspect the property ourselves, build a complete estimate, and submit a formal supplement or dispute backed by photos, measurements, and policy language.
When a carrier still won't move, we can invoke the appraisal clause in your policy, a dispute-resolution process that frequently resolves valuation disagreements without litigation. If the issue is coverage rather than value, we'll tell you honestly and, when appropriate, refer you to an attorney we trust.
Working with a public adjuster Rolesville NC families can call after a denial costs you nothing up front. We work on contingency, so if we can't recover more for you, you don't owe us a fee.

Is Your Team Licensed In North Carolina, And Why Does That Matter For A Wake County Claim?
Yes. Every adjuster at For The Public Adjusters, Inc. is licensed by the North Carolina Department of Insurance, which is a legal requirement for anyone negotiating an insurance claim on a policyholder's behalf in this state. You can verify any public adjuster's license directly through the Department's online lookup, and we encourage you to do exactly that before hiring anyone.
Licensing matters more than most homeowners realize. North Carolina caps public adjuster fees, requires written contracts with clear cancellation rights, and mandates continuing education. An unlicensed "claim consultant" or a contractor negotiating your claim isn't bound by any of that, and using one can actually jeopardize your claim.
Local knowledge matters too. Rolesville sits in a part of Wake County that's grown fast, which means a mix of newer construction in neighborhoods like Averette Ridge and older homes near downtown. We know how carriers treat hail claims on architectural shingles common in newer builds, how they scope water losses in homes with finished bonus rooms, and what local rebuild costs actually look like with current Wake County labor and material pricing.
When a carrier's estimate uses regional pricing that doesn't reflect what Rolesville contractors actually charge, we challenge it line by line. That combination of state licensing, fee protections, and genuine local experience is exactly what you should demand from anyone handling your claim, whether it's us or someone else.
Will Hiring A Public Adjuster Rolesville NC Residents Recommend Cause My Insurance Company To Raise My Rates Or Cancel My Policy?
No. In North Carolina, insurers cannot legally raise your premium or cancel your policy simply because you hired professional representation for a claim. Filing a legitimate claim is a contractual right you paid for, and bringing in an advocate to document that claim properly does not change your risk profile.
Rate increases in Wake County are typically driven by regional loss trends — things like the hailstorms that have swept through eastern Wake in recent years — not by whether an individual policyholder had help negotiating a settlement. Your neighbors on the same street are subject to the same territorial rating whether they filed a claim or not.
What we often see is the opposite concern playing out: homeowners in Rolesville accept a low first offer because they're afraid of "making waves," then discover months later that the payout didn't cover the actual repair cost. At that point they're paying out of pocket for damage their policy should have covered.
For The Public Adjusters, Inc. works within the terms of your existing policy. We're not asking the carrier for anything you're not entitled to — we're documenting the full scope of the loss so the settlement matches what the policy actually promises. Insurers deal with licensed adjusters like us every day. It's a normal, professional part of the claims process, and it doesn't flag you as a problem policyholder.
Do I Have To Accept My Insurance Company's First Settlement Offer On My Rolesville Claim?
Absolutely not, and in most cases you shouldn't — at least not before someone independent has reviewed it. A first offer is exactly that: a starting figure based on the carrier's own inspection, which is often brief and can miss significant damage.
We regularly review initial estimates for Rolesville homeowners that leave out entire categories of loss. Common gaps include hidden moisture behind drywall after a pipe break, wind-lifted shingles that weren't visibly torn, matching costs when discontinued siding or roofing can't be patched to blend with the rest of the home, and code-upgrade requirements Wake County enforces during permitted repairs.
Under your policy, you have the right to dispute the carrier's scope and pricing. Accepting a check is not always the end of the road either — many claims can be supplemented if new damage is documented — but it's far easier and faster to get the number right before you agree to it.
Our process is straightforward: we inspect the property ourselves, build a line-item estimate using the same industry pricing platforms the insurance companies use, and compare it against their offer. If the gap is small, we'll tell you honestly that the offer is fair. If it's substantial — and it frequently is — we negotiate directly with the carrier on your behalf. Before you sign anything or cash a settlement check, a free review costs you nothing and can reveal exactly what the first offer left on the table.
What Documents And Information Should I Have Ready Before My First Meeting With Your Team?
The more you can gather up front, the faster we can move, but don't delay calling us just because your paperwork is incomplete. We can retrieve most of what's missing directly from your carrier.
The most useful items are: your full insurance policy, including the declarations page and all endorsements; your claim number and any correspondence from the insurance company, especially their estimate or denial letter if one exists; photos or video of the damage, ideally taken as soon as it happened; and receipts for any emergency repairs, tarping, water extraction, or hotel stays.
If you have older photos showing the home's condition before the loss — even casual family pictures where the roof, floors, or ceilings are visible — those can be surprisingly valuable for proving pre-loss condition. For contents claims, bank and credit card statements help reconstruct what was lost.
Don't throw anything away yet, either. Damaged materials like waterlogged flooring, hail-dented gutters, or burned belongings are physical evidence. If they must be removed for safety, photograph everything thoroughly first and keep samples where practical.
When we sit down with Rolesville and Wake County homeowners for the first time, we walk through the policy together in plain English, explain what coverage actually applies to your situation, and map out realistic next steps. That first consultation is free, and you'll leave it understanding your claim better than most policyholders ever do — whether or not you decide to hire us.
What's The Difference Between A Public Adjuster And A Roofing Contractor Who Offers To "Handle My Insurance Claim"?
This distinction matters a lot in Rolesville, especially after a hailstorm when out-of-town roofers canvass neighborhoods door to door. A contractor's job is to repair your property. A licensed public adjuster Rolesville NC homeowners hire is legally authorized to represent you in the claim itself — interpreting your policy, preparing the estimate, and negotiating the settlement with your insurer.
In North Carolina, it is actually against the law for a contractor to negotiate your insurance claim or adjust the loss on your behalf. They can provide a repair bid, but they cannot advocate for coverage decisions, argue policy language, or handle disputes with the carrier. Some do it anyway, which can jeopardize your claim and leave you with no licensed professional accountable for the outcome.
There's also a conflict-of-interest problem. A contractor gets paid by doing the repair, so their estimate reflects the work they intend to perform — which may not capture everything your policy owes you, such as contents damage, additional living expenses, code upgrades, or interior water intrusion outside their trade.
For The Public Adjusters, Inc. is licensed by the North Carolina Department of Insurance and owes a fiduciary duty to you, not to any repair company. We document the entire loss, not just the roof, and we have no stake in which contractor you ultimately choose. The best arrangement is often both: a reputable local contractor to perform quality repairs, and our team to make sure the settlement is large enough to pay for them.
Do You Handle Commercial Claims Too, Or Does A Public Adjuster Rolesville NC Businesses Can Call Only Work On Homes?
We handle both. While much of our work in Rolesville involves residential claims, For The Public Adjusters, Inc. regularly represents commercial property owners as well — retail spaces along Main Street, offices, restaurants, churches, and light industrial buildings throughout Wake County.
Commercial claims are often more complex than residential ones. Beyond structural damage, you may have business personal property, tenant improvements, code-upgrade requirements, and business interruption losses to document. An underpaid commercial claim doesn't just shortchange your building — it can shortchange months of lost income while you're closed for repairs.
Rolesville's rapid growth means a lot of newer commercial construction, and that cuts both ways. Newer buildings may have updated code compliance, but replacement costs for modern materials and finishes are frequently underestimated by carrier adjusters working from outdated pricing databases.
We build commercial claims the same way we build residential ones: a thorough inspection, a line-item estimate using current local pricing, documentation of every covered element of the loss, and direct negotiation with the insurance company on your behalf.
If you own a business or investment property in Rolesville, Wake Forest, Zebulon, or anywhere in the Triangle, the smart move is a free claim review before you accept any settlement figure. Whether it's hail damage to a commercial roof, a kitchen fire in a restaurant, or water damage in a leased office, we can tell you quickly whether the carrier's numbers hold up — and what to do if they don't.
Are There Deadlines For Filing Or Disputing A Property Insurance Claim In North Carolina?
Yes, and missing them can cost you your entire recovery. In North Carolina, most property insurance policies require you to report a loss promptly, and the standard statute of limitations for a breach-of-contract action against your insurer is three years — though some policies attempt to shorten that window contractually, so your specific policy language matters.
Beyond the legal deadlines, there are practical ones. Policies typically require you to submit a sworn proof of loss within a set period after the carrier requests it, often 60 days. Miss that, and the insurer may have grounds to deny the claim outright, even if the damage is clearly covered.
There's also a hidden deadline that catches many Rolesville homeowners: evidence disappears. Hail bruising on shingles weathers over time, water stains get painted over, and storm dates become harder to prove. The longer you wait, the easier it is for a carrier to argue the damage is old, pre-existing, or caused by wear and tear.
Our team reviews your policy for every applicable deadline the moment we take your case, and we handle the proof-of-loss and documentation requirements so nothing lapses. If you're already close to a deadline — say you've been going back and forth with your carrier for months on a Wake County storm claim — call us immediately. We can often preserve your rights and get a stalled claim moving again, but time genuinely matters. When in doubt, don't wait until the deadline is on top of you.
I Already Received A Partial Payment And Started Repairs — Can A Public Adjuster In Rolesville Still Help Me?
In most cases, yes. Accepting a partial payment or beginning emergency repairs does not close your claim or waive your right to pursue the full amount you're owed. Insurance settlements in North Carolina can be supplemented when additional covered damage is documented, and carriers reopen and adjust payments on claims all the time.
Here's the key distinction: cashing a check for undisputed amounts is normal. What you want to avoid is signing a full and final release without understanding what you're giving up. If you haven't signed a release, your claim is almost certainly still open to supplementation.
When Rolesville homeowners come to us mid-repair, we start by comparing what the carrier paid against what the damage actually costs to fix at current Wake County labor and material prices. We photograph and document remaining damage, gather contractor invoices for work already done, and identify covered items the original estimate missed — things like matching shingles or siding, code-required upgrades, and hidden water damage discovered during demolition.
One important caution: preserve everything you can. Keep damaged materials when possible, save every receipt, and photograph conditions before contractors cover them up. Damage that's been repaired and discarded without documentation is much harder to claim.
Even if your project is nearly finished, it costs nothing to have us review the numbers. We frequently recover meaningful supplements on claims homeowners assumed were settled — and if the payment you received was actually fair, we'll tell you that honestly.

How Do You Determine What My Rolesville Property Damage Is Actually Worth?
We build your claim from the ground up rather than working backward from the insurance company's number. That difference in approach is usually where the recovery gap comes from.
It starts with a detailed physical inspection. As a public adjuster Rolesville NC property owners hire to represent them exclusively, we take the time carrier adjusters often don't — getting on the roof, moisture-mapping walls and flooring after water losses, checking attics and crawlspaces, and documenting damage that isn't visible from the ground or a quick walkthrough.
From there, we write a line-item estimate using professional estimating software with pricing current to the Raleigh-area market. Material and labor costs in a fast-growing town like Rolesville don't always match the regional averages carriers rely on, and that discrepancy alone can shortchange a claim by thousands.
We also read your policy closely. Coverage for code upgrades, matching of undamaged materials, debris removal, additional living expenses, and contents losses is frequently overlooked or underpaid. Every covered dollar gets included and supported with photos, measurements, and documentation.
Finally, we account for what's hidden. Water intrusion behind siding, insulation contaminated by smoke, decking damage beneath hail-struck shingles — these are real costs that surface during repairs, and we push to have them recognized up front rather than fought over later.
The result is a defensible, evidence-backed valuation we can negotiate from with confidence. You'll see the full estimate yourself, so you know exactly what your loss is worth before any settlement discussion begins.
Local Relevance
Rolesville sits in the heart of Wake County's growth corridor, with newer subdivisions spreading around one of the oldest incorporated towns in North Carolina. That mix matters for claims: newer builder-grade homes and older established houses fail differently, and insurers value their repairs differently too.
The climate here drives most of the losses we see. Humid summers bring severe thunderstorms and lightning strikes, remnants of Atlantic hurricanes push inland with soaking rain and downed trees, and winter ice storms snap pine limbs onto roofs and power lines. Tree damage claims and water intrusion claims are steady work in this part of the county year-round.
One point many Rolesville homeowners learn the hard way: standard homeowners policies do not cover flooding. If heavy rain sends water into a low-lying lot or finished basement, coverage comes only through a separate policy under the National Flood Insurance Program. Knowing which policy responds — and filing under the right one — is often the difference between a paid claim and a denied one.
For The Public Adjusters, Inc. serves Rolesville, Wake Forest, and the surrounding Wake County communities, and we understand how local carriers and their field adjusters handle claims in this market.
The tall loblolly pines shading many Rolesville lots become a genuine liability when hurricane remnants arrive after weeks of summer rain — saturated clay soil loosens root systems, and trees that survived the wind itself can topple onto roofs days later. Documenting both the impact damage and the hidden water intrusion that follows is where tree damage claims here are most often shortchanged.
Get A Free Claim Review In Rolesville
Before you accept the insurance company's number, let a licensed and bonded adjuster who works only for policyholders look at your loss. The consultation is free, and there's no fee unless your claim is paid. Fire, water, smoke, tree, storm, or flood — call For The Public Adjusters, Inc. today.
Call us: (919) 400-6440
Helpful Resources
- NCDOI Public Adjusters Guide
- National Flood Insurance Program (NFIP)
- North Carolina Department of Insurance — State regulator that licenses public adjusters and assists consumers
Our services in this city
Last updated: August 19, 2026